

VA whole life insurance is available through a program called VALife, which gives eligible Veterans permanent coverage of up to $40,000 with guaranteed acceptance and no medical exam. It is the VA's main whole-life option, and it works best as a base layer of protection that some Veterans choose to pair with other coverage. For Veterans in the Triad area, including Greensboro, Kernersville, High Point and Winston-Salem, understanding what VALife covers, and where it stops, makes it easier to decide whether it is enough on its own.
What Is VA Whole Life Insurance?
VA whole life insurance is permanent coverage that stays in force for your lifetime as long as premiums are paid, and the VA's current version is VALife. Like any whole life policy, it pays a death benefit to your beneficiaries and builds cash value over time.
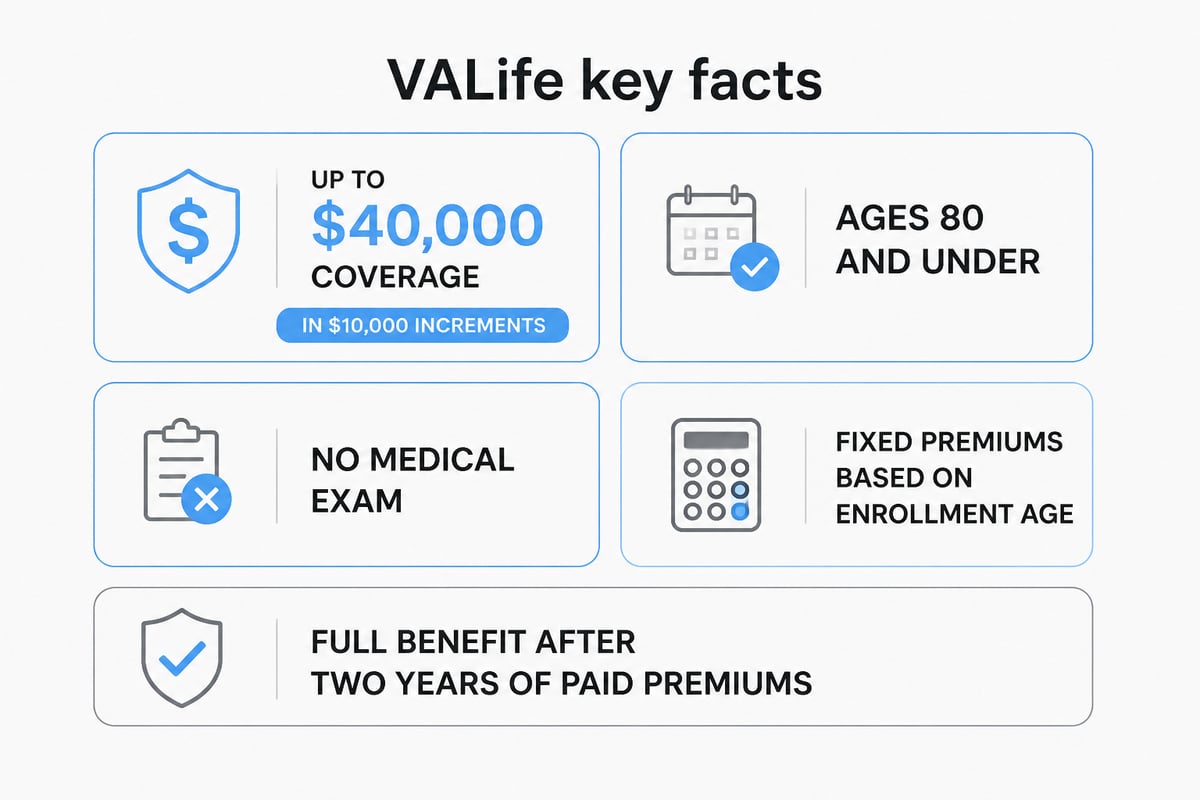
According to VA.gov, VALife offers up to $40,000 in whole-life coverage, selectable in $10,000 increments. Veterans age 80 or younger with a service-connected disability rating from 0% to 100% are eligible, and there is no application deadline. Two features set it apart from many commercial policies:
- No medical exam or health questions. VA News confirms that enrollment requires no medical exam or health questions.
- Fixed premiums. Your premium is based on your age at enrollment and the coverage amount you select, and it does not increase as you age.
The VA's overview of its life insurance programs lists VALife alongside several other options, so it helps to know how they differ.
Which VA Life Insurance Programs Exist?
The VA offers several life insurance programs, and they fall into two groups: coverage for Veterans with service-connected disabilities and coverage for those leaving the military. The most relevant to this topic are:
- VALife. Permanent whole-life coverage of up to $40,000 for Veterans with a service-connected disability rating, including a 0% rating.
- Veterans' Group Life Insurance (VGLI). Renewable term coverage for Veterans who held Servicemembers' Group Life Insurance (SGLI) while in service.
- Service-Disabled Veterans' Insurance (S-DVI). An older program for Veterans with service-connected disabilities who separated from service within a set window, with its own eligibility rules.
- Veterans' Mortgage Life Insurance (VMLI). Mortgage protection for severely disabled Veterans who received a specially adapted housing grant.
VALife is the only one of these built around permanent, lifelong coverage with guaranteed acceptance for the broadest group of disabled Veterans. VGLI is term coverage, which means it is designed to cover a period of life rather than all of it.
How Does VALife Eligibility Work?
You qualify for VALife if you are 80 or younger and hold a VA service-connected disability rating, even a 0% rating. The VA does not impose an application deadline, so you can enroll when it suits your situation.
Veterans over 80 are not automatically excluded. As VA.gov explains, you may qualify if you applied for disability compensation for a new service-connected condition before turning 81, received the rating after turning 81, and apply for VALife within two years of that rating.
Because enrollment does not depend on your health, a Veteran with a serious medical condition has the same access as one in excellent health. That guaranteed acceptance is the program's greatest strength. It also explains the waiting period described next.
What Is the Two-Year Waiting Period?
The two-year waiting period means your full VALife death benefit does not take effect until you have held the policy for two years. VA.gov states that the full face amount takes effect two years after enrollment, provided premiums are paid during that period.
The VA's guide to its life insurance options also describes this waiting period alongside the guaranteed acceptance feature. The trade-off is straightforward. Because no one is turned away for health reasons, the VA limits the payout during the early years. If you are in poor health, this matters, since a death within the first two years would not produce the full benefit.
How Much Does VA Whole Life Insurance Cost?
The cost of VALife depends on your age when you enroll and the coverage amount you choose, and the premium then stays fixed. The VA does not raise it as you grow older, which makes budgeting simple for Veterans on a fixed income.
Exact premiums vary by age and amount, so the VA's own VALife page is the best source for current figures. The practical point is that enrolling at a younger age locks in a lower rate for the life of the policy. A Veteran who enrolls at a younger age will generally pay less each month than one who enrolls later for the same amount of coverage.
For comparison, private policies with larger face amounts carry very different price tags. If you are curious about what a larger policy involves, our breakdown of the cost of a $1 million whole life policy shows how face amount, age and health drive pricing.
Is $40,000 Enough Coverage?
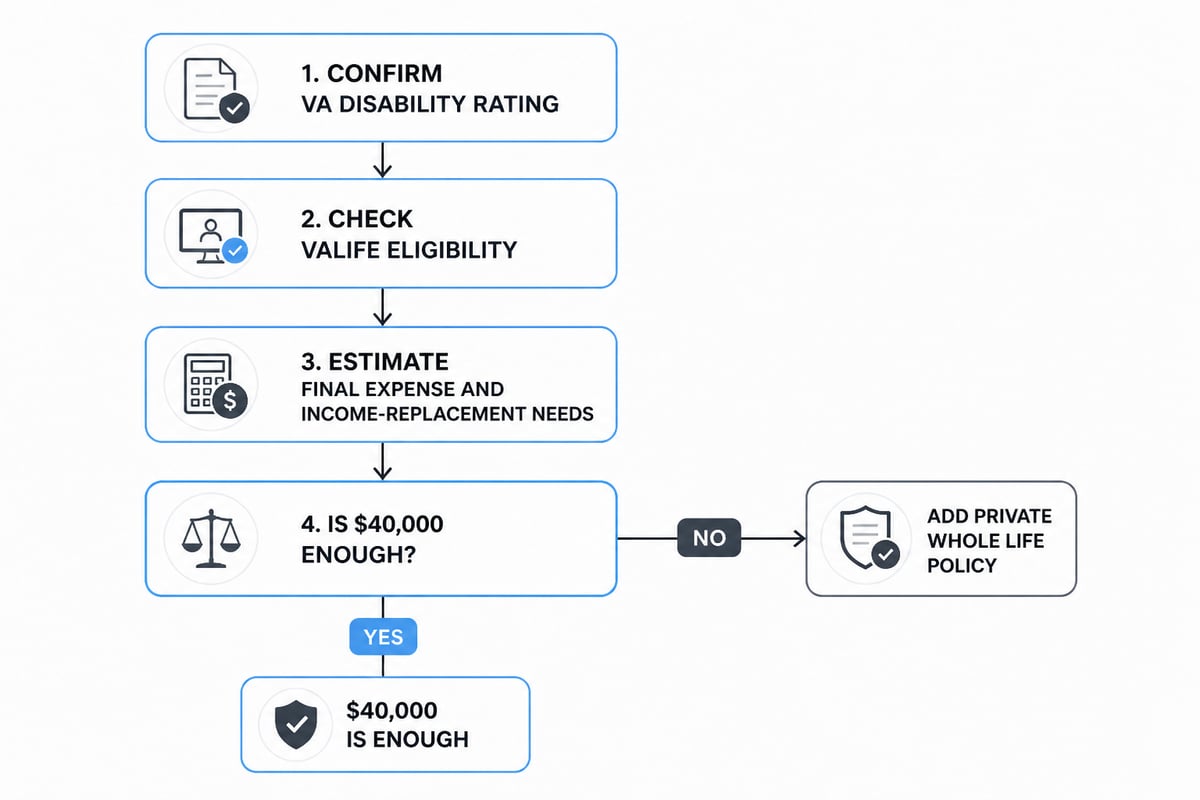
For many families, $40,000 covers final expenses but does not replace income or pay off significant debts. It can handle funeral costs, medical bills and small outstanding balances, which is exactly what many Veterans want from a whole life policy.
Consider where $40,000 falls short:
- A surviving spouse who relies on your income or pension
- A mortgage or other long-term debt
- Support for a dependent child or an adult child with special needs
- Business obligations if you own a company
Hypothetical example: a Veteran with a home loan and a spouse who depends on household income might find that a $40,000 VALife policy covers final expenses but leaves the mortgage unaddressed. In that situation, a second policy could close the gap.
How Does VGLI Compare With VALife?
VGLI is term coverage that can reach much higher amounts, while VALife is permanent coverage capped at $40,000. VGLI offers $10,000 to $500,000 in term coverage, with the available amount based on the SGLI coverage you held when leaving service, according to VA.gov.
The application window is time-sensitive. You can apply within 240 days of leaving the military without providing evidence of good health, and the overall application window runs one year and 120 days.
| Feature | VALife | VGLI |
|---|---|---|
| Policy type | Permanent whole life | Term |
| Coverage amount | Up to $40,000 | $10,000 to $500,000 |
| Health questions | None | None within 240 days of separation |
| Premium behavior | Fixed for life | Based on age bracket, per VA terms |
| Application window | No deadline | One year and 120 days after separation |
If you are recently separated and still inside the window, VGLI deserves a close look. Our page on life insurance for veterans walks through how these choices fit different situations.
When Does a Private Whole Life Policy Make Sense?
A private whole life policy makes sense when you need more than $40,000, want a guaranteed cash value schedule, or need coverage that fits a larger financial plan. Whole life is designed to last your entire life and includes a cash value savings component, which you can borrow against or use later.
Some Veterans also pursue a second policy because they want coverage tied to specific goals, such as leaving an inheritance or covering a spouse's retirement income. Moser Insurance Group Inc’s whole life insurance offering provides guaranteed protection alongside long-term cash value growth, and as an independent agency we work with multiple carriers, so you compare options in one place.
A few related questions come up often:
- If you want to understand whether the cash value is worth the premium, read our look at whether whole life insurance is a good investment.
- If you live in the Triad and want state-specific guidance, our page on North Carolina whole life insurance is a useful starting point.
- If health is a concern, a no medical exam life insurance option may work alongside your VA coverage.
Does Life Insurance Interact With Medicare?
Life insurance and Medicare are separate, so enrolling in one does not change the other. For Veterans turning 65 in Greensboro, Winston-Salem or High Point, both decisions often arrive at the same time, and it is easy to treat them as one conversation.
Medicare covers health care costs. Life insurance, including VALife, provides a death benefit to your beneficiaries. They do not replace each other, and neither affects your eligibility for the other. Veterans who use both VA health care and Medicare can also coordinate how those benefits work together, which is a separate planning question from life insurance.
Our team can help you review Medicare options and check in during the year to review your plan and Medicare changes, so you can handle both decisions in one conversation.
How Do You Apply and Name Beneficiaries?
You apply for VALife through the VA, and you name your beneficiaries on the application, which you can update later. Because there is no medical underwriting, the process is more about confirming your service-connected disability rating than answering health questions.
A few practical steps help the process go smoothly:
- Confirm your disability rating and that it is documented with the VA.
- Decide on a coverage amount in $10,000 increments, up to $40,000.
- Name a primary and contingent beneficiary, and keep both current after life events such as marriage, divorce or a death in the family.
- Pay premiums on time, especially during the first two years, so the full face amount takes effect.
Keep copies of your policy documents where a spouse or family member can find them. Many families lose time after a death simply because no one knows which policies exist.
Are VA Life Insurance Benefits Taxable?
Life insurance death benefits paid to a named beneficiary are generally not subject to federal income tax. That is true of most life insurance, and it is one reason families value it for covering final expenses and debts.
Tax treatment can vary for cash value withdrawals and for larger estates, so it is sensible to speak with a qualified tax professional about your specific situation. We can help you understand how policy features work, but tax advice itself belongs with a licensed tax advisor.
FAQ
Do veterans get lifetime benefits?
Some benefits last for life, but not every VA benefit does. VALife is permanent whole life coverage that stays in force as long as premiums are paid, while other benefits, such as VGLI term coverage or disability compensation, follow their own rules and eligibility requirements.
How much do you pay for VA life insurance?
Your VALife premium depends on your age at enrollment and the coverage amount you select, and it stays fixed for the life of the policy. The VA publishes current premium details on its VALife page, and enrolling at a younger age results in a lower monthly payment.
How much does a $1,000,000 life insurance policy cost per month?
The monthly cost varies widely with your age, health, policy type and term length.
Start by confirming your VA disability rating, then write down how much coverage your family would need beyond the $40,000 VALife maximum. If you live in the Triad area, including Greensboro, Kernersville, High Point or Winston-Salem, our independent agency can explain how private options such as whole life insurance fit alongside VA coverage and answer questions without pressure. Reach us at moserinsurancegroup@gmail.com or visit moserinsurancegroup.com, and Call/Text Now (336) 862-1763 to talk through your options with the Moser Insurance Group Inc team.
Recent Comments