
Life insurance has traditionally required extensive medical exams, blood work, and lengthy approval processes. For many individuals and families in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, this creates barriers to securing financial protection. No medical life insurance offers an alternative path to coverage that eliminates health screenings while providing peace of mind for your loved ones. Whether you're managing existing health conditions, need immediate coverage, or simply want to avoid the hassle of medical exams, these policies represent a practical solution worth understanding.
Understanding No Medical Life Insurance Fundamentals
No medical life insurance refers to policies that approve applicants without requiring physical examinations, blood tests, or comprehensive medical records review. These products have evolved significantly in 2026, with insurers using sophisticated underwriting methods that assess risk through alternative data sources.
The application process typically involves answering health questions on a simple form. Insurers evaluate your responses alongside other factors like age, coverage amount, and lifestyle indicators. This streamlined approach means you can often receive approval within days rather than weeks.
Two Primary Types of No Medical Coverage
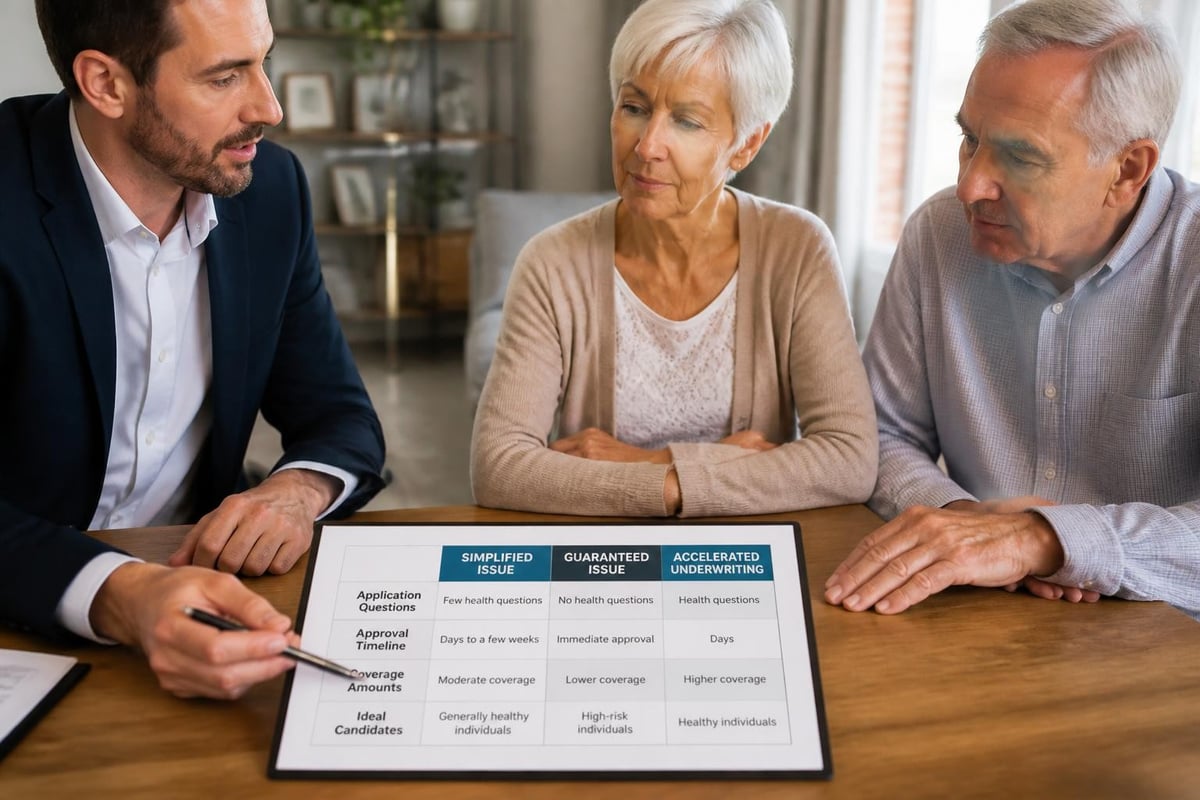
The no medical life insurance market offers distinct product categories, each serving different needs and risk profiles:
| Policy Type | Medical Questions | Approval Time | Coverage Limits | Best For |
|---|---|---|---|---|
| Simplified Issue | Yes (5-10 questions) | 24-48 hours | Up to $500,000 | Generally healthy applicants |
| Guaranteed Issue | No health questions | Immediate | $10,000-$25,000 | Serious health conditions |
| Accelerated Underwriting | Yes (detailed) | 1-7 days | Up to $1,000,000 | Healthy with digital footprint |
Simplified issue policies ask basic health questions about recent diagnoses, medications, and hospitalizations. If your answers meet the insurer's criteria, approval happens quickly without further investigation.
Guaranteed issue coverage accepts all applicants regardless of health status. These policies typically include graded death benefits, meaning full coverage doesn't activate immediately. During the first two to three years, beneficiaries receive only premium refunds plus interest if death occurs from natural causes.
How Accelerated Underwriting Works in 2026
Modern technology has transformed the no medical life insurance landscape through accelerated underwriting. Insurers now access prescription databases, driving records, and consumer data to build comprehensive risk profiles without traditional exams.
Applicants with healthy lifestyles and clean medical histories can qualify for substantial coverage amounts. The process involves:
- Completing a detailed online application
- Authorizing access to medical information databases
- Answering lifestyle and occupation questions
- Receiving instant or same-day decisions
This approach bridges the gap between fully underwritten policies and simplified products. You get competitive rates without the inconvenience of scheduling appointments or waiting for lab results.
Cost Considerations for No Medical Policies
Pricing for no medical life insurance reflects the additional risk insurers assume by forgoing medical examinations. Understanding these cost structures helps you make informed decisions about coverage value.
Premium Factors and Rate Comparisons
Age represents the most significant pricing variable. A 35-year-old non-smoker might pay $30-$50 monthly for $250,000 in simplified issue term life insurance, while a 55-year-old could pay $150-$200 for equivalent coverage.
Coverage type also impacts premiums substantially:
- Simplified issue term: 15-40% higher than fully underwritten
- Guaranteed issue whole life: 30-60% higher than traditional permanent policies
- Accelerated underwriting: 0-15% higher, sometimes matching traditional rates
Gender affects pricing as well. Women typically receive lower rates due to longer life expectancies, with savings ranging from 10-25% compared to male applicants of the same age and health profile.
Finding Affordable No Medical Coverage
The cheapest life insurance without medical exams comes from comparing multiple carriers and understanding your risk classification. Insurers specialize in different market segments, meaning one company might offer excellent rates for your specific situation while another prices you significantly higher.
Rate shopping delivers substantial savings. Consider these strategies:
- Request quotes from at least 4-5 carriers
- Compare identical coverage amounts and term lengths
- Review both monthly and annual premium options
- Investigate promotional rates for new customers
- Ask about multi-policy discounts
For residents in the Triad Area seeking guidance, working with an experienced advisor can streamline this comparison process. Contact Moser Insurance Group at 336-862-1763 or moserinsurancegroup@gmail.com for personalized rate analysis specific to your circumstances.
Who Benefits Most from No Medical Life Insurance
No medical life insurance serves specific populations particularly well. Understanding whether you fall into these categories helps determine if this coverage type aligns with your needs.
Health Conditions That Complicate Traditional Underwriting
Certain medical histories make traditional life insurance difficult or impossible to obtain. No medical policies provide alternatives when you've experienced:
- Diabetes with complications: Neuropathy, retinopathy, or kidney involvement
- Heart disease: Previous heart attacks, stents, or bypass surgery
- Cancer history: Recent diagnoses or ongoing treatment
- Mental health conditions: Depression, anxiety, or bipolar disorder requiring medication
- High blood pressure or cholesterol: Uncontrolled or requiring multiple medications
These conditions don’t automatically disqualify you from simplified issue coverage, though guaranteed issue products may offer better approval odds depending on severity.
Time-Sensitive Coverage Needs
Immediate protection requirements make no medical life insurance especially valuable. Consider these scenarios:
A new mortgage or business loan creates sudden financial obligations requiring immediate coverage. Traditional underwriting timelines of 4-8 weeks might leave your family exposed during the application period.
Upcoming travel to high-risk areas or participation in dangerous activities prompts coverage needs. Securing a policy before these events occur ensures you're protected, though some activities may require disclosure.
Family planning situations where pregnancy or adoption creates new dependent obligations. Quick approval allows coverage to begin before medical complications potentially arise.
Convenience and Privacy Preferences
Some individuals simply prefer avoiding medical appointments and invasive testing. The no medical life insurance application respects your time and privacy by eliminating:
- Paramedical examiner home visits
- Blood draws and urine samples
- Detailed physician statements
- Extensive medical records requests
- Follow-up testing for abnormal results
This streamlined approach particularly appeals to busy professionals, individuals uncomfortable with medical procedures, or those who value discretion in their financial planning.
Coverage Amounts and Policy Structures
Understanding available coverage limits helps set realistic expectations when exploring no medical life insurance options. Different policy types offer varying maximum death benefits based on underwriting approach.
Simplified Issue Coverage Ranges
| Age Range | Typical Maximum | Premium Impact | Common Use Cases |
|---|---|---|---|
| 18-40 | $500,000-$1,000,000 | Moderate | Mortgage protection, income replacement |
| 41-55 | $250,000-$500,000 | Higher | Final expenses, debt coverage |
| 56-70 | $100,000-$250,000 | Highest | Burial costs, small estate needs |
| 71+ | $25,000-$100,000 | Premium | Final expenses only |
Most carriers cap simplified issue policies around $500,000. Higher amounts typically require at least accelerated underwriting with database verification, if not full medical exams.
Term Length Options Without Medical Exams
No medical term life insurance typically offers these duration choices:
- 10-year terms: Most affordable, suitable for temporary needs
- 15-year terms: Balances cost and coverage duration
- 20-year terms: Common for mortgage protection and child-raising years
- 30-year terms: Available but less common in no medical products
Permanent no medical policies include whole life and universal life variants. These accumulate cash value over time while providing lifetime coverage guarantees. Guaranteed issue products almost exclusively fall into the permanent category due to their acceptance of all applicants.
Application Process and Approval Timeline
The streamlined nature of no medical life insurance creates efficient application experiences, though understanding the process helps avoid delays or complications.
Step-by-Step Application Journey
Initial contact and quote gathering begins with providing basic information: age, gender, desired coverage amount, and general health status. This takes 5-10 minutes through online forms or phone conversations with agents.
Detailed application completion involves answering health questions specific to the policy type. Simplified issue applications ask about recent diagnoses, surgeries, medications, and lifestyle factors. Be prepared to provide:
- Current medication names and dosages
- Dates of recent doctor visits or hospitalizations
- Details about any chronic conditions
- Tobacco use history
- Height and weight information
Review and signature can occur electronically through secure portals. Most carriers in 2026 offer completely digital processes requiring no paper documents or wet signatures.
What Happens After Submission
Modern no medical exam life insurance uses automated systems for instant preliminary decisions. You'll typically receive one of three responses:
- Immediate approval: Policy issues within 24-48 hours
- Pending review: Underwriters need additional information or clarification
- Decline with alternatives: Suggested guaranteed issue or modified products
Pending applications shouldn't cause alarm. Underwriters might simply need clarification on medication purposes or condition timelines. Responding promptly to these requests prevents delays.
Common Questions and Misconceptions
Confusion surrounds no medical life insurance, leading some individuals to avoid these products unnecessarily. Addressing these misunderstandings reveals the true value proposition.
"No Medical Exam Means Lower Quality Coverage"
This misconception stems from outdated perceptions of simplified products. Modern no medical life insurance offers identical death benefit protections as traditional policies. Your beneficiaries receive the same tax-free lump sum payment regardless of underwriting method.
The difference lies in pricing and availability, not coverage quality. Carriers use different risk assessment tools but provide equivalent financial protection when you pass away.
Coverage Limitations and Exclusions
Most no medical policies include standard exclusions during initial years:
- Suicide within the first two years (premium refund only)
- Death while committing a felony
- Misrepresentation on the application (material fraud)
Guaranteed issue products add graded benefit periods. If you die from illness during years one or two, beneficiaries typically receive returned premiums plus 10-20% interest rather than the full death benefit. Accidental death usually pays full benefits immediately.
"I Can't Get Enough Coverage Without Medical Exams"
While maximum limits exist, many families discover no medical policies provide sufficient protection. Calculate your actual coverage needs based on:
- Outstanding mortgage balance
- Other debts (car loans, credit cards, student loans)
- Income replacement for 5-10 years
- Children's education expenses
- Final expense costs ($10,000-$15,000)
For many households in Greensboro, High Point, Winston Salem, and Kernersville, $250,000-$500,000 addresses these obligations adequately. Supplementing no medical coverage with employer-provided group life insurance creates comprehensive protection.
Comparing Carriers and Making Your Selection
No medical exam life insurance companies vary significantly in their offerings, specializing in different age groups, health profiles, and coverage types. Strategic carrier selection optimizes both pricing and approval probability.
Top Considerations When Evaluating Insurers
Financial strength ratings indicate an insurer's ability to pay future claims. Review ratings from:
- AM Best (aim for A- or higher)
- Standard & Poor's (AA- or better preferred)
- Moody's (Aa3 or stronger recommended)
Customer service quality matters throughout the policy lifecycle. Research complaint ratios through your state insurance department and read current customer reviews focused on claims processing experiences.
Product flexibility determines long-term value. Look for policies offering:
- Conversion options from term to permanent coverage
- Guaranteed renewability regardless of health changes
- Living benefit riders for terminal illness
- Premium payment flexibility
Specialized No Medical Insurance Providers
Certain carriers excel in specific no medical life insurance niches. Companies focusing on older applicants (ages 50-85) typically offer better guaranteed issue rates and acceptance criteria than those targeting younger demographics.
Technology-forward insurers provide superior accelerated underwriting experiences for healthy applicants. These carriers invest in advanced algorithms and data partnerships, enabling substantial coverage amounts without exams for qualified applicants.
Regional carriers sometimes offer competitive pricing for residents in specific states. North Carolina residents might find specialized options not available nationally, making local expertise valuable when comparing quotes.
Integration with Your Overall Financial Plan
No medical life insurance functions as one component within comprehensive financial protection strategies. Understanding how these policies complement other coverage types maximizes your family's security.
Layering Coverage for Complete Protection
Combining policy types creates flexible, cost-effective coverage structures:
A base guaranteed issue policy provides permanent coverage for final expenses, ensuring burial and immediate costs are always covered regardless of when death occurs. This foundation costs less than larger permanent policies while guaranteeing essential protection.
Adding simplified issue term coverage protects against income loss and major obligations during working years. When the term expires, the guaranteed issue policy continues providing permanent benefits.
This strategy delivers comprehensive protection at lower total cost than purchasing a single large permanent policy through traditional underwriting.
Coordinating with Health Insurance and Medicare
For individuals approaching Medicare eligibility, life insurance planning intersects with healthcare coverage decisions. The resources allocated to Medicare Advantage or supplemental coverage affect available budget for life insurance premiums.
Balancing these priorities requires understanding your complete risk profile. Medical bills represent a leading cause of financial hardship, making adequate health coverage essential. However, life insurance protects your family's long-term financial stability after you're gone.
Working with advisors who understand both Medicare and life insurance helps optimize this balance. Moser Insurance Group offers guidance across these interconnected decisions, ensuring comprehensive protection aligned with your budget. Visit moserinsurancegroup.com to explore your options.
Taking Action on Your No Medical Life Insurance Needs
Understanding no medical life insurance creates value only when you convert knowledge into coverage. Implementation steps vary based on your specific situation, but following a structured approach ensures optimal outcomes.
Immediate Next Steps for Coverage Seekers
Assess your coverage requirement using these calculations:
- Multiply annual income by 10 for basic replacement
- Add all outstanding debts (mortgage, cars, credit cards)
- Include $50,000-$100,000 per child for education
- Add $15,000-$20,000 for final expenses
- Subtract existing life insurance and savings
This total represents your coverage gap that no medical life insurance should address.
Gather necessary information before beginning applications:
- List of current medications with dosages
- Dates of recent medical events (hospitalizations, surgeries, diagnoses)
- Primary care physician contact information
- Beneficiary details (names, relationships, Social Security numbers)
- Contingent beneficiary information
Request multiple quotes from carriers specializing in your age range and health profile. Comparing at least three options ensures competitive pricing and appropriate coverage recommendations.
Working with Independent Insurance Advisors
Independent agents access multiple carriers, providing broader options than captive agents representing single companies. This matters significantly in no medical life insurance, where carrier specializations create substantial rate variations for identical coverage.
An experienced advisor helps you navigate:
- Medical question interpretation and accurate completion
- Carrier selection based on your specific health history
- Application timing to maximize approval probability
- Alternative products if initial applications receive declines
- Beneficiary designation strategies for tax efficiency
For personalized guidance in the Triad Area, contact Moser Insurance Group at 336-862-1763. Their expertise across life insurance products ensures you receive education-focused recommendations rather than pressure sales tactics.
Policy Management After Approval
Your responsibilities begin when coverage starts. Maintain your policy through:
- Timely premium payments (consider automatic bank drafts)
- Updating beneficiary designations after life changes
- Reviewing coverage adequacy every 3-5 years
- Understanding your policy's features and riders
- Keeping beneficiaries informed about policy existence
Notify your insurer immediately if addresses, payment methods, or beneficiaries change. These updates prevent complications during claims processing when your family needs quick access to benefits.
Store your policy documents securely but ensure trusted family members know their location. Consider providing copies to your executor or attorney to facilitate efficient estate settlement.
No medical life insurance removes traditional barriers to coverage, providing accessible protection for individuals who might otherwise go uninsured. Whether you're managing health conditions, need immediate approval, or simply value convenience, these policies deliver meaningful financial security for your loved ones. Moser Insurance Group helps families throughout Greensboro, Kernersville, High Point, Winston Salem, and the broader Triad Area understand their life insurance options with clear guidance tailored to individual circumstances. Reach out to Moser Insurance Group today to explore how no medical life insurance fits within your complete protection strategy.
Recent Comments