

Planning for long-term financial security often includes considering substantial life insurance coverage. For families and individuals in the Triad Area, understanding the 1 million whole life insurance cost helps make informed decisions about permanent protection. Unlike term policies that expire after a set period, whole life insurance provides lifetime coverage with a cash value component that grows over time. This comprehensive guide explores pricing factors, premium expectations across different age groups, and how to evaluate whether this level of coverage fits your financial goals.
Understanding Whole Life Insurance Premiums
Whole life insurance represents a significant financial commitment that extends throughout your lifetime. The 1 million whole life insurance cost reflects both the death benefit guarantee and the policy's cash value accumulation feature.
Whole life insurance policies operate differently than term coverage because they combine protection with a savings element. Every premium payment includes:
- Death benefit coverage that pays beneficiaries tax-free
- Cash value growth that accumulates on a tax-deferred basis
- Fixed premiums that never increase regardless of age or health changes
- Guaranteed returns based on the policy's stated interest rate
Insurance carriers calculate premiums using actuarial tables that assess mortality risk, administrative costs, and investment returns. The permanent nature of whole life coverage means insurers commit to eventually paying the death benefit, which explains why premiums cost significantly more than term policies.
Key Factors That Determine Your Premium
Multiple variables influence the 1 million whole life insurance cost for any individual applicant. Understanding these factors helps you anticipate your potential premium range.
Age at Application
Your age represents the single most influential factor in premium calculations. Younger applicants pay substantially less because they present lower mortality risk over the policy's duration. A 30-year-old might pay $8,000 to $12,000 annually, while a 50-year-old could face premiums of $25,000 to $35,000 for identical coverage.
Health Status and Medical History
Insurers conduct thorough medical underwriting that includes blood work, physical examinations, and medical record reviews. Chronic conditions like diabetes, heart disease, or cancer history increase premiums or may result in coverage denial. Excellent health earns preferred rates that can reduce costs by 20-30% compared to standard classifications.
Gender Differences
Women typically pay 10-15% less than men for equivalent coverage due to longer life expectancy statistics. A 40-year-old woman might pay $17,000 annually while a 40-year-old man pays $19,500 for the same $1 million policy.
Lifestyle and Occupation
Risky hobbies like skydiving, rock climbing, or scuba diving can increase premiums or require policy exclusions. Hazardous occupations such as construction, mining, or law enforcement may also result in higher rates. Tobacco use typically doubles premium costs compared to non-smoker rates.
Premium Examples by Age Group
Examining average whole life insurance costs across different age brackets provides realistic expectations for budgeting purposes. These ranges reflect healthy non-smokers seeking $1 million coverage in 2026.
| Age Range | Male Annual Premium | Female Annual Premium | Monthly Cost (Male) |
|---|---|---|---|
| 25-30 | $7,500 – $10,000 | $6,500 – $8,500 | $625 – $833 |
| 35-40 | $12,000 – $16,000 | $10,500 – $14,000 | $1,000 – $1,333 |
| 45-50 | $20,000 – $28,000 | $17,500 – $24,000 | $1,667 – $2,333 |
| 55-60 | $35,000 – $48,000 | $30,000 – $41,000 | $2,917 – $4,000 |
These figures demonstrate how the 1 million whole life insurance cost escalates significantly with age. Residents throughout Greensboro, Kernersville, High Point, and Winston Salem can use these benchmarks when evaluating their insurance planning timeline.
Comparing Whole Life to Other Policy Types
Understanding how whole life insurance compares to alternatives helps clarify whether the premium investment makes sense for your situation.
Term Life Insurance
Term policies provide pure death benefit protection without cash value accumulation. A healthy 35-year-old might pay $600-$900 annually for a 20-year $1 million term policy, compared to $12,000-$16,000 for whole life coverage. The dramatic price difference reflects term insurance's temporary nature and lack of savings component.
Universal Life Insurance
Universal life insurance offers flexible premiums and death benefits while building cash value. The 1 million whole life insurance cost remains fixed, whereas universal life premiums can adjust based on policy performance and your payment preferences. Universal life might start with lower premiums but requires active management to prevent lapse.
Guaranteed Universal Life
This hybrid product provides permanent coverage at lower premiums than whole life, typically 30-40% less expensive. However, guaranteed universal life builds minimal cash value compared to traditional whole life policies, focusing primarily on the death benefit guarantee.
The Cash Value Component
Beyond the death benefit, whole life insurance accumulates cash value that policyholders can access during their lifetime. This feature distinguishes permanent insurance from term coverage and partially justifies the higher 1 million whole life insurance cost.
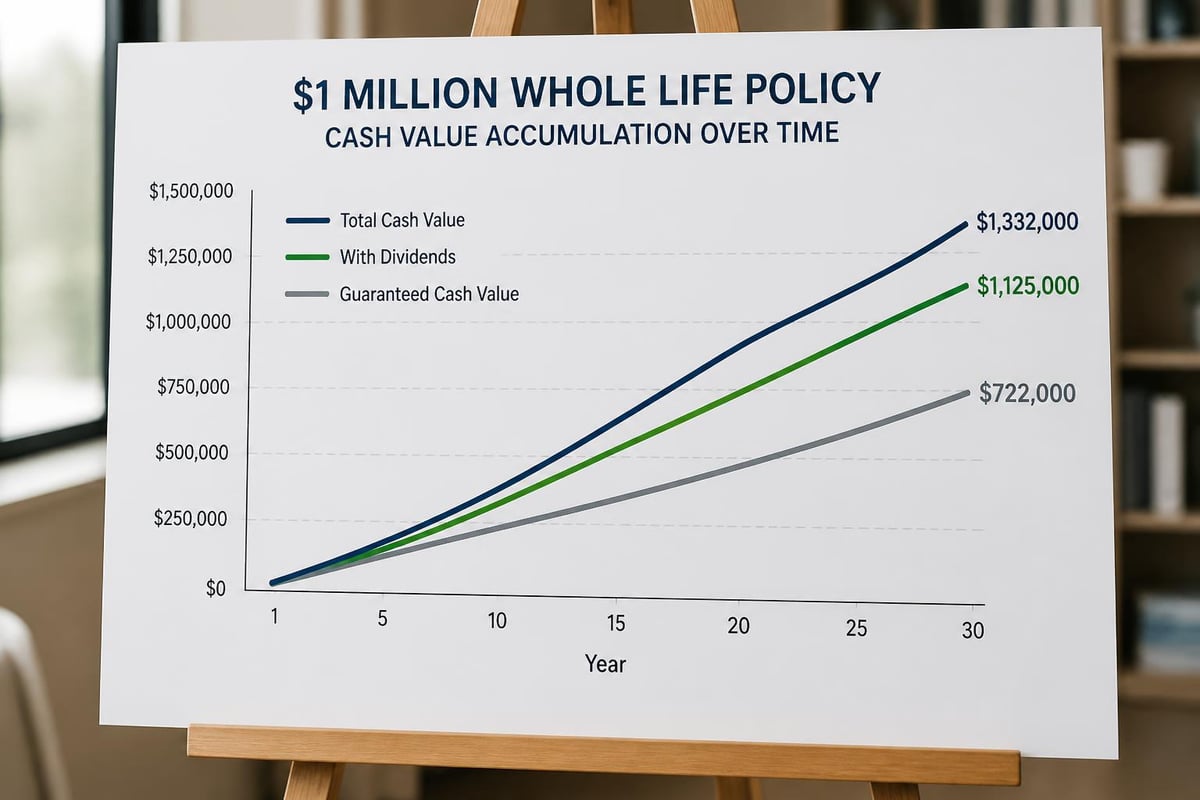
Cash value grows through guaranteed interest credits and potential dividend payments from participating policies. Most whole life contracts guarantee 2-4% annual growth, with dividends potentially adding another 1-3% depending on the insurer's financial performance.
Accessing Your Cash Value
Policyholders can utilize accumulated cash value through several methods:
- Policy loans that borrow against the cash value at competitive interest rates
- Withdrawals that permanently reduce both cash value and death benefit
- Premium payments using cash value to cover annual premiums
- Collateral for bank loans without withdrawing funds from the policy
A well-funded whole life policy might accumulate $300,000 to $500,000 in cash value over 20-30 years, providing a tax-advantaged financial resource for emergencies, retirement supplementation, or business opportunities.
Tax Advantages of Whole Life Insurance
The 1 million whole life insurance cost provides several tax benefits that enhance the policy's overall value proposition.
Cash value grows tax-deferred, meaning you don't pay taxes on interest or dividend accumulation until withdrawal. Policy loans aren't considered taxable income as long as the policy remains in force. Death benefits pass to beneficiaries completely tax-free, regardless of the million-dollar amount.
These tax characteristics make whole life insurance an attractive estate planning tool, especially for high-net-worth individuals in the Winston Salem and Greensboro areas seeking to transfer wealth efficiently to the next generation.
Who Benefits Most from Million-Dollar Coverage
Not everyone needs or should purchase $1 million in permanent life insurance. Certain situations particularly warrant considering this coverage level despite the substantial 1 million whole life insurance cost.
High-Income Earners
Families depending on six-figure incomes need substantial coverage to replace lost earnings potential. A $1 million death benefit can provide 10-15 years of income replacement for families earning $80,000-$100,000 annually, ensuring children's education funding and mortgage payments continue without financial hardship.
Business Owners
Entrepreneurs often carry whole life insurance for business succession planning, buy-sell agreement funding, or key person coverage. The cash value serves as a corporate asset while guaranteeing business continuity funds upon an owner's death.
Estate Planning Strategies
Wealthy individuals use whole life insurance to provide estate liquidity, pay estate taxes, or equalize inheritances among heirs. The guaranteed death benefit ensures funds are available regardless of when death occurs, unlike investment portfolios subject to market volatility.
Pension Maximization
Retirees can elect higher pension payouts without survivor benefits, then use a portion of the increased income to fund whole life insurance protecting their spouse. This strategy sometimes provides better overall financial outcomes than pension survivor options.
Medical Underwriting and Application Process
Securing $1 million in whole life coverage requires comprehensive medical evaluation. Understanding the underwriting process helps applicants prepare and avoid delays.
Insurance companies typically require:
- Complete medical history questionnaire
- Paramedical examination including blood and urine samples
- Electrocardiogram (EKG) for applicants over 50
- Physician's statement for pre-existing conditions
- Motor vehicle record check
- Prescription database review
The underwriting period usually takes 4-8 weeks for straightforward applications. Complex medical histories may extend the timeline to 12 weeks or longer as underwriters request additional records or specialist reports.
| Health Classification | Premium Impact | Requirements |
|---|---|---|
| Preferred Plus | 15-25% discount | Excellent health, no medications, ideal weight |
| Preferred | 10-15% discount | Good health, minor conditions controlled |
| Standard | Base rates | Average health, controlled chronic conditions |
| Substandard | 25-200% increase | Significant health issues or high-risk factors |
Residents throughout the Triad Area seeking whole life insurance should gather medical records in advance and maintain honest communication throughout the application process. Misrepresentations can void coverage even after policy issuance.
Strategies to Reduce Premium Costs
While the 1 million whole life insurance cost represents a substantial commitment, several approaches can help manage expenses without sacrificing essential coverage.
Apply at Younger Ages
Every year of delay significantly increases premiums. A 35-year-old pays approximately 40% less than a 45-year-old for identical coverage. Early application locks in lower rates for life, generating substantial lifetime savings.
Improve Health Before Applying
Losing weight, controlling blood pressure, or quitting tobacco can shift you into better rate classifications. A six-month health improvement program might reduce annual premiums by $3,000-$5,000, justifying the application delay.
Consider Blended Coverage
Combining term and whole life insurance provides $1 million total coverage at reduced cost. You might purchase $500,000 in whole life for permanent protection plus $500,000 in 20-year term coverage for peak earning years, significantly lowering total premiums while maintaining adequate protection.
Pay Annually Instead of Monthly
Annual premium payments typically save 4-8% compared to monthly installments. A policy costing $20,000 annually might cost $21,200 if paid monthly, adding $1,200 in unnecessary expenses over the year.
Work with Independent Agents
Independent insurance professionals like those at Moser Insurance Group Inc can compare multiple carriers simultaneously, identifying the most competitive rates for your specific situation. Different insurers price the same applicant differently based on their underwriting guidelines and target markets.
For personalized guidance on whole life insurance options, contact Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com. Our team serves families throughout High Point, Kernersville, Greensboro, and Winston Salem with transparent advice on permanent life insurance solutions.
Understanding Policy Riders and Enhancements
Optional riders customize whole life policies to address specific needs, though they increase the base 1 million whole life insurance cost. Common enhancements worth considering include:
Waiver of Premium Rider
This rider continues premium payments if you become totally disabled, preventing policy lapse during income interruption. Cost typically ranges from 5-10% of base premiums, making it affordable protection against disability-related coverage loss.
Accelerated Death Benefit Rider
This provision allows accessing a portion of the death benefit if diagnosed with a terminal illness, providing funds for medical care or end-of-life expenses. Many insurers include this rider at no additional cost.
Paid-Up Additions Rider
This option uses dividends to purchase additional whole life coverage, accelerating both cash value growth and death benefit increases. It represents one of the most efficient ways to enhance policy performance over time.
Guaranteed Insurability Rider
This rider permits purchasing additional coverage at future dates without medical underwriting, valuable for young applicants who anticipate needing more insurance as their income and family responsibilities grow.
Common Misconceptions About Whole Life Insurance
Several myths about permanent life insurance cause confusion when evaluating the 1 million whole life insurance cost against other financial products.
"Whole Life is Always a Bad Investment"
While whole life insurance costs more than term coverage, dismissing it as a poor investment ignores its unique benefits. The guaranteed death benefit, tax advantages, and forced savings discipline serve specific financial planning purposes that pure investment accounts cannot replicate.
"You Should Buy Term and Invest the Difference"
This common advice assumes consistent investment discipline and favorable market returns. Reality shows most people don't invest the premium difference, and whole life's guarantees provide certainty that market-based strategies cannot match.
"Cash Value Growth is Too Slow"
Early years do show modest cash value accumulation as policies recoup acquisition costs. However, year 10-20 typically demonstrates accelerating growth, with later years providing substantial returns competitive with conservative investment alternatives.
"You Can't Afford Whole Life Insurance"
Rather than viewing costs for $1 million policies as unaffordable, consider whether the coverage amount matches your actual needs. Many people benefit more from $250,000-$500,000 in whole life paired with term coverage rather than stretching budgets for the maximum death benefit.
When Whole Life May Not Be Appropriate
Despite its advantages, whole life insurance doesn't suit every situation. Understanding when alternative strategies work better helps avoid unnecessary expense.
Short-Term Protection Needs
If you only need coverage during working years to protect a mortgage or support minor children, term life insurance costs 90% less and serves the purpose perfectly. The 1 million whole life insurance cost makes sense only when permanent protection or cash value accumulation matters.
Maxed Retirement Contributions
Financial advisors typically recommend maximizing 401(k) and IRA contributions before purchasing whole life insurance for its cash value features. Tax-deferred retirement accounts offer better growth potential for most savers, with whole life serving as a supplemental savings vehicle after retirement accounts are fully funded.
Unstable Income
The fixed premium commitment requires reliable cash flow. People with variable income might struggle maintaining whole life policies during lean periods, risking policy lapse and loss of all accumulated benefits.
Very Young Children
While some parents purchase whole life insurance for children, the 1 million whole life insurance cost for adults better serves most families' protection needs. Small policies for children can make sense for insurability guarantees, but not at coverage levels that strain family budgets.
Evaluating Insurance Company Financial Strength
A whole life policy represents a multi-decade commitment, making insurer financial stability critically important. The best premium pricing means nothing if the company cannot fulfill its obligations 30-40 years from now.
Rating Agency Assessments
Review ratings from multiple agencies including A.M. Best, Moody's, Standard & Poor's, and Fitch. Look for companies rated A+ or higher from A.M. Best and AA or better from the others. These ratings assess an insurer's ability to meet policyholder obligations.
Dividend Payment History
Participating whole life policies from mutual companies have paid dividends annually for decades, demonstrating financial strength and policyholder commitment. Companies with 100+ year dividend payment histories show remarkable stability.
Policy Performance Illustrations
Request illustrations showing guaranteed versus non-guaranteed values. Conservative projections based primarily on guaranteed elements indicate realistic expectations, while illustrations heavily dependent on non-guaranteed dividends may disappoint.
Making Your Coverage Decision
Determining whether the 1 million whole life insurance cost fits your financial plan requires honest assessment of your protection needs, budget capacity, and long-term goals.
Start by calculating your actual coverage requirements based on:
- Income replacement needs for dependent family members
- Debt obligations including mortgages and business loans
- Education funding for children's college expenses
- Final expenses and estate settlement costs
- Legacy goals for wealth transfer or charitable giving
Compare the total premium outlay over 20-30 years against the guaranteed benefits provided. A $20,000 annual premium means $600,000 in total payments over 30 years, but generates $1 million tax-free to beneficiaries plus significant cash value for your use during life.
Consider your overall financial picture including emergency funds, retirement savings, and other assets. Whole life insurance works best as one component of a diversified financial strategy, not as your sole savings vehicle.
For families in Kernersville, High Point, Greensboro, and Winston Salem weighing these complex decisions, professional guidance makes a significant difference. Visit moserinsurancegroup.com to explore how permanent life insurance fits within your comprehensive financial protection plan.
Understanding the 1 million whole life insurance cost in 2026 requires evaluating your unique circumstances, health status, and long-term financial objectives. While premiums represent a substantial commitment, the guaranteed lifetime protection and cash value accumulation serve important planning purposes for many families and business owners. At Moser Insurance Group Inc, we help individuals and families throughout the Triad Area understand their life insurance options with clear guidance and personalized support, ensuring you make confident decisions about protecting your family's financial future. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss how whole life insurance can fit your comprehensive protection strategy.
Recent Comments