

Whole life insurance stands apart in the landscape of financial protection products because it offers something few other vehicles can deliver: guaranteed lifetime coverage paired with a savings component that grows tax-deferred. For families planning their financial future in the Triad Area, understanding how this permanent insurance works, what it costs, and whether it aligns with your goals is essential before making a commitment that can span decades. Unlike term policies that expire, whole life remains in force as long as you pay premiums, building cash value you can access during your lifetime while ensuring your beneficiaries receive a death benefit no matter when you pass away.
What Makes Whole Life Insurance Different
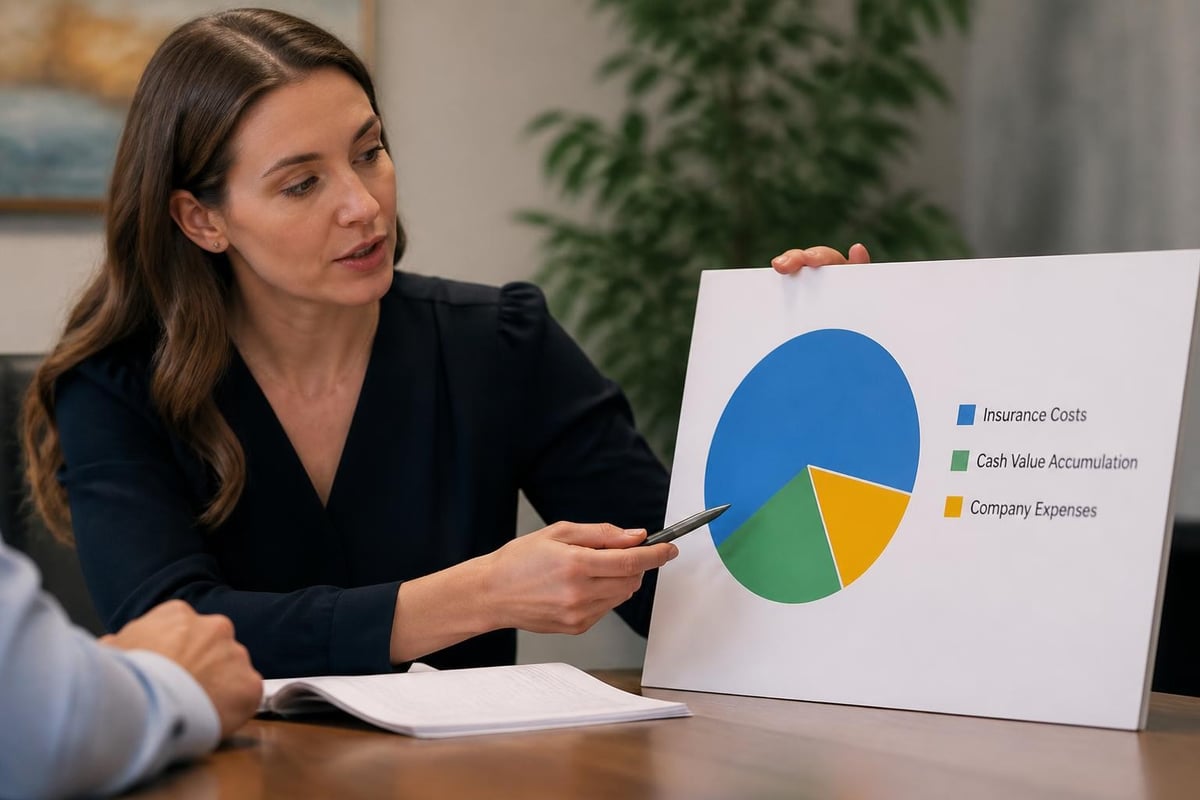
Whole life insurance is a permanent policy designed to last your entire lifetime, combining a guaranteed death benefit with a cash value account that accumulates over time. The National Association of Insurance Commissioners explains the core mechanics of how premiums are divided between insurance costs and savings, creating a unique dual-purpose financial tool.
When you purchase a policy, your premium payments serve two functions. A portion covers the actual cost of insurance, while the remainder goes into a cash value account that grows at a guaranteed minimum rate. Most insurers also pay dividends on participating whole life policies, though dividends are never guaranteed and depend on the company's financial performance.
Key features that define whole life:
- Guaranteed premiums that never increase
- Fixed death benefit that won't decrease (and may grow with dividends)
- Cash value accumulation at a guaranteed minimum rate
- Tax-deferred growth on the savings component
- Potential dividend payments from mutual insurance companies
The predictability appeals to many families in Greensboro, Kernersville, High Point, and Winston Salem who want protection that doesn't require constant reassessment or renewal decisions. You set it up once, pay consistently, and the coverage remains in place regardless of health changes or age.
How Cash Value Grows and Compounds
The cash value component distinguishes whole life from term insurance and represents a forced-savings mechanism that grows steadily. During the early years, cash value accumulates slowly because insurance costs and policy fees consume most of your premium. As decades pass, the growth accelerates through compound interest and potential dividend reinvestment.
Insurance companies guarantee a minimum interest rate on cash value, typically between 1.5% and 3.5% in 2026, though the actual crediting rate often exceeds the minimum. Mutual insurers may pay annual dividends based on investment performance, mortality experience, and operating expenses. Policyholders can take dividends as cash, use them to reduce premiums, purchase additional paid-up insurance, or leave them to accumulate at interest.
Accessing Your Cash Value
| Access Method | How It Works | Tax Implications | Impact on Death Benefit |
|---|---|---|---|
| Policy Loan | Borrow against cash value at favorable rates | No income tax on loan proceeds | Reduces death benefit by outstanding loan amount plus interest |
| Partial Withdrawal | Take cash directly from the policy | Tax-free up to basis; gains taxable | Permanently reduces death benefit |
| Full Surrender | Cancel policy and receive cash value | Gains above premiums paid are taxable | Policy terminates; no death benefit |
| Dividend Withdrawal | Take annual dividends as cash | Generally tax-free as return of premium | No direct impact if policy remains in force |
The IRS provides specific guidance on tax treatment of life insurance proceeds, loans, and surrenders, confirming that death benefits remain income-tax-free to beneficiaries and loans avoid current taxation when structured properly.
Families often use cash value to supplement retirement income, fund college expenses, or bridge financial gaps during emergencies. The ability to access funds without triggering immediate taxes makes whole life an alternative to traditional savings accounts, though the long-term commitment and early-year opportunity costs require careful consideration.
Comparing Whole Life to Term and Universal Options
Choosing between permanent and temporary coverage depends on your financial objectives, time horizon, and budget constraints. Each policy type serves distinct purposes and fits different life stages.
Whole life advantages:
- Guaranteed lifetime protection regardless of health changes
- Fixed premiums that never rise due to age or illness
- Predictable cash value growth with minimum guarantees
- Dividends that can enhance both cash value and death benefit
- No policy expiration or renewal decisions
Whole life limitations:
- Significantly higher premiums than term insurance
- Slow early cash value accumulation relative to premium cost
- Lower investment returns compared to market-based alternatives
- Reduced flexibility in premium payments and coverage adjustments
Term insurance offers maximum death benefit per premium dollar but provides no cash value and expires after 10, 20, or 30 years. Universal life provides more flexibility in premiums and death benefits but carries greater risk because cash value growth depends on current interest rates rather than guarantees. Consumer Reports examines when permanent policies make sense versus term coverage combined with separate investments, noting that whole life works best for those who need guaranteed lifetime protection and value certainty over potentially higher returns.
A 35-year-old non-smoking male in the Triad Area might pay $150 monthly for $500,000 of 20-year term coverage or $650 monthly for a comparable whole life policy. The term policy costs less initially but expires at age 55 with no residual value. The whole life contract continues indefinitely, accumulates cash value reaching approximately $200,000 by age 65 (assuming 5% dividends), and guarantees the death benefit regardless of future health status.
Understanding Premiums, Dividends, and Long-Term Costs
Premium structure on whole life policies remains level for life, meaning the amount you pay at age 40 stays identical at age 80. This predictability helps with budgeting but requires careful initial assessment of affordability across changing life circumstances.
Premium Payment Options
Most companies offer several payment structures:
- Continuous-pay (ordinary life): Pay premiums until death or age 100+
- Limited-pay (10-pay, 20-pay): Higher premiums for a set period, then policy is paid-up
- Single-premium: One large upfront payment, immediate cash value
- Paid-up at age 65: Premium payments end at retirement
Limited-pay options appeal to those who want coverage secured before retirement when income may decrease. Single-premium policies maximize early cash value but trigger modified endowment contract (MEC) status under IRS rules, changing tax treatment of loans and withdrawals.
Participating whole life policies from mutual insurers may pay annual dividends, though companies make no guarantees. The actuarial standards that govern illustration regulations require insurers to show realistic projections, not overly optimistic scenarios. Dividend scales have declined over recent decades as interest rates fell, reminding buyers that historical performance doesn't guarantee future results.
Using Whole Life for Estate Planning and Wealth Transfer
High-net-worth families often incorporate whole life into estate strategies because death benefits pass income-tax-free to beneficiaries and can provide liquidity to pay estate taxes, settle debts, or equalize inheritances among heirs.
When an estate exceeds federal exemption limits ($13.61 million per individual in 2024, indexed annually), life insurance proceeds are included in the taxable estate if the deceased owned the policy. Transferring ownership to an irrevocable life insurance trust (ILIT) removes proceeds from the estate while maintaining control over distribution terms and protecting assets from creditors.
Whole life also facilitates business succession planning. Buy-sell agreements funded with permanent insurance ensure surviving partners can purchase a deceased owner's shares at predetermined values without depleting operating capital. The guaranteed death benefit and fixed premiums eliminate uncertainty about funding availability when needed most.
For families in Winston Salem and High Point managing multi-generational wealth, whole life serves as a tax-efficient transfer vehicle. Premium payments reduce the taxable estate while building death benefits that can fund trusts, endow charitable foundations, or provide for heirs with special needs. The Federal Reserve’s Survey of Consumer Finances tracks household holdings of cash-value life insurance, showing persistent ownership among higher-income and older families who value the asset-protection and estate-planning features.
Policy Illustrations and Regulatory Transparency
When evaluating whole life proposals, you'll receive a policy illustration showing projected values under current dividend scales and guaranteed minimums. Understanding what these numbers represent and their limitations prevents unrealistic expectations.
The NAIC’s model regulation on life insurance illustrations mandates that insurers display both guaranteed and non-guaranteed elements separately, show multiple scenario outcomes, and include specific disclosure language about the hypothetical nature of projected dividends. Regulators prohibit illustrating dividend scales higher than currently paid and require companies to demonstrate that projected rates are supportable based on actual experience.
Key illustration components:
- Guaranteed columns: Minimum cash values and death benefits contractually promised
- Current assumption columns: Projected values if current dividends continue unchanged
- Premium outlay: Total amounts you'll pay over specified periods
- Cash surrender value: What you'd receive if canceling the policy
- Death benefit: Amount payable to beneficiaries at different ages
Comparing illustrations across carriers requires careful analysis because companies use different assumptions, product designs, and dividend scales. A seemingly higher projected cash value may result from aggressive dividend assumptions unlikely to materialize. Focus on guaranteed minimums, company financial strength ratings, and historical dividend stability rather than optimistic projections alone.
FINRA’s guidance on policy exchanges warns consumers about replacement transactions where agents encourage swapping existing coverage for new policies. While 1035 exchanges allow tax-free transfers of cash value between policies, new surrender charges, extended accumulation periods, and loss of valuable policy features may outweigh potential benefits. Always review replacement transactions with an independent advisor before proceeding.
When Whole Life Makes Sense for Your Situation
Whole life insurance fits specific financial profiles and objectives rather than serving as a universal solution. Evaluating whether it aligns with your needs requires honest assessment of your goals, time horizon, and alternative uses for premium dollars.
Ideal candidates for whole life coverage:
- Parents seeking guaranteed protection for minor children or dependents with special needs
- Business owners requiring permanent coverage for buy-sell agreements or key-person insurance
- High-income earners maximizing tax-advantaged savings vehicles beyond 401(k) and IRA limits
- Estate planners needing liquidity to pay taxes or equalize inheritances
- Individuals who value certainty and guaranteed outcomes over potentially higher investment returns
- Those with chronic health conditions making term renewal prohibitively expensive
Better alternatives when:
- You need maximum coverage for minimum premium (term insurance)
- Investment returns are your primary goal (term plus index funds)
- You want premium flexibility and higher potential growth (universal or variable life)
- Coverage needs are temporary (mortgage protection, income replacement during working years)
A family in Greensboro with two young children and a $300,000 mortgage might prioritize term insurance to maximize death benefit during critical earning years, then add a small whole life policy for final expenses and guaranteed legacy protection. Conversely, a 50-year-old business owner in Kernersville with substantial retirement savings may choose whole life to lock in insurability, create estate liquidity, and supplement retirement income through policy loans.
The decision hinges on whether guaranteed lifetime protection and forced savings justify the premium commitment. Whole life insurance from Moser Insurance Group Inc combines permanent coverage with cash value growth, providing families in the Triad Area with predictable protection that adapts to changing needs through loans, dividends, and flexible beneficiary arrangements.
Monitoring Performance and Adjusting Your Strategy
Purchasing whole life insurance isn't a "set and forget" decision. Annual reviews ensure your policy performs as expected and continues serving your evolving financial objectives.
Annual Policy Review Checklist
| Review Item | Why It Matters | Action Steps |
|---|---|---|
| Dividend announcement | Shows actual performance vs. illustrated projections | Compare current dividend scale to original illustration; assess long-term sustainability |
| Cash value growth | Confirms accumulation pace meets expectations | Calculate growth percentage; verify it aligns with guaranteed plus dividend projections |
| Premium payment status | Prevents unintended lapse from missed payments | Confirm autopay enrollment; review grace periods and reinstatement provisions |
| Beneficiary designations | Ensures proceeds distribute according to current wishes | Update after marriages, births, divorces, or deaths; name contingent beneficiaries |
| Loan balances | Monitors interest accumulation and death benefit reduction | Review outstanding loan amounts; consider repayment to restore full death benefit |
| Policy rider benefits | Verifies supplemental coverage remains adequate | Assess inflation impact on waiver of premium, accidental death, or other riders |
Market conditions affect dividend scales even at well-managed mutual companies. The U.S. Treasury’s Federal Insurance Office report analyzes how rising interest rates beginning in 2022 improved life insurers' investment returns after years of low yields, potentially supporting higher future dividends. However, guaranteed elements remain unchanged regardless of market fluctuations, emphasizing the importance of conservative planning based on minimums rather than optimistic scenarios.
If your financial situation changes dramatically, several adjustment options exist. You can reduce the death benefit to lower premiums, convert to extended term or reduced paid-up insurance using existing cash value, or surrender the policy for cash value minus any applicable fees. Each choice carries tax and coverage implications that require careful evaluation before implementation.
Tax Advantages and Compliance Considerations
Whole life insurance enjoys favorable tax treatment that enhances its appeal as a wealth-building tool, provided you structure and manage the policy within IRS guidelines.
Key tax benefits:
- Death benefits pass income-tax-free to beneficiaries under IRC Section 101(a)
- Cash value grows tax-deferred with no annual 1099 reporting
- Policy loans avoid immediate taxation when properly structured
- 1035 exchanges allow tax-free transfers between permanent policies
- Dividend payments generally qualify as return of premium (non-taxable)
Tax advantages disappear if a policy becomes a modified endowment contract (MEC) by exceeding premium limits under the 7-pay test. MEC status triggers "last-in-first-out" taxation on loans and withdrawals, meaning gains come out first and incur income tax plus potential 10% penalties before age 59½.
Working with experienced professionals helps structure premium payments and coverage amounts to avoid MEC classification while maximizing tax benefits. Companies test policies at issue and monitor them throughout to ensure compliance, but substantial changes (adding riders, increasing death benefits) can trigger recalculation.
Estate tax inclusion depends on policy ownership. Policies owned by the deceased at death count toward estate value for federal tax purposes. Transferring ownership to an ILIT or another individual three years before death removes proceeds from the taxable estate, though you lose direct control over beneficiary changes and policy management.
Premium payments aren't tax-deductible for personal coverage, distinguishing life insurance from qualified retirement accounts. However, business-owned policies may receive different treatment depending on purpose and structure, requiring coordination with tax advisors familiar with corporate-owned life insurance (COLI) regulations.
Making an Informed Decision About Whole Life Coverage
Selecting permanent insurance requires balancing competing priorities: guaranteed protection versus cost, certainty versus flexibility, forced savings versus investment autonomy. No single answer fits every family's situation, making personalized guidance essential.
Start by clarifying your primary objective. Are you protecting dependents who need income replacement? Planning your estate? Building tax-advantaged savings? Funding a business agreement? Each goal suggests different policy designs, coverage amounts, and premium structures.
Questions to ask before purchasing:
- How much coverage do I need based on debts, income replacement, and final expenses?
- Can I comfortably afford premiums during economic downturns or income disruptions?
- Do I have higher-interest debt to pay off or retirement savings gaps to fill first?
- What happens if I need to stop paying premiums in 5, 10, or 20 years?
- Does the insurance company have strong financial ratings and dividend payment history?
Request illustrations from multiple highly rated carriers and compare guaranteed values rather than optimistic projections. Examine company financial strength through ratings from A.M. Best, Moody's, and Standard & Poor's. Research historical dividend performance, though past results don't guarantee future payments.
Consider combining strategies. A base whole life policy providing guaranteed lifetime coverage paired with term insurance for temporary high-coverage needs often delivers better value than either approach alone. This hybrid strategy ensures permanent protection while maximizing death benefit during critical earning and debt-repayment years.
Avoid pressure tactics or promises that seem unrealistic. Legitimate insurance professionals educate rather than push, helping you understand tradeoffs and make confident decisions aligned with your values and objectives. If someone discourages comparison shopping or claims their product is universally superior, seek a second opinion.
Working with Knowledgeable Insurance Professionals
Navigating whole life insurance complexities benefits from working with advisors who prioritize education and suitability over sales commissions. The right professional explains options clearly, compares alternatives objectively, and helps you make informed choices without pressure.
At Moser Insurance Group Inc, we guide individuals and families throughout the Triad Area in understanding how life insurance fits within comprehensive financial planning. Whether you're exploring whole life for estate planning, business succession, or guaranteed legacy protection, our team provides personalized support to match coverage with your specific goals and budget.
Expect your advisor to review your complete financial picture, including existing coverage, retirement accounts, debts, and family obligations. Comprehensive analysis reveals whether permanent insurance complements your strategy or whether alternative approaches better serve your needs. Transparency about costs, commission structures, and product limitations builds trust and ensures recommendations align with your interests rather than sales quotas.
Policy delivery doesn't end the relationship. Ongoing service includes annual reviews, assistance with beneficiary updates, loan processing, claims support, and strategic adjustments as your life circumstances change. Insurance needs evolve through marriages, births, divorces, business transitions, and retirement, requiring periodic reassessment to maintain appropriate protection levels.
You can reach our team at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com to schedule a consultation. We serve families and businesses in Greensboro, Kernersville, High Point, Winston Salem, and throughout the Triad Area with straightforward guidance on life insurance, Medicare, and health coverage options.
Whole life insurance offers guaranteed lifetime protection and tax-advantaged cash value growth for families who value certainty and long-term financial security. Understanding how premiums, dividends, and policy features work together helps you determine if this permanent coverage aligns with your goals. Moser Insurance Group Inc helps individuals and families in the Triad Area make confident insurance decisions through clear explanations and personalized guidance. Contact us at 336-862-1763 or moserinsurancegroup@gmail.com to discuss how whole life insurance fits within your comprehensive financial plan.
Recent Comments