

Understanding your healthcare coverage becomes increasingly important as you approach retirement age. Many people entering Medicare discover that traditional coverage leaves significant gaps, particularly when it comes to dental and vision care. These routine but essential services can become surprisingly expensive without proper coverage, making it critical to understand how medicare dental and vision plans work and what options are available to you in the Greensboro, Kernersville, High Point, Winston Salem, and Triad Area communities.
What Original Medicare Does Not Cover
Original Medicare (Parts A and B) provides robust coverage for hospital stays, doctor visits, and medically necessary procedures. However, the program has notable limitations when it comes to dental and vision services.
Dental Coverage Gaps in Original Medicare
Medicare Part A and Part B generally do not cover routine dental care. This means cleanings, fillings, tooth extractions, dentures, and most other dental procedures fall outside the scope of traditional coverage. The CMS overview of Medicare dental coverage clarifies that Medicare will only pay for dental services in very specific circumstances.
Medicare may cover dental services only when:
- The dental procedure is an integral part of a covered medical procedure (such as jaw reconstruction after an accident)
- You need a dental examination before a kidney transplant or heart valve replacement
- Dental treatment is necessary due to complications from radiation treatment for oral cancer
These exceptions are rare and don't help with routine dental maintenance that most Medicare beneficiaries need.
Vision Coverage Limitations
Similarly, Original Medicare provides minimal vision coverage. Part B covers certain diagnostic tests and treatments for eye diseases such as glaucoma, macular degeneration, and diabetic retinopathy. However, routine eye exams, eyeglasses, and contact lenses are not covered except in specific post-surgical situations.
| Service Type | Original Medicare Coverage | Typical Out-of-Pocket Cost |
|---|---|---|
| Routine eye exam | Not covered | $50-150 per visit |
| Eyeglasses | Only after cataract surgery | $100-500+ per pair |
| Contact lenses | Only after cataract surgery | $200-700+ annually |
| Routine dental cleaning | Not covered | $75-200 per cleaning |
| Fillings | Not covered | $150-450 per filling |
| Dentures | Not covered | $1,000-3,000+ per set |
Medicare Advantage Plans Fill the Coverage Gap
Medicare Advantage (Part C) plans offer an alternative way to receive Medicare benefits through private insurance companies approved by Medicare. One of the most significant advantages of these plans is the inclusion of supplemental benefits that Original Medicare doesn't cover.
How Medicare Advantage Handles Dental Benefits
Most Medicare Advantage plans include some level of dental coverage as an added benefit. According to KFF’s analysis of Medicare Advantage enrollment, the vast majority of MA plans now offer dental benefits, though the scope and generosity vary considerably.
Typical dental benefits in Medicare Advantage plans include:
- Preventive services (cleanings, X-rays, exams)
- Basic services (fillings, extractions, root canals)
- Major services (crowns, bridges, dentures)
Coverage levels differ substantially between plans. Some plans offer comprehensive dental with low copays, while others provide only preventive care or impose annual dollar limits on benefits.
Vision Benefits in Medicare Advantage
Medicare Advantage plans typically include vision benefits that go beyond Original Medicare's limited coverage. These benefits commonly include routine eye exams and allowances toward eyeglasses or contact lenses.
Standard vision benefits often feature:
- Annual routine eye exams with minimal or no copay
- Allowances of $100-300 toward eyewear every one or two years
- Access to preferred provider networks with discounted pricing
- Coverage for contact lens fittings in some plans
Understanding Standalone Dental and Vision Plans
If you prefer to keep Original Medicare and add Medicare Supplement Plans for other gaps, you can purchase standalone dental and vision insurance policies. These plans operate independently from Medicare and provide dedicated coverage for dental and vision needs.
Standalone Dental Insurance Options
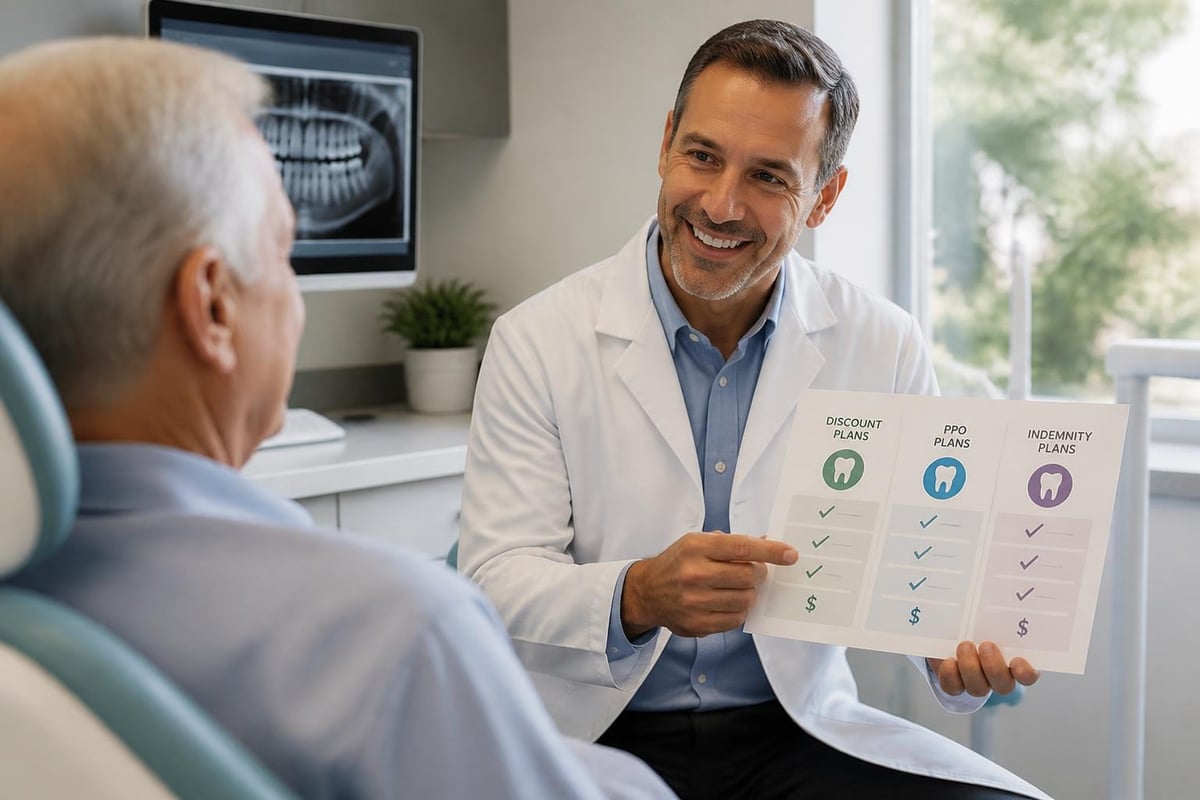
Private dental insurance plans designed for seniors typically fall into three categories:
- Discount dental plans: Not insurance, but membership programs offering reduced rates at participating dentists (typically 10-60% savings)
- Indemnity plans: Traditional insurance that lets you visit any dentist and reimburses a percentage of costs
- Preferred Provider Organization (PPO) plans: Network-based plans offering better coverage when you use in-network providers
| Plan Type | Monthly Premium Range | Annual Maximum | Best For |
|---|---|---|---|
| Discount Plans | $8-20 | No maximum (just discounts) | Healthy teeth needing basic care |
| PPO Plans | $20-60 | $1,000-2,000 | Regular maintenance and minor issues |
| Indemnity Plans | $30-80 | $1,500-3,000+ | Those wanting provider flexibility |
Most standalone dental plans include waiting periods for major services, meaning you cannot immediately claim coverage for expensive procedures. Preventive care typically has no waiting period, but basic services may require 3-6 months of enrollment, and major services may require 12-24 months.
Standalone Vision Insurance Considerations
Vision insurance plans for Medicare beneficiaries typically cost $10-30 monthly and provide annual eye exams plus allowances for frames, lenses, or contacts. These plans work best for people who need new prescription eyewear regularly.
Evaluating Your Personal Dental and Vision Needs
Choosing the right medicare dental and vision plans requires honest assessment of your current oral and eye health, anticipated needs, and budget considerations. Not everyone needs the same level of coverage.
Dental Health Assessment Factors
Consider your dental history and current status:
- Frequency of cavities or gum disease in recent years
- Existing dental work that may need replacement or repair
- Whether you have dentures or anticipate needing them
- Your commitment to preventive care and regular cleanings
People with good dental health who maintain regular preventive care may find that a basic plan or even a discount program meets their needs adequately. Those facing significant dental work should calculate whether comprehensive Medicare Advantage dental benefits or robust standalone coverage provides better value.
Vision Care Evaluation
Your vision insurance needs depend on several factors that change throughout your Medicare years.
Key considerations include:
- Whether you wear corrective lenses and how often your prescription changes
- History of eye conditions like glaucoma, cataracts, or macular degeneration
- Family history of eye disease
- Whether you prefer glasses, contacts, or both
People with stable prescriptions who only need new glasses every few years might skip vision insurance and pay out of pocket. However, those with changing prescriptions or who prefer contact lenses often benefit from the predictable costs of vision coverage.
Comparing Medicare Advantage Versus Original Medicare Plus Supplements
One of the most important decisions Medicare beneficiaries face is choosing between Medicare Advantage plans with built-in dental and vision benefits or staying with Original Medicare and adding separate coverage for these services.
Financial Comparison Strategy
The Medicare & You 2025 handbook provides official guidance on comparing these options, but the math depends heavily on individual circumstances.
Calculate total annual costs including:
- Monthly premiums (Medicare Advantage, Medigap, Part D, dental, vision)
- Expected out-of-pocket costs based on your typical usage
- Maximum out-of-pocket limits
- Provider network restrictions and your preferred doctors
Many people in the Triad Area find that Medicare Advantage plans offer excellent value when dental and vision benefits are factored in, especially if they use those services regularly. Others prefer the flexibility of Original Medicare with supplements and standalone dental/vision plans.
Provider Network Considerations
Medicare Advantage plans typically require you to use network providers for maximum benefits, though some PPO plans offer out-of-network coverage at higher costs. This restriction extends to dental and vision benefits included in the plan.
Network questions to ask:
- Are my current dentist and eye doctor in the plan's network?
- How many dental and vision providers serve Greensboro, Winston Salem, High Point, and Kernersville?
- What happens if I need care while traveling?
- Can I switch providers easily if dissatisfied?
Those who value provider choice and have established relationships with specialists often prefer Original Medicare's freedom to see any provider who accepts Medicare, then add standalone dental and vision coverage.
Shopping for Medicare Dental and Vision Plans
The annual Medicare enrollment periods provide opportunities to review and change your medicare dental and vision plans. Understanding when and how to shop ensures you don't miss important deadlines.
Annual Enrollment Period Strategy
The Annual Enrollment Period runs from October 15 through December 7 each year, allowing you to switch from Original Medicare to Medicare Advantage (or vice versa) and change your coverage options. This is the primary time to evaluate whether your current dental and vision benefits meet your needs.
Steps for effective plan comparison:
- Document your current year's dental and vision expenses
- List upcoming procedures or needs you anticipate
- Research which plans cover your preferred providers
- Compare total costs including premiums and expected out-of-pocket expenses
- Verify coverage details for specific services you need
Research from the Kaiser Family Foundation on dental, hearing, and vision costs shows significant variation in supplemental benefits across Medicare Advantage plans, making careful comparison essential.
Special Enrollment Situations
Certain circumstances allow you to change your medicare dental and vision plans outside the Annual Enrollment Period. These Special Enrollment Periods may apply when you move to a new service area, lose other coverage, or qualify for Extra Help with costs.
Common Mistakes to Avoid
Many Medicare beneficiaries make preventable errors when selecting dental and vision coverage that can cost them thousands of dollars or leave them without needed care.
Mistake 1: Assuming Medicare Covers Routine Care
The most common misconception is that Medicare functions like employer health insurance that typically includes dental and vision coverage. Original Medicare was designed in 1965 when dental and vision care were considered separate from core medical services, and that structure remains today.
Mistake 2: Ignoring Waiting Periods
Standalone dental insurance plans almost always include waiting periods for major services. People who delay purchasing coverage until they need extensive work often discover they must wait months or even a year before coverage applies to procedures like crowns, bridges, or dentures.
Mistake 3: Choosing Based Only on Premium
The lowest-premium plan rarely provides the best value. Annual maximums, copays, coinsurance percentages, and network restrictions all affect your actual costs. A plan with a $15 monthly premium but a $1,000 annual maximum may cost more overall than a $35 plan with a $2,500 maximum if you need significant dental work.
Mistake 4: Not Verifying Provider Networks
Enrolling in a plan before confirming your preferred dentist or eye doctor participates in the network can force difficult choices between changing providers or paying higher out-of-network costs. Always verify network participation before enrolling, especially in the Greensboro, High Point, Winston Salem, and Kernersville areas where provider networks vary.
Coordinating Dental and Vision Coverage With Overall Medicare Strategy
Your medicare dental and vision plans should integrate seamlessly with your broader Medicare coverage strategy. These supplemental benefits don't exist in isolation-they're part of your complete healthcare approach.
Integrating With Part D Prescription Coverage
Some medications affect dental health, including those that cause dry mouth or bone density loss. When evaluating dental coverage, consider how your prescriptions might increase your dental care needs. Similarly, eye conditions often require prescription medications that your Part D plan covers.
Considering Long-Term Care Planning
As you age, accessing dental and vision care may become more challenging if mobility decreases. Some Medicare Advantage plans offer transportation benefits or in-home services that can help maintain oral and eye health even with physical limitations. While it's a separate consideration, maintaining adequate life insurance coverage through options like Term Life Insurance provides financial protection for your family as you manage healthcare costs in retirement.
Budgeting for Total Healthcare Costs
Create a comprehensive healthcare budget that accounts for all Medicare-related expenses:
- Part B premium (deducted from Social Security)
- Part D premium
- Medicare Supplement or Medicare Advantage premium
- Standalone dental and vision premiums (if applicable)
- Estimated copays, coinsurance, and deductibles
- Services not covered by any plan
The National Institute of Dental and Craniofacial Research guidance on finding dental care emphasizes the importance of budgeting for dental expenses, particularly for Medicare beneficiaries who face coverage gaps.
Local Considerations for Triad Area Residents
Medicare beneficiaries in Greensboro, Winston Salem, High Point, Kernersville, and throughout the Triad Area have access to numerous Medicare Advantage plans and standalone dental and vision options. The competitive market in North Carolina provides choices, but also requires careful comparison.
Regional Provider Networks
Major dental and vision provider networks in the Triad Area include national chains and local independent practices. When comparing medicare dental and vision plans, verify that convenient providers participate in your chosen plan's network.
Questions for local plan comparison:
- How many dentists in Greensboro accept this plan?
- Are there vision providers in Kernersville and High Point?
- Does the plan include the dental practice I currently use?
- What's the average wait time for appointments with network providers?
Community Resources
Local Area Agencies on Aging and the North Carolina Senior Health Insurance Information Program (SHIIP) provide free counseling to help Medicare beneficiaries understand their options. These resources can be particularly valuable when comparing complex dental and vision coverage options.
Making Your Decision
Selecting the right medicare dental and vision plans requires balancing cost, coverage, provider access, and convenience. There's no universal "best" option-the right choice depends on your specific health status, budget, and preferences.
Final checklist before enrolling:
- Calculated total annual costs including all premiums and expected usage
- Verified your dentist and eye doctor participate in the network
- Reviewed coverage details for services you anticipate needing
- Understood waiting periods for major services
- Compared at least three different coverage options
- Confirmed enrollment deadlines and effective dates
- Saved plan documents and contact information
Whether you choose a comprehensive Medicare Advantage plan with built-in benefits or Original Medicare with standalone coverage, having dental and vision protection helps you maintain your quality of life throughout retirement.
For personalized assistance comparing your options, you can contact Moser Insurance Group Inc at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com to discuss your specific situation and get clear answers about medicare dental and vision plans available in your area.
Choosing the right medicare dental and vision plans doesn't have to feel overwhelming when you have expert guidance. Whether you're new to Medicare or reviewing your current coverage, having someone explain your options clearly makes all the difference. Moser Insurance Group Inc helps individuals and families in the Triad Area understand their Medicare choices without pressure, providing personalized support so you can make confident decisions about your healthcare coverage. Contact Moser Insurance Group Inc today to discuss your dental and vision coverage options.
Recent Comments