

When you purchase a home, you're making one of the largest financial commitments of your lifetime. Protecting that investment and ensuring your family can remain in the home even if something happens to you requires careful planning. Life and mortgage insurance work together to create a safety net that covers your mortgage obligations while providing broader financial protection for your loved ones. Understanding how these two types of coverage interact helps you make informed decisions that secure your family's future without overpaying for unnecessary policies.
Understanding the Basics of Life and Mortgage Insurance
Life insurance provides a tax-free death benefit to your chosen beneficiaries when you pass away. This fundamental protection tool replaces lost income, covers final expenses, and helps your family maintain their standard of living. According to LIMRA research, millions of American households lack adequate life insurance protection, leaving families vulnerable to financial hardship.
Mortgage protection insurance, on the other hand, is a specialized type of decreasing term life insurance designed specifically to pay off your home loan if you die before it's fully paid. The coverage amount typically decreases over time as your mortgage balance declines. While this sounds convenient, it's important to understand the differences between dedicated mortgage insurance products and traditional life insurance policies that can accomplish the same goal with greater flexibility.
Key Differences Between Mortgage Insurance and Traditional Life Insurance
The primary distinction lies in how the death benefit is paid and who controls it. Mortgage protection insurance typically pays directly to your lender, covering only the remaining loan balance. Your beneficiaries don't receive any excess funds, and they have no say in how the money is used.
Traditional life insurance, by contrast, pays the death benefit directly to your named beneficiaries. They can use those funds to pay off the mortgage, cover other expenses, or invest for long-term security. This flexibility makes standard life insurance policies more versatile for most families in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem.
Types of Life Insurance That Protect Your Mortgage
Several life insurance options can safeguard your mortgage while providing additional benefits. Each type serves different needs and budgets, making it essential to evaluate your specific situation before choosing coverage.
Term Life Insurance for Mortgage Protection
Term life insurance offers the most affordable way to protect your mortgage. You select a coverage amount equal to or greater than your mortgage balance and choose a term length that matches or exceeds your loan payoff timeline.
Advantages of using term life for mortgage protection:
- Significantly lower premiums than permanent policies
- Flexible coverage amounts that you control
- Beneficiaries receive full death benefit to use as needed
- Can cover multiple financial obligations beyond the mortgage
- Easy to adjust coverage as your needs change
A 30-year term policy purchased when you take out a 30-year mortgage ensures protection throughout the entire loan period. If you refinance or pay off the mortgage early, the coverage remains in place for other financial needs.
Permanent Life Insurance Options
Whole life insurance builds cash value while providing lifelong coverage. Although premiums are higher than term policies, the cash value component grows tax-deferred and can be accessed through policy loans or withdrawals.
For homeowners focused on both mortgage protection and long-term wealth building, permanent insurance offers unique advantages. The cash value can serve as an emergency fund, supplement retirement income, or provide collateral for loans. Meanwhile, the death benefit ensures your family can pay off the mortgage regardless of when you pass away.
| Policy Type | Premium Cost | Coverage Duration | Cash Value | Best For |
|---|---|---|---|---|
| Term Life | Lowest | 10-30 years | None | Temporary protection, budget-conscious families |
| Whole Life | Highest | Lifetime | Yes, guaranteed growth | Long-term planning, wealth building |
| Universal Life | Moderate | Lifetime (if funded properly) | Yes, variable growth | Flexible premium needs |
| Mortgage Insurance | Moderate | Matches loan term | None | Single-purpose mortgage coverage only |
Calculating the Right Coverage Amount
Determining how much life and mortgage insurance you need requires analyzing your total financial obligations, not just your mortgage balance. A comprehensive approach considers multiple factors that affect your family's financial security.
The Total Debt Method
Start by calculating all outstanding debts: mortgage principal, home equity loans, car loans, credit cards, and student loans. Add funeral and final expenses, which average $7,000 to $12,000 in 2026. This baseline ensures your family won't inherit debt alongside their grief.
Next, consider income replacement. Multiply your annual income by the number of years your family would need support. Many financial advisors recommend 10 to 15 times your annual income, though individual circumstances vary significantly.
Additional factors to include:
- College education costs for children
- Outstanding medical bills or healthcare needs
- Business debts if you're self-employed
- Co-signed loans or obligations
- Future care needs for dependents with disabilities
The DIME Formula for Comprehensive Coverage
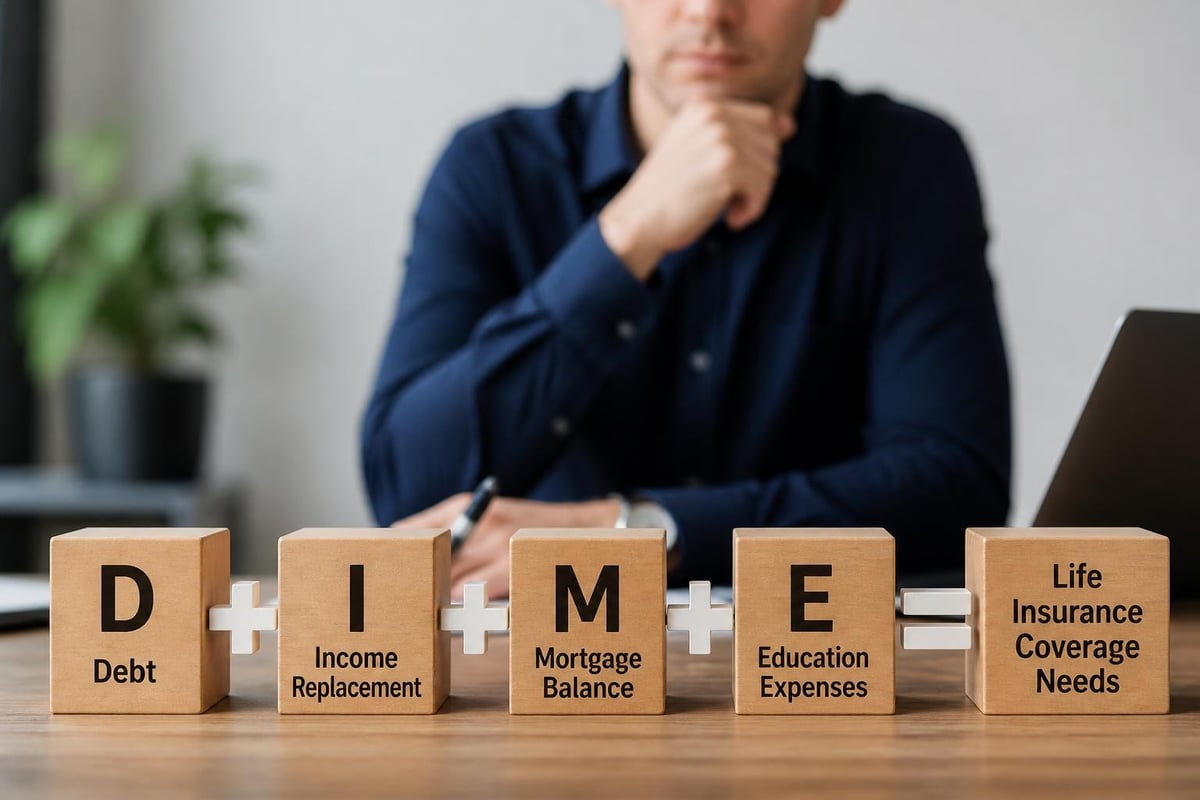
The DIME method (Debt, Income, Mortgage, Education) provides a structured approach to calculating life insurance needs:
- Debt: Total of all debts except mortgage
- Income: Annual income multiplied by years of replacement needed
- Mortgage: Remaining balance on home loan
- Education: Estimated college costs for all children
For example, a family with $25,000 in debt, $60,000 annual income needing 10 years replacement, a $250,000 mortgage, and $100,000 in education costs would need $1,025,000 in coverage. This comprehensive calculation ensures adequate protection across all financial responsibilities.
Special Considerations for Different Types of Borrowers
Your mortgage type and personal situation influence which life and mortgage insurance strategy works best. Different borrower profiles require tailored approaches to protection.
First-Time Homebuyers
Young families purchasing their first home often have the highest debt-to-income ratios and the longest mortgage terms. Consumer Reports recommends prioritizing affordable term life insurance that provides substantial coverage during these high-risk years.
A 30-year term policy purchased at age 30 typically costs far less per month than the same coverage purchased at age 45. Locking in low rates early provides decades of affordable protection. For residents in Greensboro, Winston Salem, and surrounding communities, getting quotes early in your homebuying journey maximizes savings.
Self-Employed Borrowers and Business Owners
If you're self-employed, your life insurance needs extend beyond personal mortgage protection. Your business may have debts, partner agreements, or key person insurance requirements. Coordinating personal and business coverage ensures all obligations are met.
Consider whether your business income would continue if you passed away. If your family depends on business value or ongoing operations, additional coverage beyond the mortgage becomes critical. Understanding how different policy types support both personal and business needs helps create comprehensive protection.
Co-Borrowers and Joint Mortgages
When two people share mortgage responsibility, each should carry adequate life insurance. Some couples purchase separate policies on each person, while others use a joint policy covering both lives.
Comparing individual versus joint coverage:
| Approach | Pros | Cons |
|---|---|---|
| Individual policies on each person | Each policy pays full benefit; coverage continues if one spouse dies; can customize amounts | Higher total premiums |
| Joint first-to-die policy | Lower premiums than two separate policies; simple administration | Pays only once; survivor left without coverage |
| Joint survivorship policy | Pays after both deaths; useful for estate planning | No benefit to surviving spouse; not suitable for mortgage protection |
For most families, individual policies on each wage earner provide the best balance of protection and flexibility. This approach ensures the surviving spouse receives a death benefit to pay off the mortgage while maintaining their own coverage.
Tax Implications and Financial Planning
Understanding the tax treatment of life and mortgage insurance helps maximize the value of your coverage. The IRS provides clear guidance on how life insurance proceeds and policy transactions are taxed.
Tax-Free Death Benefits
Life insurance death benefits paid to beneficiaries are generally income-tax-free. This applies whether your family uses the money to pay off the mortgage, cover living expenses, or invest for the future. This tax advantage makes life insurance an efficient wealth transfer tool.
However, if your estate is large enough to trigger federal estate taxes (over $13.99 million per individual in 2026), life insurance proceeds may be included in your taxable estate. Proper estate planning, including irrevocable life insurance trusts, can address this issue for high-net-worth families.
Cash Value Growth and Access
Permanent life insurance policies build cash value that grows tax-deferred. You won't pay taxes on growth while it remains inside the policy. When you access cash value through policy loans, the borrowed amount is also not taxable as long as the policy remains in force.
Withdrawals up to your total premium payments (cost basis) are tax-free. Amounts exceeding your basis are taxable as ordinary income. Understanding these rules helps you strategically access policy value without triggering unnecessary taxes.
Common Mistakes to Avoid When Buying Coverage
Many homeowners make preventable errors when purchasing life and mortgage insurance. Awareness of these pitfalls helps you make smarter decisions and avoid costly mistakes.
Buying Only Mortgage Protection Insurance
Dedicated mortgage protection insurance typically costs more per dollar of coverage than comparable term life insurance. Additionally, the decreasing benefit structure means you're paying consistent premiums for continuously declining coverage.
Experian’s comparison analysis shows that traditional term life insurance usually provides better value. You get level coverage for level premiums, giving you more protection for your money. Your beneficiaries maintain control over how the death benefit is used, rather than having it automatically paid to the lender.
Underestimating Coverage Needs
Many families purchase only enough coverage to pay off the mortgage, neglecting other financial obligations. This leaves survivors struggling with daily expenses, debt payments, and long-term goals even after the house is paid off.
A comprehensive approach considers all income replacement needs, not just the mortgage. Your family will still need money for utilities, food, transportation, healthcare, and education whether or not the mortgage is paid. Adequate coverage addresses total financial needs, not just housing costs.
Failing to Review Coverage Regularly
Life circumstances change, but many homeowners never adjust their coverage. Refinancing to a larger mortgage, adding children to the family, or taking on new debts all increase your insurance needs.
Events that should trigger a coverage review:
- Refinancing or purchasing a new home
- Birth or adoption of children
- Marriage or divorce
- Significant income increase or decrease
- Starting a business
- Children graduating from college
- Retirement planning milestones
Schedule an annual review with a qualified insurance professional to ensure your coverage keeps pace with your evolving needs. For families in High Point, Kernersville, and the broader Triad Area, working with a local advisor who understands regional costs and needs provides personalized guidance.
Shopping for Life and Mortgage Insurance
The buying process for life insurance has become more transparent and consumer-friendly in recent years. NAIC consumer resources provide independent guidance on shopping strategies, policy comparison, and regulatory protections.
Working with an Independent Agent
Independent insurance agents represent multiple insurance companies, allowing them to compare policies and find the best fit for your specific needs. This contrasts with captive agents who sell only one company's products.
An independent agent can explain the nuances between carriers, highlight financial strength ratings, and customize coverage to your budget. They also provide ongoing service, helping with beneficiary changes, coverage reviews, and claims assistance when needed.
At Moser Insurance Group Inc, we help individuals and families understand their options with clear guidance and personalized support. We focus on educating clients so they can make confident insurance decisions without pressure. You can reach us at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your specific situation.
Understanding Policy Illustrations and Quotes
When reviewing life insurance proposals, focus on guaranteed values rather than illustrated projections. Non-guaranteed elements like dividends, cash value growth rates, and future premiums can change based on company performance and market conditions.
Key elements to compare across proposals:
- Guaranteed death benefit amount and duration
- Guaranteed premium amount and payment period
- Insurance company financial strength ratings (A.M. Best, Moody's, S&P)
- Policy fees and surrender charges
- Conversion options (for term policies)
- Riders and additional benefits included
Request proposals from multiple highly-rated carriers. Price differences can be substantial for identical coverage, especially as you age or if you have health conditions. Shopping multiple options ensures competitive pricing without sacrificing quality coverage.
Medical Underwriting and Health Considerations
Most life insurance policies require medical underwriting, which assesses your health status to determine premiums and eligibility. The process typically includes a health questionnaire, prescription drug check, and sometimes a medical exam with blood and urine tests.
Factors that influence your rates include age, tobacco use, height and weight, blood pressure, cholesterol levels, family medical history, and existing health conditions. Being honest on your application is critical as misrepresentations can void coverage when your family needs it most.
Some insurers offer accelerated or simplified underwriting for healthy applicants, reducing approval time from weeks to days or even minutes. These programs use data analytics and third-party health records to assess risk without traditional medical exams.
Protecting Against Fraud and Scams
As with any financial product, life insurance attracts fraudulent schemes targeting uninformed consumers. The FTC warns consumers about common scams involving life insurance policies and supposed unclaimed benefits.
Red Flags to Watch For
Be wary of unsolicited contacts claiming you're the beneficiary of an unknown policy or that you need to purchase mortgage insurance as a loan condition. Legitimate lenders may require that you have life insurance, but they cannot require you to purchase it from a specific company or through a specific agent.
High-pressure sales tactics, requests for upfront fees before providing coverage, and promises of unusually high returns on policy cash values should all raise concerns. Verify agent licenses through your state insurance department and check company ratings through independent rating agencies.
Verifying Policy Information
Keep all policy documents in a secure location and inform your beneficiaries where to find them. Document your coverage details, including company name, policy number, death benefit amount, and agent contact information.
Consider creating a centralized record of all financial accounts and insurance policies that your executor or family members can access if needed. This simple step prevents legitimate claims from going unfiled due to lack of awareness.
Integration with Overall Financial Planning
Life and mortgage insurance shouldn't exist in isolation from your broader financial strategy. Effective planning coordinates all protection and wealth-building tools to work together efficiently.
Coordinating with Employer Benefits
Many employers provide group life insurance as an employee benefit, typically offering one to two times your annual salary in coverage. While valuable, employer coverage usually isn't sufficient for complete family protection, especially if you have a substantial mortgage.
Group coverage is also portable only if you leave employment, and conversion options are often expensive. Treat employer life insurance as a supplement to, not a replacement for, personal coverage that you control regardless of job changes.
Estate Planning Considerations
Life insurance plays a crucial role in estate planning beyond simple mortgage protection. The death benefit provides liquidity to pay estate taxes, equalize inheritances among heirs, or fund charitable bequests.
For families with substantial estates, coordination between life insurance, wills, trusts, and beneficiary designations ensures your wishes are carried out efficiently. Review beneficiary designations regularly as they supersede will provisions for insurance policies and retirement accounts.
Retirement Planning Integration
Permanent life insurance can complement retirement savings strategies. The cash value grows tax-deferred and can be accessed in retirement through loans or withdrawals, providing supplemental income without increasing taxable income in the same way as traditional IRA or 401(k) distributions.
Some retirees use permanent life insurance to create a pension-like income stream while preserving the death benefit for heirs. Others leverage cash value to bridge the gap between early retirement and Social Security eligibility, preserving retirement accounts for later years.
Making the Decision: Next Steps for Homeowners
Securing appropriate life and mortgage insurance requires thoughtful analysis of your unique circumstances. No single solution fits every family, making personalized guidance essential for optimal outcomes.
Gathering Necessary Information
Before meeting with an insurance advisor, compile key financial information: current mortgage balance and terms, other outstanding debts, annual household income, current life insurance coverage (including employer benefits), anticipated future expenses like college costs, and your family's monthly budget.
This information enables accurate needs analysis and ensures proposed coverage addresses all relevant factors. It also streamlines the application process once you decide to move forward with coverage.
Questions to Ask Your Insurance Advisor
A qualified advisor should welcome detailed questions about policy options, pricing, and suitability. Ask about the specific insurance companies they recommend and why, how they're compensated for the products they sell, what happens if you can no longer afford premiums, and how policy performance is monitored over time.
Also inquire about policy riders or additional benefits that might be valuable for your situation, such as waiver of premium, accelerated death benefits for terminal illness, or guaranteed insurability options. Understanding all available features helps you customize coverage to your needs.
Implementing Your Protection Strategy
Once you've selected appropriate coverage, complete the application process promptly while your health status and insurability remain favorable. Delays can result in health changes that increase premiums or reduce eligibility.
Review your coverage annually and after major life events. As your mortgage balance decreases and your financial situation evolves, your insurance needs will change. Proactive management ensures you maintain optimal protection without overpaying for coverage you no longer need.
For personalized guidance on protecting your home and family in 2026, visit moserinsurancegroup.com to explore your options and connect with experienced professionals who understand the unique needs of families throughout the Triad Area.
Life and mortgage insurance provide essential protection that secures your family's home and financial future when coordinated properly. Understanding the differences between mortgage-specific products and traditional life insurance helps you choose coverage that offers maximum flexibility and value. At Moser Insurance Group Inc, we provide clear explanations and personalized support to help you make confident decisions about protecting what matters most. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your specific needs and explore your options without pressure.
Recent Comments