

Finding the right health insurance coverage requires understanding how to effectively quote health insurance options available to you. Whether you're approaching Medicare eligibility, self-employed, or simply shopping for better coverage, the process of comparing health insurance quotes can feel overwhelming without the proper guidance. In the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, residents have numerous insurance options to consider, making it essential to approach the quoting process with knowledge and confidence.
Understanding What Makes Up a Health Insurance Quote
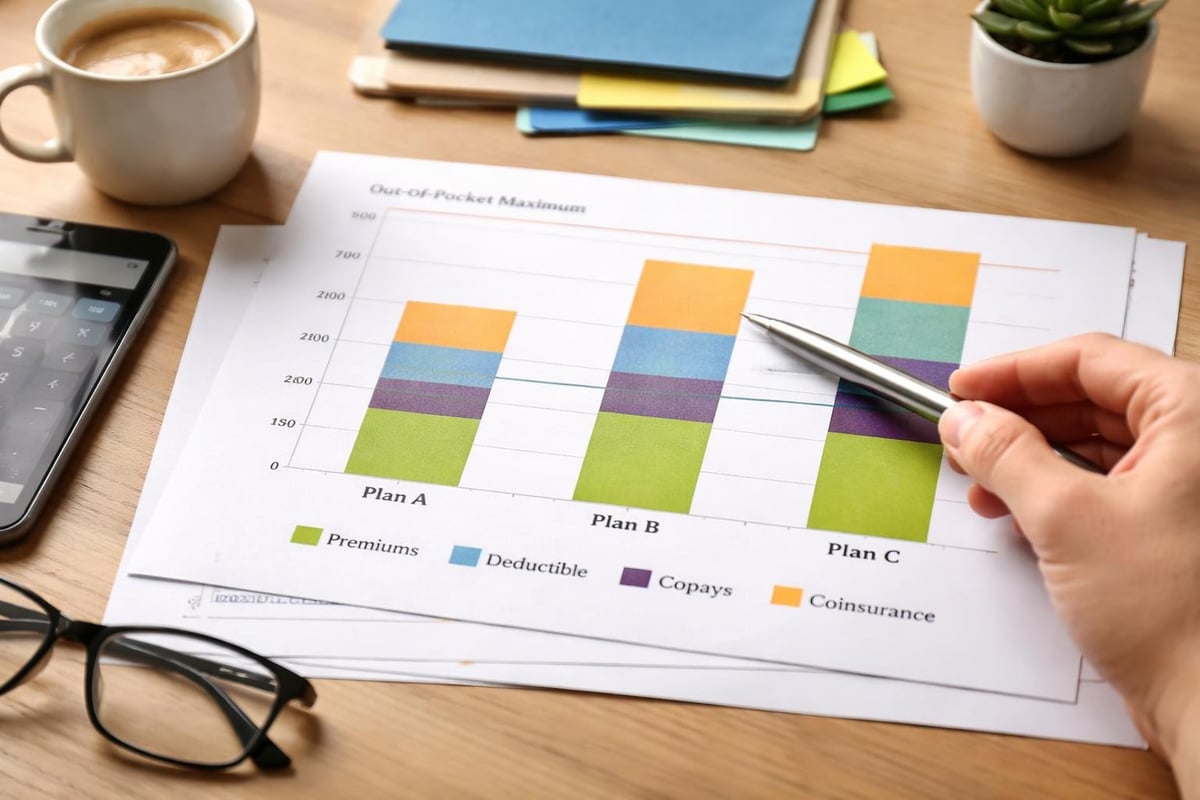
When you quote health insurance, you're not just looking at a single number. A comprehensive quote includes multiple financial components that work together to determine your total healthcare costs throughout the year. The premium represents your monthly payment to maintain coverage, regardless of whether you use medical services.
Deductibles determine how much you'll pay out-of-pocket before your insurance begins covering expenses. A plan with a lower monthly premium often comes with a higher deductible, while plans with higher premiums typically feature lower deductibles. This inverse relationship creates the foundation for choosing a plan that matches your healthcare usage patterns and financial situation.
Key Elements in Every Health Insurance Quote
- Monthly premium amount
- Annual deductible
- Out-of-pocket maximum
- Copayment amounts for office visits
- Coinsurance percentages
- Prescription drug coverage tiers
- Provider network restrictions
Beyond these basics, understanding the components of a health insurance quote helps you make meaningful comparisons. The out-of-pocket maximum serves as your financial safety net, capping the total amount you'll pay in a calendar year for covered services. Once you reach this threshold, your insurance covers 100% of additional covered expenses.
How to Gather Accurate Information Before Requesting Quotes
Preparation significantly improves the accuracy and relevance of the health insurance quotes you receive. Start by compiling personal information including your age, ZIP code (such as 27284 for Kernersville or 27103 for Winston Salem), tobacco usage status, and household income if you're exploring marketplace subsidies.
Your medical history and anticipated healthcare needs shape which plans offer the best value. Create a list of current medications, preferred doctors and specialists, and any planned medical procedures for 2026. When you gather health insurance quotes effectively, this information ensures you're comparing plans that actually meet your specific needs.
Information Needed to Quote Health Insurance
- Personal demographics (birthdate, address, household size)
- Income details for subsidy calculations
- Current health conditions and prescription needs
- Preferred healthcare providers and facilities
- Expected medical service usage for the upcoming year
If you're self-employed in the Triad Area, you'll need additional documentation. Self-employed health insurance options often require proof of business ownership and income verification. Tax returns, profit and loss statements, and 1099 forms help insurance providers determine your eligibility for different plan types and potential tax credits.
Comparing Quotes Across Different Plan Types
Health insurance plans fall into distinct categories, each with different cost structures and access rules. Health Maintenance Organizations (HMOs) typically offer lower premiums but require you to choose a primary care physician and obtain referrals for specialist visits. Preferred Provider Organizations (PPOs) provide more flexibility in choosing providers but come with higher premiums.
Exclusive Provider Organizations (EPOs) blend elements of both, offering lower costs than PPOs while eliminating the referral requirements of HMOs. Point of Service (POS) plans combine features from multiple plan types, allowing both in-network and out-of-network care with varying cost-sharing levels.
| Plan Type | Referrals Required | Out-of-Network Coverage | Typical Premium Level | Best For |
|---|---|---|---|---|
| HMO | Yes | Emergency only | Lowest | Predictable local care |
| PPO | No | Yes (higher cost) | Highest | Flexibility and travel |
| EPO | No | Emergency only | Medium | No referral hassle |
| POS | Yes (for specialists) | Yes (higher cost) | Medium-High | Mixed preferences |
When you quote health insurance across these plan types, you'll notice significant premium differences. A 45-year-old in Greensboro might see HMO quotes ranging from $450-$550 monthly, while PPO quotes for similar coverage could reach $650-$800. These differences reflect the flexibility and network access each plan type provides.
Critical Questions to Ask When Reviewing Quotes
The quote itself only tells part of the story. Essential questions when reviewing health insurance quotes help reveal details that might not appear in the initial quote document. Ask whether your current physicians participate in the plan's network, as out-of-network care dramatically increases costs.
Prescription drug coverage varies substantially between plans. Request the plan's formulary to verify your medications appear on covered lists and check which tier they're assigned to. A medication on Tier 4 or 5 costs significantly more than one on Tier 1 or 2, potentially adding hundreds of dollars to your monthly expenses.
Essential Questions for Every Health Insurance Quote
Coverage Details:
- Which hospitals and urgent care facilities participate in this network?
- Does the plan cover my preferred pharmacy locations?
- Are my specialists considered in-network providers?
- What services require prior authorization?
Cost Considerations:
- Do copays count toward my deductible?
- What's the coinsurance rate after meeting my deductible?
- Are there separate deductibles for prescription drugs?
- Does the plan offer any preventive care at no cost?
Understanding these details before selecting a plan prevents unpleasant financial surprises. For individuals approaching Medicare eligibility, exploring Medicare Advantage plans alongside traditional health insurance helps identify when transitioning makes financial sense.
Online Quote Tools vs. Working with Licensed Agents
Digital platforms make it easier than ever to quote health insurance from home. Comparing health insurance quote websites effectively requires verifying the site's credentials and understanding its relationships with insurance carriers. Some websites represent specific carriers, while others aggregate quotes from multiple sources.
Online tools excel at providing quick premium estimates and allowing side-by-side plan comparisons. You can adjust coverage levels, filter by network type, and model different deductible scenarios instantly. However, automated systems may not account for nuances in your specific situation or help you understand policy language.
Advantages of Online Quote Tools:
- Immediate access 24/7
- Easy comparison of multiple carriers
- No pressure from salespeople
- Privacy in the research phase
Benefits of Working with Licensed Agents:
- Personalized guidance based on your health needs
- Help understanding complex policy terms
- Assistance with application processes
- Ongoing support for claims and coverage questions
For Moser Insurance Group Inc clients in High Point and surrounding areas, combining both approaches often yields the best results. Research online to understand available options and pricing ranges, then schedule a consultation to discuss your specific needs. You can reach our team at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your health insurance questions.
Special Considerations for Different Life Stages
Your insurance needs evolve throughout your life, affecting how you should quote health insurance at different stages. Young adults in their twenties who rarely visit doctors might prioritize low monthly premiums with high deductibles, accepting the risk of higher costs if unexpected medical needs arise.
Families with children require different calculations. Pediatric visits, immunizations, and the unpredictability of childhood illnesses make comprehensive coverage with moderate deductibles more valuable. Plans with lower copays for office visits often provide better value than the cheapest premium options.
Life Stage Health Insurance Priorities
| Life Stage | Primary Considerations | Recommended Plan Features |
|---|---|---|
| Young Adults (18-30) | Low premiums, catastrophic protection | High deductible, preventive care coverage |
| Families with Children | Predictable costs, pediatric coverage | Moderate deductible, low copays |
| Middle Age (40-55) | Chronic condition management | Comprehensive coverage, prescription benefits |
| Pre-Medicare (55-64) | Bridge to Medicare, serious illness coverage | Balanced premium/deductible, broad network |
As you approach age 65, the landscape shifts dramatically. Understanding Medicare supplement plans becomes crucial, as does timing the transition from employer or marketplace coverage to Medicare. For Winston Salem residents turning 65, planning this transition six months in advance prevents coverage gaps.
Understanding Subsidy Eligibility and Its Impact on Quotes
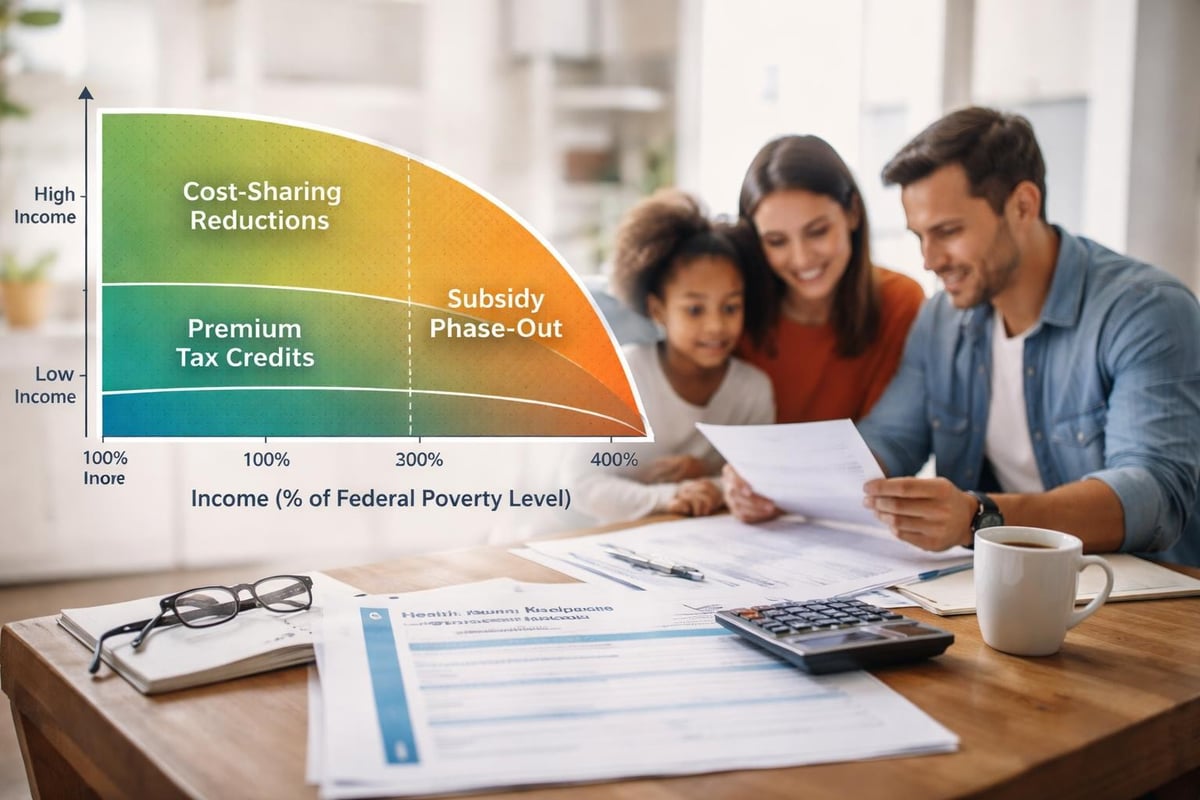
Advance Premium Tax Credits significantly reduce health insurance costs for eligible individuals and families. When you quote health insurance through the Health Insurance Marketplace, the system estimates your subsidy based on projected annual income. These credits apply directly to your monthly premiums, reducing your out-of-pocket costs.
Eligibility depends on your Modified Adjusted Gross Income (MAGI) relative to the Federal Poverty Level. In 2026, a single person earning between approximately $15,060 and $60,240 annually qualifies for subsidies, while a family of four qualifies with household income between roughly $31,200 and $124,800.
Income fluctuations during the year affect subsidy amounts. If you receive a raise, inherit money, or experience other income changes, report these to the Marketplace promptly. Underestimating income results in owing money when filing taxes, while overestimating means paying more monthly than necessary.
Cost-sharing reductions provide additional savings for those earning below 250% of the Federal Poverty Level. These reductions lower your deductibles, copayments, and coinsurance amounts, making the same Silver-tier plan significantly more affordable than the standard version.
Common Mistakes When Getting Health Insurance Quotes
Many people focus exclusively on monthly premiums when they quote health insurance, overlooking the total cost picture. A plan with a $300 monthly premium but a $8,000 deductible could cost significantly more annually than a $450 premium plan with a $2,000 deductible, depending on your healthcare usage.
Failing to verify provider networks represents another critical error. Assuming your longtime physician accepts a particular insurance without verification can force you to either change doctors or pay out-of-network rates. For Greensboro residents, checking whether local facilities like Cone Health or Novant Health participate in specific networks prevents access problems.
Frequent Quote Comparison Errors
- Comparing different plan types (Bronze vs. Gold) without adjusting for coverage differences
- Ignoring out-of-pocket maximums when calculating worst-case scenarios
- Not researching prescription drug coverage for current medications
- Overlooking provider directory accuracy and calling offices directly to verify
- Failing to account for dental and vision needs separately
Timing also matters. Shopping for health insurance outside Open Enrollment periods requires a Qualifying Life Event, such as losing other coverage, marriage, or relocating. Missing enrollment deadlines can leave you uninsured for months, making advance planning essential.
When evaluating personal health insurance plans, calculate total annual costs by adding premiums, expected deductibles based on your health status, and typical copays. This comprehensive approach reveals which plan truly offers the best value for your situation.
How to Quote Health Insurance for Self-Employed Individuals
Self-employment introduces unique challenges and opportunities in the health insurance market. Without access to employer-sponsored group plans, you'll purchase coverage individually through the Health Insurance Marketplace or directly from carriers. The Self-Employed Health Insurance Deduction allows you to deduct premiums from your taxable income, reducing your overall healthcare costs.
Irregular income complicates subsidy calculations. Project your annual income conservatively based on previous years and business trends. The Marketplace reconciles your actual income when you file taxes, adjusting credits accordingly. For Kernersville business owners, working with a tax professional and insurance advisor simultaneously ensures optimal results.
Business structure affects your options. Sole proprietors and single-member LLCs purchase individual coverage. Partnerships and S-corporations might establish group plans even with one employee. C-corporations can offer Health Reimbursement Arrangements (HRAs) or Qualified Small Employer Health Reimbursement Arrangements (QSEHRAs) as alternatives to traditional coverage.
Professional associations and business groups sometimes offer access to group health plans. While these plans market themselves as providing group coverage benefits, scrutinize them carefully. Many are simply individual plans marketed to association members, offering no cost advantages over direct marketplace purchases.
The Role of Insurance Agents in the Quoting Process
Licensed insurance agents provide valuable services at no direct cost to consumers, as carriers pay their commissions. When you quote health insurance with an agent's assistance, you gain access to expert knowledge about carrier reputations, claim payment histories, and local provider network quality.
Agents help navigate the application process, ensuring accuracy and completeness. Mistakes on insurance applications can lead to coverage denials or claim rejections later. An experienced agent reviews your application before submission, catching errors that might cause problems.
For complex situations involving pre-existing conditions, multiple household members with different needs, or coordination with other coverage types, professional guidance proves especially valuable. At moserinsurancegroup.com, we specialize in helping Triad Area families understand their complete insurance picture, including how health insurance coordinates with Medicare plans and life insurance needs.
Ongoing support extends beyond the initial sale. When questions arise about coverage, claims, or plan changes during Open Enrollment, your agent serves as your advocate. This relationship becomes particularly valuable when dealing with claim denials or coverage disputes.
Planning for Future Healthcare Needs
Effective health insurance selection requires thinking beyond immediate needs. A healthy 35-year-old might develop chronic conditions requiring regular specialist care. A family planning to expand should consider maternity coverage levels and pediatric benefits.
Medical cost inflation averages 5-8% annually, outpacing general inflation. Plans that seem expensive today might represent competitive pricing in future years. When evaluating multi-year affordability, project premium increases and assess whether the plan remains sustainable if costs rise 15-20% over three years.
Life changes trigger Special Enrollment Periods, allowing mid-year plan changes. Marriage, divorce, childbirth, adoption, losing other coverage, and moving to a new area all qualify. Understanding these triggers helps you time coverage changes strategically rather than waiting for annual Open Enrollment.
For individuals in their late 50s and early 60s, strategic health insurance selection involves planning the bridge to Medicare. Higher premium plans with comprehensive coverage might prove worthwhile if you anticipate significant medical needs before turning 65. Conversely, if you're healthy and approaching Medicare eligibility, emphasizing lower premiums over comprehensive coverage can reduce costs during this transition period.
Navigating health insurance quotes effectively requires understanding the full picture of coverage, costs, and personal healthcare needs. By asking the right questions, comparing plans thoroughly, and considering both current and future medical requirements, you position yourself to make informed insurance decisions. Whether you're self-employed in the Triad Area, approaching Medicare eligibility, or simply seeking better coverage for your family in Greensboro, Kernersville, High Point, or Winston Salem, Moser Insurance Group Inc provides the personalized guidance you need to understand your options clearly. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your health insurance questions without pressure or confusion.
Recent Comments