

Understanding your healthcare coverage options becomes increasingly important as you approach retirement. Medical supplement plans, also known as Medigap policies, provide essential coverage that works alongside Original Medicare to help manage out-of-pocket healthcare costs. For residents in Greensboro, Winston Salem, High Point, Kernersville, and throughout the Triad Area, navigating these options requires clear information about what these plans cover, how they differ, and when to enroll. At Moser Insurance Group Inc, we help individuals and families make informed decisions about their healthcare coverage without pressure or confusion. Reach us at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your specific needs.
What Medical Supplement Plans Cover
Medical supplement plans are standardized insurance policies sold by private insurance companies to help pay some of the healthcare costs that Original Medicare doesn't cover. These gaps include copayments, coinsurance, and deductibles that can add up significantly throughout the year.
The standardization of Medicare Supplement Insurance plans ensures that each plan type offers the same basic benefits regardless of which insurance company sells it. For example, a Plan G from one company provides identical coverage to Plan G from another company, though premiums may vary.
Core Benefits and Coverage Areas
Most medical supplement plans cover several key areas that Original Medicare leaves as your responsibility:
- Part A coinsurance and hospital costs up to an additional 365 days after Medicare benefits are exhausted
- Part B coinsurance or copayment for medical services and outpatient care
- Blood transfusions for the first three pints each year
- Part A hospice care coinsurance or copayment
Some plans also include coverage for Medicare Part A deductibles, Part B deductibles, Part B excess charges, and even emergency care when traveling outside the United States. These additional benefits vary depending on which plan letter you choose.
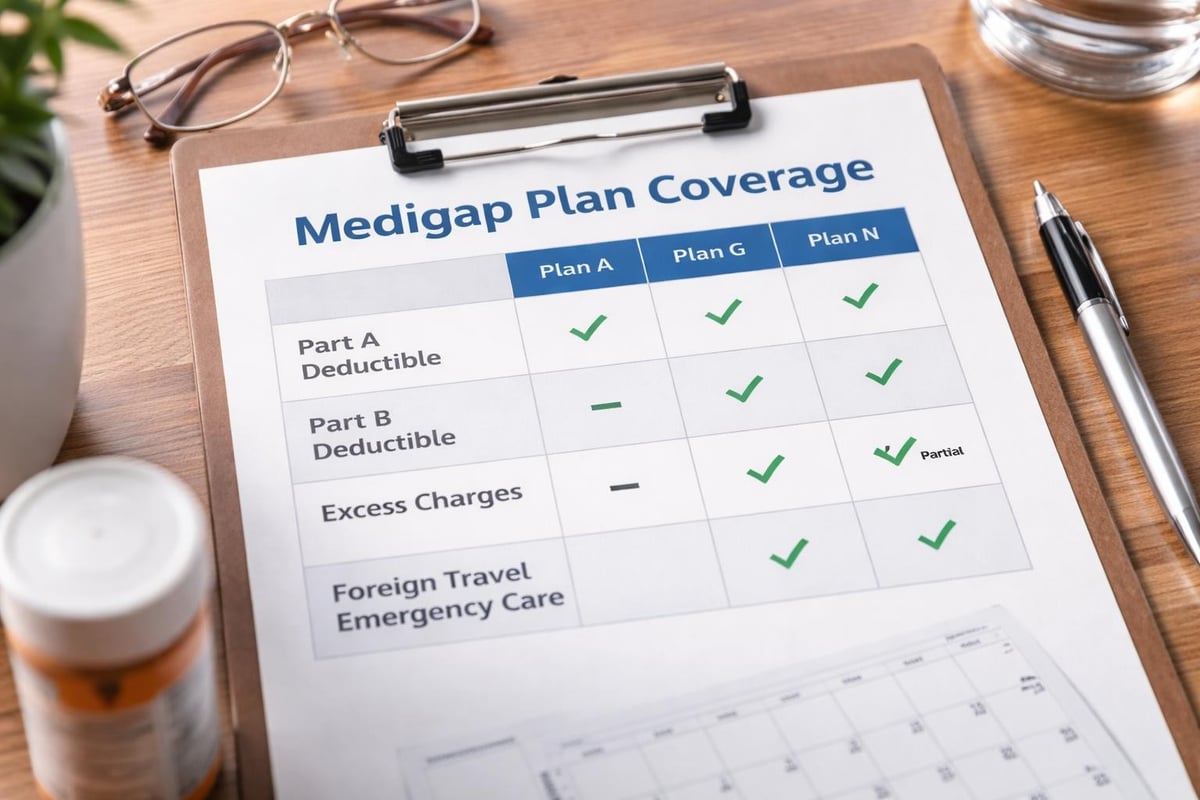
The comprehensive nature of certain plans means you can visit any doctor or hospital that accepts Medicare patients. This nationwide acceptance provides flexibility if you travel frequently or spend winters in warmer climates like many residents from the Triad Area do.
Understanding Plan Types and Standardization
The Centers for Medicare & Medicaid Services works with state insurance departments to regulate how medical supplement plans are structured and sold. According to federal creditable coverage guidelines, these plans must meet specific standards to protect consumers.
| Plan Type | Part A Deductible | Part B Deductible | Part B Excess Charges | Foreign Travel Emergency |
|---|---|---|---|---|
| Plan A | No | No | No | No |
| Plan G | Yes | No | Yes | Yes |
| Plan N | Yes | No | No | Yes |
| Plan F* | Yes | Yes | Yes | Yes |
*Plan F is only available to those who became eligible for Medicare before January 1, 2020.
Popular Plan Choices in 2026
Plan G has become the most popular choice for new Medicare beneficiaries since Plan F was discontinued for those newly eligible. It covers everything except the Part B deductible, which stands at $257 in 2026. This minimal out-of-pocket expense makes Plan G an excellent value for comprehensive coverage.
Plan N offers a budget-friendly alternative with slightly higher cost-sharing. You pay up to $20 copays for doctor visits and up to $50 copays for emergency room visits that don't result in admission. However, you save significantly on monthly premiums compared to Plan G.
Many residents in Winston Salem, High Point, and Kernersville find that understanding Medicare plan differences helps them choose the right coverage level for their health needs and budget.
Enrollment Periods and Timing
The best time to purchase medical supplement plans is during your Medigap Open Enrollment Period. This six-month window begins the first day of the month you're both 65 or older and enrolled in Medicare Part B. During this period, insurance companies cannot deny you coverage or charge higher premiums based on health conditions.
Why Timing Matters
Guaranteed issue rights during this initial enrollment period provide crucial protections. As NerdWallet’s Medicare supplement comparison explains, missing this window can result in medical underwriting, higher premiums, or even coverage denial.
If you're turning 65 and live in Greensboro or anywhere in the Triad Area, planning ahead ensures you don't miss this critical enrollment opportunity. The team at Moser Insurance Group Inc can guide you through the enrollment process for those turning 65 to ensure you make informed decisions.
After your initial enrollment period ends, you can still apply for medical supplement plans, but insurance companies in most states can use medical underwriting to determine eligibility and pricing. This means your health history becomes a factor in approval and cost.
Special Enrollment Situations
Certain life events trigger guaranteed issue rights outside your initial enrollment period:
- Your Medicare Advantage plan leaves your area or stops providing coverage
- You move out of your plan's service area
- Your employer or union coverage ends
- You lose coverage through no fault of your own
Understanding these special circumstances helps you know when you can switch plans without medical underwriting concerns.
Cost Factors and Premium Considerations
Medical supplement plans require monthly premiums in addition to your Medicare Part B premium. These costs vary based on several factors including where you live, which insurance company you choose, and how the company prices its policies.
Premium Rating Methods
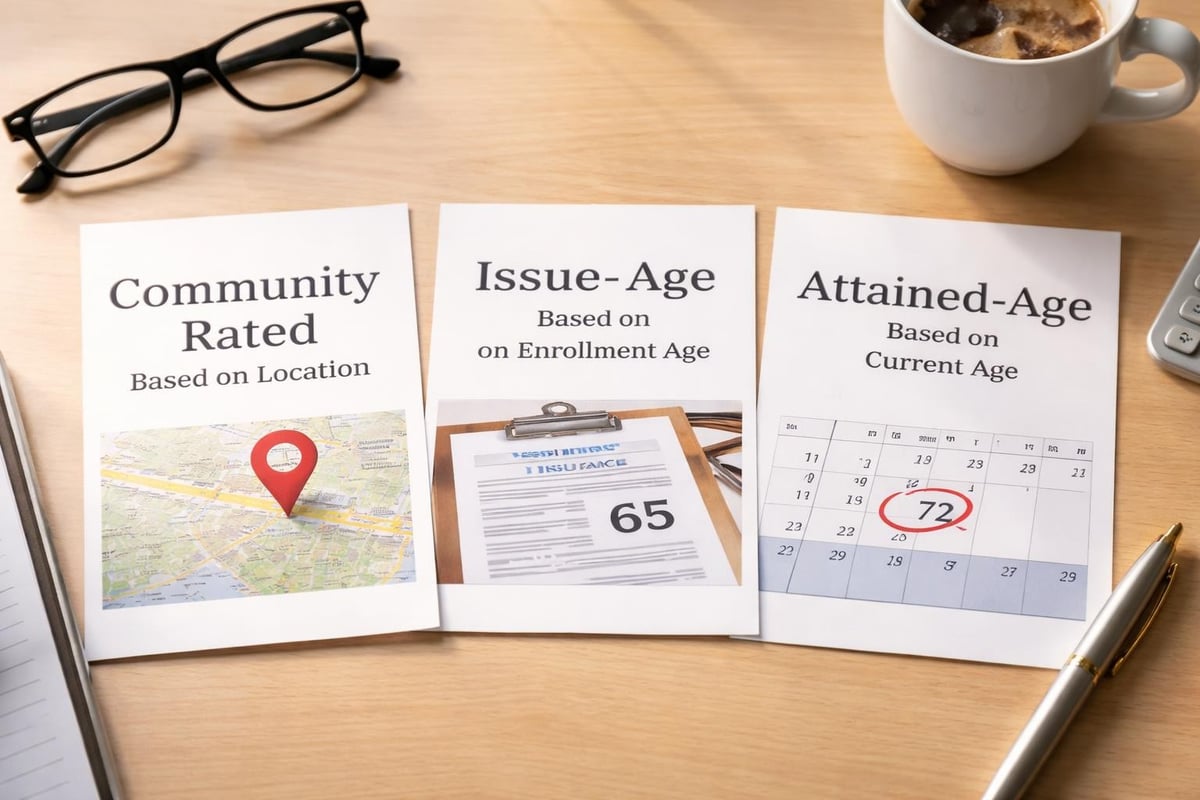
Insurance companies use three primary methods to set premiums:
Community-rated policies charge the same premium to everyone in a geographic area regardless of age. These premiums typically increase only due to inflation and other factors affecting all policyholders.
Issue-age-rated policies base your premium on your age when you first buy the policy. Your rate doesn't increase as you get older, though it may increase for other reasons like inflation.
Attained-age-rated policies start with lower premiums but increase as you age. While initially affordable, these plans can become significantly more expensive as you grow older.
For residents throughout the Triad Area seeking Medicare supplements in North Carolina, understanding these pricing structures helps predict long-term costs.
Comparing Plans and Insurance Companies
Not all insurance companies charge the same premium for identical coverage. Shopping around during your enrollment period can save hundreds or even thousands of dollars annually.
What to Compare Beyond Price
- Financial stability ratings from agencies like A.M. Best or Standard & Poor's
- Customer service reputation and complaint ratios
- Claims processing efficiency and payment track record
- Premium increase history over the past five to ten years
While a lower premium seems attractive, consider the company's history of rate increases. Some insurers offer low initial rates but implement steep increases later. Others maintain more stable, predictable pricing over time.
The regulatory framework for Medicare Supplement Plans ensures consumer protections, but choosing a reputable company still matters for your long-term satisfaction.
Medical Supplement Plans vs Medicare Advantage
Many people wonder whether medical supplement plans or Medicare Advantage plans better suit their needs. These two paths offer fundamentally different approaches to Medicare coverage.
| Feature | Medical Supplement Plans | Medicare Advantage |
|---|---|---|
| Network restrictions | None – any Medicare provider | Usually HMO or PPO networks |
| Out-of-pocket maximum | Varies by plan | Required annual cap |
| Prescription drug coverage | Separate Part D needed | Often included |
| Monthly costs | Part B + supplement premium | Often $0 or low premium |
| Travel flexibility | Nationwide coverage | May limit out-of-area care |
Medical supplement plans work alongside Original Medicare, meaning you can see any doctor or specialist who accepts Medicare patients. This flexibility particularly benefits those who travel, spend time in multiple states, or want freedom to choose providers without network restrictions.
For comparison, Medicare Advantage plans in North Carolina typically use networks and may require referrals for specialist care. However, they often include prescription drug coverage and additional benefits like dental, vision, and hearing.
Prescription Drug Coverage Considerations
Medical supplement plans don't include prescription drug coverage. If you choose a Medigap policy, you'll need to enroll in a separate Medicare Part D prescription drug plan to avoid penalties and ensure medication coverage.
Coordinating Multiple Policies
Managing three separate policies might seem complicated:
- Medicare Part A and Part B provide your base coverage
- Medical supplement plan fills the gaps in Original Medicare
- Part D plan covers prescription medications
This structure actually provides significant advantages. You can choose the Part D plan that best covers your specific medications while maintaining comprehensive medical coverage through your supplement plan. The separation allows you to optimize each component of your coverage.
When reviewing your coverage annually during the Medicare Annual Enrollment Period from October 15 to December 7, you can switch Part D plans if your medications change or better options become available.
State Regulations and Consumer Protections
While federal law sets basic standards for medical supplement plans, state insurance departments provide additional oversight and consumer protections. North Carolina residents benefit from specific regulations that govern how these plans are sold and administered.
State regulators review and approve premium rate increases, investigate consumer complaints, and ensure companies follow proper sales practices. The CMS training materials on Medigap policies provide detailed information about these protections.
Your Rights as a Consumer
You have the right to:
- Review your policy within 30 days and cancel for a full refund if unsatisfied
- Receive clear, accurate information about coverage before purchasing
- File complaints with the state insurance department if you experience problems
- Appeal claim denials through a formal process
These protections ensure that medical supplement plans remain a reliable source of coverage throughout your retirement years.
Making an Informed Decision
Choosing among medical supplement plans requires evaluating your health needs, budget, and preferences. According to Kiplinger’s analysis of Medigap decisions, the choice you make during your initial enrollment period can affect your coverage and costs for years to come.
Questions to Consider
How often do you visit doctors? If you see specialists regularly or have ongoing health conditions, comprehensive coverage through Plan G might provide peace of mind and predictable costs.
What's your budget for premiums? Balance monthly premiums against potential out-of-pocket costs. Sometimes paying slightly higher premiums saves money overall if you need frequent care.
Do you travel frequently? Plans with foreign travel emergency coverage protect you during international trips, an important consideration for active retirees.
Are you comfortable with copays? Plan N's lower premiums come with small copays that might suit your preferences if you don't mind paying $20 for doctor visits.
Working with an experienced insurance professional helps you evaluate these factors based on your specific situation. Contact Moser Insurance Group Inc at moserinsurancegroup@gmail.com or visit moserinsurancegroup.com to discuss your options with someone who understands the unique needs of residents in High Point, Kernersville, and throughout the Triad Area.
Long-Term Planning and Policy Management
Once enrolled in medical supplement plans, you'll want to review your coverage periodically to ensure it continues meeting your needs. Unlike Medicare Advantage plans, you cannot easily switch Medigap plans after your initial enrollment period without potential medical underwriting.
When to Consider Changing Plans
Switching plans makes sense in limited circumstances:
- You're moving to a different state with different plan availability or pricing
- Your plan is being discontinued, giving you guaranteed issue rights to select another plan
- You qualify for a lower-cost plan and can pass medical underwriting
Most people keep their medical supplement plan for many years because the coverage remains stable and predictable. Your Plan G in 2026 will cover the same benefits in 2036, though premiums will likely increase over time.
For ongoing support with your Medicare coverage decisions, including coordination with dental, vision, and hearing benefits, maintaining a relationship with a trusted insurance advisor proves valuable.
Additional Coverage Considerations
While medical supplement plans provide excellent coverage for Medicare-approved services, they don't cover everything. Understanding what remains your responsibility helps you plan for complete healthcare protection.
What Medigap Doesn't Cover
Medical supplement plans typically don't pay for:
- Long-term care or custodial care in nursing facilities
- Vision care beyond what Medicare covers
- Dental care
- Hearing aids
- Private-duty nursing
Many retirees choose to purchase separate policies for these services or budget for these expenses independently. The predictable out-of-pocket costs with medical supplement plans make budgeting for additional services more manageable.
Household Planning
If both spouses need coverage, each requires their own individual medical supplement plan. You cannot share a policy. However, some insurance companies offer household discounts when both spouses purchase policies from the same company.
Planning for both individuals ensures continuous coverage regardless of life changes. The team at Moser Insurance Group Inc can help couples in Greensboro, Winston Salem, and surrounding areas coordinate their Medicare coverage efficiently.
Getting Official Information and Resources
The official Medicare guide to getting started with supplement insurance provides comprehensive information directly from the federal government. This resource explains coverage details, costs, and enrollment procedures in clear language.
Additional reliable sources include:
- The Medicare.gov website for plan comparisons and current information
- State Health Insurance Assistance Programs (SHIP) for free local counseling
- Your state insurance department for company complaint ratios and rate information
- Trusted insurance professionals who specialize in Medicare coverage
Combining information from multiple reputable sources helps you make confident decisions about your healthcare coverage. Don't hesitate to ask questions and seek clarification when something seems unclear.
Understanding medical supplement plans empowers you to make informed healthcare decisions as you navigate Medicare enrollment. Whether you're approaching 65 or helping a family member explore options, having clear guidance makes the process straightforward rather than overwhelming. Moser Insurance Group Inc specializes in helping residents throughout the Triad Area understand their Medicare options with personalized support and honest advice. Call 336-862-1763 or email moserinsurancegroup@gmail.com to discuss how we can help you choose the right coverage for your needs, or visit Moser Insurance Group Inc to learn more about our services.
Recent Comments