

Planning for retirement involves making informed decisions about how to protect your savings while generating reliable income. John Hancock annuities have served as a cornerstone retirement planning tool for decades, offering multiple product types designed to address different financial needs and risk tolerances. Whether you're approaching retirement age, already enrolled in Medicare, or helping a family member navigate their retirement options, understanding how these annuity products work can empower you to make confident financial decisions. This comprehensive guide explores the features, benefits, and considerations surrounding john hancock annuities to help you determine if they align with your retirement income goals.
Understanding John Hancock Annuities and Their Role in Retirement
John Hancock, a subsidiary of Manulife Financial Corporation, has maintained a strong presence in the life insurance and annuity market since 1862. The company offers a diverse portfolio of annuity products designed to provide guaranteed income streams, tax-deferred growth, and principal protection for retirement savers.
An annuity is a contract between you and an insurance company where you make either a lump-sum payment or series of payments in exchange for regular disbursements beginning immediately or at a future date. Annuities serve multiple purposes in retirement planning, from supplementing Social Security and pension income to creating a personal pension that you cannot outlive.
Types of John Hancock Annuities Available
John Hancock offers several annuity categories, each structured to meet specific financial objectives:
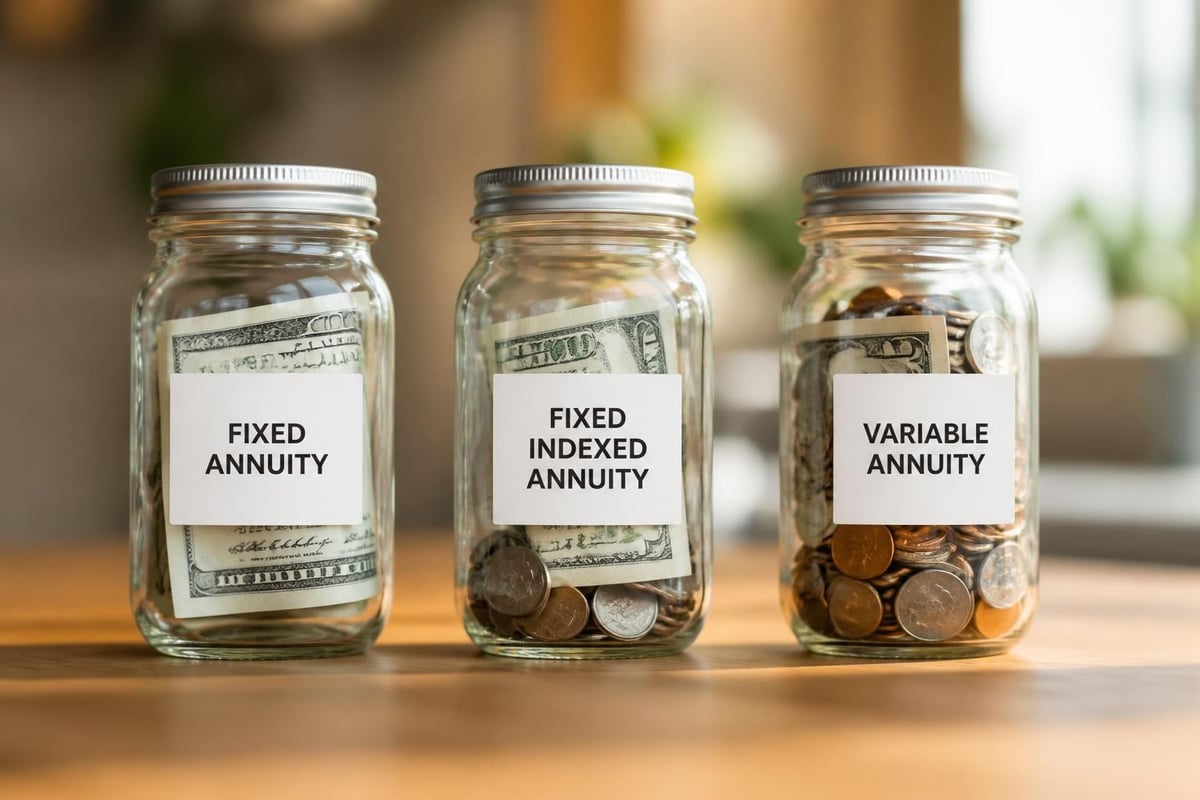
Fixed Annuities provide guaranteed interest rates for specified periods, protecting your principal while offering predictable growth. These contracts appeal to conservative investors who prioritize safety and certainty over potentially higher returns.
Fixed Indexed Annuities (FIAs) link your interest credits to the performance of market indexes like the S&P 500 while protecting your principal from market downturns. Fixed indexed annuities have become increasingly popular as investors seek upside potential with downside protection.
Variable Annuities allow you to invest in sub-accounts similar to mutual funds, offering growth potential tied directly to market performance. These products carry more risk but potentially higher returns, and the regulatory framework surrounding variable annuities requires careful disclosure of fees and risks.
Key Features of John Hancock Annuity Products
John Hancock annuities incorporate several distinguishing features that differentiate them from competitors and address specific retirement planning concerns.
Guaranteed Lifetime Income Riders
Many john hancock annuities offer optional guaranteed lifetime withdrawal benefits (GLWBs) that ensure you receive a specified percentage of your account value annually for life, regardless of market performance or how long you live. These riders typically require additional fees but provide valuable longevity protection.
| Rider Feature | Typical Structure | Cost Range |
|---|---|---|
| Guaranteed Withdrawal Percentage | 4-5% of benefit base annually | 0.75-1.25% of account value |
| Benefit Base Growth | 5-7% annual roll-up for deferral period | Included in rider fee |
| Joint Life Coverage | Available for married couples | Additional 0.15-0.35% |
Death Benefit Protection
Standard death benefit provisions ensure your beneficiaries receive at least your principal investment minus withdrawals, even if market performance has eroded your account value. Enhanced death benefit riders may offer step-up features that lock in market gains periodically.
Tax-Deferred Growth Advantages
Annuities grow tax-deferred, meaning you pay no taxes on interest, dividends, or capital gains until you begin withdrawals. This feature can be particularly valuable for individuals who have maximized contributions to IRAs and 401(k) plans and seek additional tax-advantaged retirement savings vehicles.
For those nearing Medicare eligibility, tax-deferred growth can also help manage modified adjusted gross income (MAGI), which affects Medicare Part B and Part D premium surcharges. Strategically timing annuity withdrawals can minimize these income-related monthly adjustment amounts (IRMAA).
Evaluating John Hancock Annuities for Your Situation
Determining whether john hancock annuities suit your retirement strategy requires examining your specific financial circumstances, risk tolerance, and income needs.
Assessing Your Income Gap
Begin by calculating your essential monthly expenses during retirement and comparing them against guaranteed income sources like Social Security and pensions. The difference represents your income gap, which annuities can help fill.
For example, if your monthly expenses total $4,500 and Social Security provides $2,200, you need an additional $2,300 monthly from other sources. An annuity with guaranteed lifetime income can cover part or all of this gap, reducing reliance on portfolio withdrawals that might be vulnerable to market volatility or sequence-of-returns risk.
Considering Your Health and Longevity
Actuarial research on annuity policyholder behavior shows that individuals who purchase lifetime income annuities typically live longer than average, a phenomenon called adverse selection. If you have family history of longevity or excellent health, annuities with lifetime income features become more valuable because you're more likely to receive payments beyond the breakeven point.
Conversely, if you have serious health conditions or family history suggesting shorter life expectancy, immediate annuities may not provide optimal value compared to keeping assets liquid or considering life insurance strategies that benefit your heirs.
Understanding Fees and Costs
Transparency about fees remains crucial when evaluating john hancock annuities, as costs directly impact your net returns and income.
Common Fee Structures
- Mortality and Expense (M&E) Charges: Variable annuities typically charge 1.0-1.5% annually to cover insurance guarantees and administrative costs
- Investment Management Fees: Sub-account fees in variable annuities range from 0.5-2.0% depending on investment options selected
- Rider Fees: Optional benefits like guaranteed lifetime withdrawal benefits cost 0.75-1.5% annually
- Surrender Charges: Early withdrawal penalties that decrease over time, typically 7-10 years
Comparing Total Costs
When evaluating costs, examine the total expense ratio rather than individual components. A john hancock variable annuity might charge 3.0% annually when combining M&E charges, sub-account fees, and rider costs. Compare this total to the value provided by guarantees and tax deferral.
Fixed and fixed indexed annuities typically embed costs within credited interest rates rather than assessing explicit annual fees. While fixed indexed annuities offer bond-like stability with equity upside, understanding how caps, spreads, and participation rates affect your actual returns helps set realistic expectations.
Market Position and Financial Strength
John Hancock's market position and financial stability matter because annuities represent long-term commitments, often spanning 20-30 years or more.
California Market Share Analysis
California’s 2024 life and annuity market share data provides insight into John Hancock's competitive position. The company maintains consistent market presence across multiple product categories, indicating stable distribution channels and competitive product features.
Financial Ratings Overview
John Hancock receives strong financial strength ratings from major rating agencies:
| Rating Agency | Current Rating | Meaning |
|---|---|---|
| AM Best | A+ | Superior ability to meet obligations |
| Moody's | A1 | Upper-medium grade, low credit risk |
| S&P Global | AA- | Very strong financial security |
| Fitch | AA- | Very strong capacity to meet commitments |
These ratings suggest john hancock annuities carry minimal insurer default risk, though state guaranty associations provide additional protection up to statutory limits (typically $250,000 per person) if an insurance company fails.
Integration with Medicare and Healthcare Planning
For individuals in the Triad Area including Greensboro, Kernersville, High Point, and Winston Salem approaching or enrolled in Medicare, coordinating annuity planning with healthcare coverage deserves careful attention.
Managing IRMAA Thresholds
Medicare Part B and Part D premiums increase when your modified adjusted gross income exceeds certain thresholds ($106,000 for individuals, $212,000 for couples in 2026). Large annuity withdrawals can push you into higher IRMAA brackets, increasing your Medicare costs by $70-$500+ monthly per person.
Strategic annuity income planning helps you withdraw amounts that meet income needs without triggering unnecessary IRMAA surcharges. Consider working with advisors who understand both annuity mechanics and Medicare enrollment considerations to optimize your overall retirement income strategy.
Medicaid Planning Considerations
If long-term care needs might arise, understand how annuities affect Medicaid eligibility. Immediate annuities may be structured as Medicaid-compliant if they meet specific requirements (irrevocable, non-assignable, actuarially sound, provide equal payments with no balloon payments, and name the state as beneficiary up to Medicaid benefits paid).
Deferred annuities typically count as available resources for Medicaid eligibility purposes, potentially delaying qualification for benefits until you spend down assets or convert them to exempt forms.
Distribution Options and Withdrawal Strategies
How you take income from john hancock annuities significantly impacts tax efficiency, longevity of assets, and overall retirement success.
Annuitization vs. Systematic Withdrawals
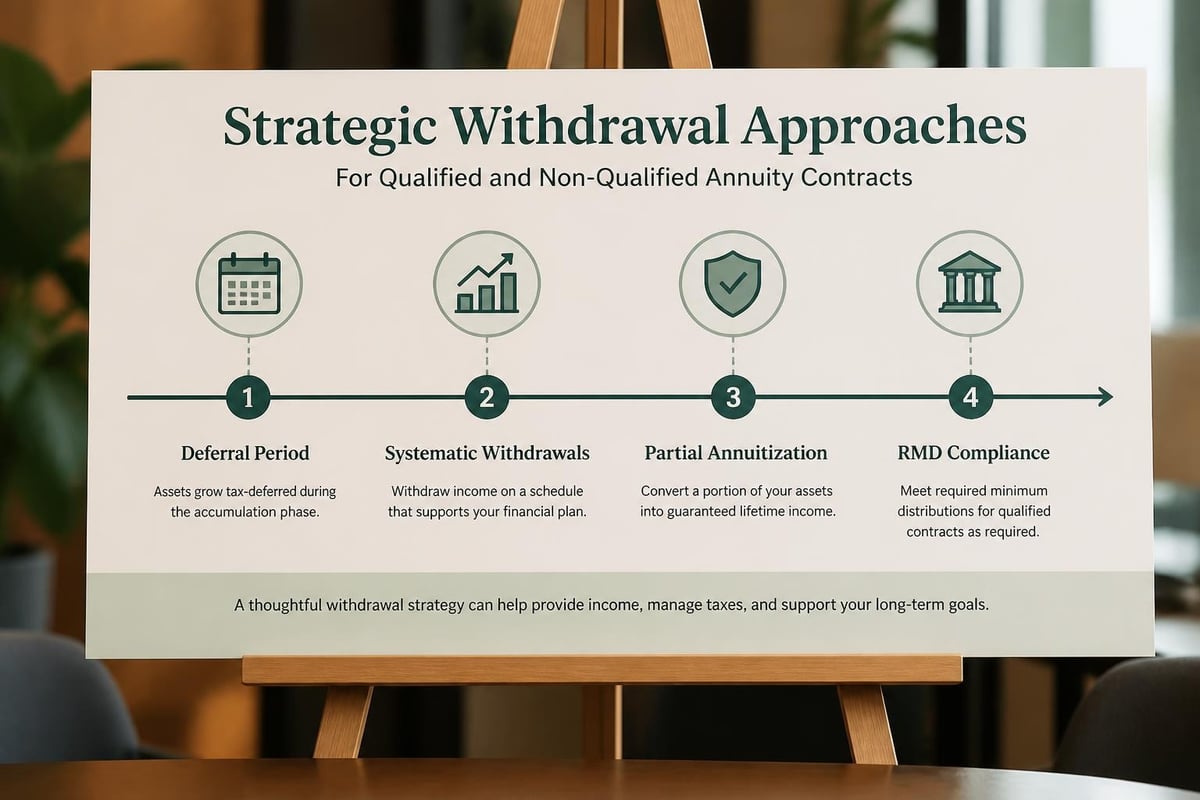
Annuitization converts your contract value into a stream of payments guaranteed for life or a specified period. Once annuitized, you typically cannot access lump sums or change payment amounts, but you receive maximum guaranteed income per dollar invested.
Systematic withdrawals allow you to take regular distributions while maintaining control over remaining assets. This flexibility enables you to adjust withdrawal amounts, access lump sums for emergencies, and leave remaining assets to beneficiaries, but provides less guaranteed income per dollar than full annuitization.
Required Minimum Distributions
Qualified annuities (those held in IRAs or other retirement accounts) require minimum distributions beginning at age 73 under current rules. Non-qualified annuities allow more flexibility but withdrawals before age 59½ typically incur 10% IRS penalties in addition to ordinary income tax on earnings.
Alternatives and Complementary Strategies
John hancock annuities represent one tool among many for retirement income planning. Comparing them to alternatives helps determine the optimal allocation.
Annuities vs. Bond Ladders
Bond ladders provide income through staggered maturity dates while preserving principal access. However, they lack longevity protection and may offer lower yields in low-interest-rate environments. Combining partial annuitization with bond holdings can provide both guaranteed lifetime income and liquidity.
Annuities vs. Dividend Stocks
Dividend-focused equity portfolios potentially offer growing income streams and inflation protection but carry market risk and no guarantees. A balanced approach might allocate a portion of assets to annuities for income flooring while maintaining equity exposure for growth and inflation hedging.
Coordinating with Life Insurance
For individuals who value legacy planning alongside income security, permanent life insurance products like whole life provide death benefits while building cash value. Some retirees use annuities for personal income security and life insurance to replace assets consumed during retirement, ensuring inheritances for beneficiaries.
Working with Qualified Professionals
Given the complexity and long-term nature of annuity contracts, working with knowledgeable professionals helps you navigate product features, tax implications, and suitability considerations.
Questions to Ask Advisors
When discussing john hancock annuities with insurance professionals, ask:
- What are the total costs including all fees and riders?
- How do surrender charges work and when can I access my money penalty-free?
- What happens to the contract if I need long-term care or pass away?
- How will annuity income affect my Medicare premiums and Social Security taxation?
- What alternatives did you consider and why do you recommend this specific product?
Red Flags to Watch
Approach with caution if advisors:
- Emphasize tax deferral for assets already in qualified retirement accounts
- Downplay fees or avoid providing written cost disclosures
- Pressure you to exchange existing annuities without thorough comparison
- Promise returns that seem unrealistic or minimize risks
- Cannot clearly explain how the product works or why it fits your situation
Regional Considerations for North Carolina Residents
For residents of the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, several regional factors influence annuity planning.
State Tax Treatment
North Carolina does not tax Social Security benefits and provides partial exclusions for pension and retirement income up to certain limits. Understanding how annuity distributions interact with state tax provisions helps optimize your overall tax efficiency.
Local Economic Conditions
Regional cost-of-living trends affect how much guaranteed income you need. Healthcare costs, property taxes, and general expenses in the Triad Area should inform your income gap calculation and annuity allocation decisions.
Access to Professional Guidance
Working with local professionals who understand both annuity products and regional retirement planning considerations provides valuable personalized support. When you're ready to explore options, reaching out to advisors who can explain how john hancock annuities fit within your complete financial picture ensures you make informed decisions aligned with your specific goals and circumstances.
If you need help understanding whether annuities complement your retirement strategy, or you're navigating Medicare coverage decisions as you approach retirement, professional guidance can clarify your options. You can contact Moser Insurance Group Inc at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com for personalized assistance tailored to your situation.
John hancock annuities offer multiple features designed to address retirement income needs, but determining whether they suit your specific situation requires careful evaluation of costs, features, alternatives, and how they integrate with your broader financial plan. The team at Moser Insurance Group Inc helps individuals and families in the Triad Area navigate complex insurance and retirement planning decisions with clear, pressure-free guidance. Whether you're exploring annuities, comparing Medicare supplement options, or evaluating life insurance strategies, reach out to Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your unique needs and make confident decisions about your financial future.
Recent Comments