

Navigating the landscape of health plans NC offers in 2026 requires understanding the diverse coverage options available to residents across the Triad Area and throughout the state. Whether you're approaching 65, seeking individual coverage, or exploring Medicare alternatives, North Carolina provides multiple pathways to comprehensive health protection. From Greensboro to Winston Salem, Kernersville to High Point, residents face important decisions about their healthcare coverage that can significantly impact both their financial security and access to quality medical services.
Understanding North Carolina's Health Insurance Landscape
The health insurance marketplace in North Carolina has evolved substantially over recent years, offering residents more choices than ever before. Health plans NC residents can select from include employer-sponsored coverage, individual marketplace plans, Medicare options, and alternative coverage arrangements.
North Carolina operates on the federal Health Insurance Marketplace rather than a state-based exchange, which means residents access coverage through Healthcare.gov during open enrollment periods. For 2026, the ACA marketplace plans in North Carolina provide standardized essential health benefits while offering various metal tiers to match different budgets and healthcare needs.
Coverage Categories Available in 2026
North Carolina residents can choose from several distinct health insurance categories:
- Medicare plans for individuals 65 and older or those with qualifying disabilities
- Marketplace plans through the Affordable Care Act exchange
- Individual and family plans purchased directly from insurers
- Employer-sponsored group coverage through workplace benefits
- Short-term health insurance for temporary coverage gaps
- Supplemental policies that enhance primary coverage
The right choice depends on your age, income level, health status, and specific medical needs. For residents in Greensboro, Kernersville, High Point, and Winston Salem, local insurance professionals can provide personalized guidance through these options.
Medicare Options for North Carolina Residents
For individuals approaching or past age 65, Medicare represents the primary health insurance pathway. Understanding health plans NC offers for Medicare beneficiaries involves exploring Original Medicare, Medicare Advantage, and supplemental coverage options.
Original Medicare Coverage
Original Medicare consists of Part A (hospital insurance) and Part B (medical insurance). Most North Carolina residents receive Part A premium-free if they or their spouse paid Medicare taxes for at least 10 years. Part B requires a monthly premium that adjusts annually based on income.
Key coverage components include:
- Hospital stays, skilled nursing facilities, hospice care (Part A)
- Doctor visits, outpatient services, preventive care (Part B)
- Durable medical equipment and certain home health services
- Limited prescription drug coverage (requires separate Part D plan)
Medicare Advantage Plans in the Triad Area
Medicare Advantage (Part C) plans bundle Original Medicare benefits with additional coverage, often including prescription drugs, dental, vision, and hearing services. Medicare Advantage options in North Carolina have expanded significantly, with multiple carriers offering HMO, PPO, and Special Needs Plans throughout the Triad Area.
| Plan Type | Network Restrictions | Prescription Coverage | Extra Benefits |
|---|---|---|---|
| HMO | Requires PCP referrals | Usually included | Dental, vision, fitness |
| PPO | Broader network options | Usually included | Telehealth, transportation |
| PFFS | Provider acceptance varies | Optional add-on | Limited extras |
| SNP | Specialized networks | Condition-specific | Targeted services |
Many beneficiaries in Greensboro, Winston Salem, and surrounding communities find Medicare Advantage plans attractive because they cap annual out-of-pocket expenses and consolidate coverage under one plan.
Medicare Supplement Insurance
Medicare Supplement plans fill the coverage gaps in Original Medicare, paying for copayments, coinsurance, and deductibles that Medicare doesn't cover. These standardized plans, designated by letters (Plan G, Plan N, etc.), provide predictable healthcare costs throughout retirement.
North Carolina residents selecting Medigap policies should compare:
- Monthly premium costs across different carriers
- Coverage standardization ensuring identical benefits by plan letter
- Guaranteed issue rights during initial enrollment periods
- Household discount opportunities when both spouses enroll
Contact Moser Insurance Group Inc at 336-862-1763 to discuss which Medicare supplement option aligns with your healthcare needs and budget.
ACA Marketplace Plans and Individual Coverage
For North Carolina residents not yet eligible for Medicare, the Health Insurance Marketplace provides access to comprehensive coverage with potential premium subsidies based on income.
Essential Health Benefits Required
All health plans NC marketplace plans must cover ten essential health benefit categories mandated by the Affordable Care Act:
- Ambulatory patient services
- Emergency services
- Hospitalization
- Maternity and newborn care
- Mental health and substance use disorder services
- Prescription drugs
- Rehabilitative services and devices
- Laboratory services
- Preventive and wellness services
- Pediatric services including dental and vision care
These standardized benefits ensure that regardless of which metal tier you select, your plan covers the same categories of care.
Metal Tier Selection Strategy
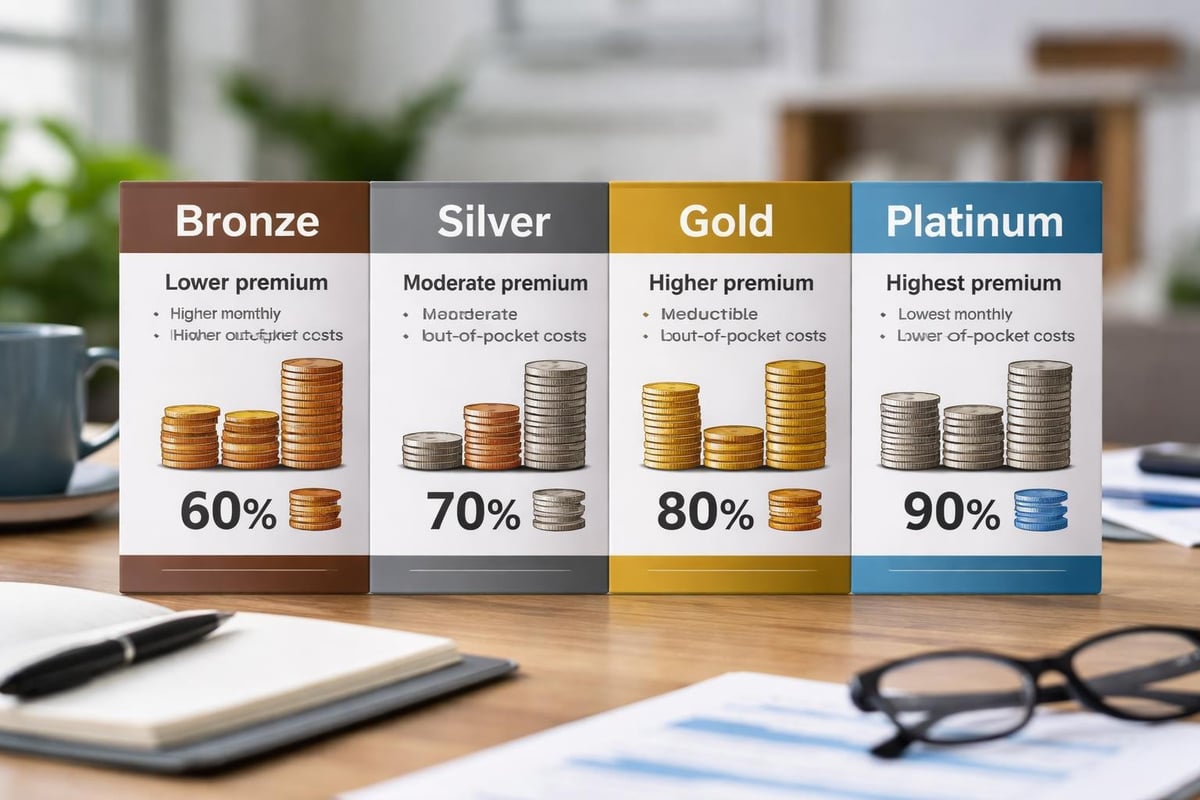
Marketplace plans are categorized into metal tiers that indicate how costs are shared between the insurer and enrollee:
Bronze Plans: Lower premiums with higher deductibles, suitable for healthy individuals who rarely need medical care beyond preventive services.
Silver Plans: Moderate premiums and cost-sharing, eligible for cost-sharing reductions that lower deductibles and copayments for qualifying households.
Gold Plans: Higher premiums with lower out-of-pocket costs when receiving care, beneficial for those with regular medical needs or prescription medications.
Platinum Plans: Highest premiums but lowest cost-sharing, ideal for individuals anticipating significant healthcare utilization.
The optimal choice depends on your expected healthcare needs for 2026 and your financial situation. Residents throughout the Triad Area can compare plans during the annual Open Enrollment Period running from November 1 through January 15.
Premium Tax Credits and Subsidies
Many North Carolina residents qualify for premium tax credits that reduce monthly insurance costs. For 2026, households with incomes between 100% and 400% of the federal poverty level may receive assistance, with extended subsidies available for those earning above 400% in certain circumstances.
Cost-sharing reductions provide additional savings by lowering deductibles, copayments, and coinsurance for Silver plan enrollees with household incomes between 100% and 250% of the poverty level. These subsidies make comprehensive coverage accessible to middle-income families across Greensboro, High Point, Winston Salem, and Kernersville.
Individual and Family Health Insurance Options
Beyond the marketplace, health plans NC residents can purchase include individual and family policies sold directly by insurance carriers. Individual and family plans offer network choices and coverage designs that may better suit specific needs.
Direct Purchase Advantages
Purchasing coverage directly from insurers provides several potential benefits:
- Extended enrollment periods beyond marketplace deadlines
- Broader plan selection including options not on the exchange
- Direct carrier relationships for customer service
- Potential access to regional carriers with strong local networks
However, direct purchase plans don't qualify for premium tax credits or cost-sharing reductions, making them most suitable for individuals whose income exceeds subsidy thresholds.
Network Considerations in the Triad Area
When evaluating health plans NC offers in the Triad Area, network composition significantly impacts your access to preferred providers. Major health systems serving Greensboro, Winston Salem, High Point, and Kernersville include Cone Health, Wake Forest Baptist Health, and Novant Health.
| Insurance Carrier | Network Type | Triad Area Coverage | Specialist Access |
|---|---|---|---|
| Blue Cross NC | Broad PPO | Comprehensive | Extensive |
| UnitedHealthcare | HMO/PPO options | Major facilities | Referral-based |
| Cigna | PPO networks | Selected providers | Direct access |
| Ambetter | Regional network | Growing presence | Limited specialists |
Verify that your current physicians, preferred hospitals, and any specialists you see regularly participate in the network before enrolling in any plan.
Alternative Health Coverage Solutions
North Carolina residents exploring alternatives to traditional health insurance should understand the differences between legitimate coverage and non-insurance products. The North Carolina Department of Insurance provides guidance on alternative plans that don't meet ACA requirements.
Health Care Sharing Ministries
Health care sharing ministries are religious or ethics-based organizations where members contribute monthly amounts that are shared to pay for medical expenses. These arrangements are not insurance and don't provide the consumer protections or coverage guarantees that regulated health plans NC offers must include.
Important limitations to consider:
- No guarantee that medical bills will be paid
- Pre-existing condition exclusions are common
- Preventive care often not covered
- No coverage for certain services based on religious beliefs
- Not subject to state insurance regulation
While monthly contributions may be lower than traditional premiums, members assume significantly more financial risk.
Short-Term Limited Duration Insurance
Short-term health insurance provides temporary coverage for gaps between permanent plans, typically lasting up to 12 months in North Carolina. These policies cost less than ACA-compliant coverage but offer substantially reduced benefits.
Short-term plans commonly exclude coverage for pre-existing conditions, maternity care, mental health services, and prescription drugs. They're best suited for healthy individuals facing brief coverage gaps rather than as long-term solutions.
For comprehensive protection, most North Carolina residents benefit from ACA-compliant marketplace plans, Medicare coverage, or employer group health insurance rather than alternative arrangements.
Supplemental Health Coverage to Enhance Protection
Many North Carolina residents enhance their primary health insurance with supplemental policies that provide additional financial protection. These specialized health plans NC offers can cover expenses that traditional medical insurance doesn't fully address.
Hospital Indemnity Insurance
Hospital indemnity policies pay cash benefits directly to policyholders when hospitalized, regardless of other insurance coverage. These fixed payments help cover deductibles, coinsurance, lost income, or non-medical expenses during hospital stays.
Benefits typically include:
- Daily hospital confinement benefit paying $100-$500 per day
- Admission benefit providing lump sum for each hospitalization
- ICU rider doubling or tripling daily benefits for intensive care
- Surgical benefit adding payment for operations
Hospital indemnity insurance proves particularly valuable for individuals with high-deductible health plans who want protection against unexpected hospitalization costs.
Dental and Vision Coverage
Original Medicare and many marketplace plans provide limited or no dental and vision coverage for adults. Standalone dental and vision insurance fills these gaps, making routine care and major services more affordable.
Comprehensive dental, vision, and hearing coverage helps Triad Area residents maintain overall health through preventive care while reducing out-of-pocket costs for glasses, contact lenses, dentures, and hearing aids.
Critical Illness and Cancer Insurance
Critical illness policies pay lump-sum benefits upon diagnosis of specified serious conditions such as heart attack, stroke, or cancer. These funds can be used for any purpose, including experimental treatments, travel to specialized facilities, or household expenses during recovery.
Cancer insurance specifically covers costs associated with cancer diagnosis and treatment, often paying for services not fully covered by major medical insurance.
Navigating Enrollment Periods and Special Circumstances
Understanding when you can enroll in health plans NC offers is crucial for maintaining continuous coverage. Missing enrollment deadlines can leave you uninsured or subject to limited plan options.
Medicare Initial Enrollment Period
Your Initial Enrollment Period for Medicare begins three months before your 65th birthday month, includes your birthday month, and extends three months after. This seven-month window is your best opportunity to enroll in Medicare without penalties.
Delaying Part B enrollment beyond this period can result in permanent premium increases unless you maintain qualifying employer coverage. If you’re turning 65, planning your Medicare enrollment at least three months in advance ensures smooth transition.
Marketplace Open Enrollment
The annual Open Enrollment Period for marketplace plans runs from November 1 through January 15 for coverage beginning January 1, 2026. North Carolina residents should compare available plans during this window, as it's the only time most people can enroll or change marketplace coverage.
Special Enrollment Periods
Certain qualifying life events trigger Special Enrollment Periods allowing you to enroll outside regular windows:
- Loss of existing coverage through job change or COBRA expiration
- Marriage, divorce, or legal separation
- Birth or adoption of a child
- Permanent move to an area with different plan availability
- Changes in household income affecting subsidy eligibility
- Becoming a U.S. citizen or legal resident
You typically have 60 days from the qualifying event to enroll in new coverage. Documentation proving the qualifying event is usually required.
Choosing the Right Health Plan for Your Situation
Selecting among the many health plans NC provides requires evaluating your specific circumstances, healthcare needs, and financial situation. A systematic approach ensures you choose coverage that protects both your health and your budget.
Assessment Factors to Consider
Healthcare utilization: Review your past year's medical expenses, prescription medications, and provider visits to estimate future needs.
Provider preferences: Verify whether your preferred doctors, hospitals, and specialists participate in plans you're considering.
Budget constraints: Calculate total annual costs including premiums, deductibles, copayments, and maximum out-of-pocket expenses.
Prescription needs: Compare drug formularies and tier placement for your medications across different plans.
Geographic coverage: Consider whether you travel frequently or divide time between locations requiring broader networks.
Comparing Total Cost of Coverage
Monthly premiums represent only one component of health insurance costs. A comprehensive comparison includes:
| Cost Component | Definition | Impact on Selection |
|---|---|---|
| Monthly Premium | Fixed payment for coverage | Higher premiums often mean lower costs when using care |
| Annual Deductible | Amount paid before insurance starts | Lower deductibles benefit frequent healthcare users |
| Copayments | Fixed fees per service | Predictable costs for routine care |
| Coinsurance | Percentage of costs after deductible | Affects major medical expenses |
| Out-of-Pocket Maximum | Annual spending cap | Critical protection against catastrophic costs |
Multiply monthly premiums by 12 and add your estimated annual deductible and typical copayments to project total yearly costs under different plans.
Professional Guidance Benefits
Working with an experienced insurance advisor provides valuable assistance navigating health plans NC offers. Moser Insurance Group Inc serves residents throughout Greensboro, Winston Salem, High Point, and Kernersville with personalized insurance guidance.
Professional advisors offer:
- Unbiased comparison of multiple carriers and plan types
- Clarification of complex insurance terminology and provisions
- Assistance with enrollment processes and paperwork
- Ongoing support for claims issues and coverage questions
- Annual reviews ensuring your coverage remains optimal
Email moserinsurancegroup@gmail.com or visit moserinsurancegroup.com to schedule a no-obligation consultation about your health insurance needs.
State-Specific Regulations and Consumer Protections
North Carolina maintains specific regulations governing health insurance that affect available plans and consumer rights. Understanding these protections helps you make informed decisions about coverage.
North Carolina Department of Insurance Oversight
The North Carolina Department of Insurance regulates insurance companies operating in the state, ensuring they maintain financial stability and comply with state laws. The department investigates consumer complaints, reviews rate increases, and provides educational resources about health plans NC residents can purchase.
Consumer protections include guaranteed renewal rights for most policies, prohibition of post-claims underwriting, and specific coverage mandates for certain conditions and treatments.
State Health Plan for Teachers and State Employees
The North Carolina State Health Plan provides coverage for over 750,000 teachers, state employees, retirees, and their dependents. Understanding the State Health Plan’s policies and procedures helps public sector workers maximize their benefits.
The plan operates under specific legal statutes that govern eligibility, coverage provisions, and administrative processes distinct from private health insurance.
Continuation Coverage Rights
North Carolina follows federal COBRA requirements allowing individuals who lose employer-sponsored coverage to continue their group health plan for limited periods by paying the full premium plus a small administrative fee. State continuation laws may extend these rights for smaller employers not subject to federal COBRA.
Understanding continuation rights prevents coverage gaps when transitioning between jobs or experiencing qualifying events that affect insurance eligibility.
Making Your Health Insurance Decision in 2026
The diverse landscape of health plans NC provides creates both opportunities and complexity for residents seeking coverage. Whether you're approaching Medicare eligibility, shopping the marketplace, or exploring supplemental protection, the key to making the right choice lies in understanding your options and carefully evaluating how each plan aligns with your needs.
Start your decision process by:
- Assessing your current and anticipated healthcare needs for 2026
- Calculating your budget for insurance premiums and out-of-pocket costs
- Identifying must-have providers or facilities that must be in-network
- Comparing specific plans available in your area of North Carolina
- Seeking expert guidance to navigate complex coverage decisions
For residents throughout the Triad Area, local expertise makes a significant difference in finding the right coverage. Professional insurance advisors understand the specific plans available in Greensboro, Winston Salem, High Point, and Kernersville, including which carriers offer the strongest networks and most competitive rates for your situation.
The investment of time in researching and comparing health plans NC offers pays dividends through years of appropriate coverage that protects your health without straining your finances. Don't rush this important decision or settle for inadequate coverage that leaves you exposed to financial risk.
Take advantage of the resources available, including comprehensive information about North Carolina health insurance options, to educate yourself about the choices you face. Understanding the fundamentals of health insurance empowers you to ask informed questions and recognize when a plan truly meets your needs versus when it simply sounds attractive due to low premiums.
Navigating the complex world of health insurance in North Carolina doesn't have to be overwhelming when you have knowledgeable support. Understanding health plans NC residents can access, from Medicare options to marketplace coverage and supplemental policies, positions you to make confident decisions about protecting your health and financial security. Moser Insurance Group Inc specializes in helping individuals and families throughout the Triad Area understand their insurance options without pressure or confusion. Whether you're turning 65, seeking individual coverage, or exploring supplemental protection, our team provides the clear guidance you need to select the right coverage. Call 336-862-1763 today to discuss your health insurance needs with an experienced advisor who puts your interests first.
Recent Comments