

Understanding your Medicare coverage options can feel overwhelming, especially when evaluating different insurance carriers and plan types. Blue Cross Medicare stands out as one of the most recognized names in Medicare coverage across the United States, offering multiple plan options that serve millions of beneficiaries. Whether you're approaching age 65, already enrolled in Medicare, or helping a loved one navigate their options, knowing what Blue Cross Medicare provides can help you make informed decisions about your healthcare future. This comprehensive guide explores the various plan types, coverage details, costs, and considerations specific to Blue Cross Medicare offerings available in 2026.
What Is Blue Cross Medicare
Blue Cross Medicare represents the Medicare-specific plans offered by Blue Cross Blue Shield companies across the United States. Unlike a single national company, Blue Cross Blue Shield operates as an association of independent companies serving different states and regions.
These companies provide Medicare coverage through three primary channels: Medicare Advantage plans (Part C), Medicare Supplement plans (Medigap), and prescription drug plans (Part D). Each Blue Cross Medicare plan type serves different needs and works differently with Original Medicare.
The specific plans available to you depend on where you live, as each Blue Cross Blue Shield company operates within designated service areas. In the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, residents have access to region-specific Blue Cross Medicare options.
How Blue Cross Medicare Differs From Original Medicare
Original Medicare consists of Part A (hospital insurance) and Part B (medical insurance), both administered by the federal government. Blue Cross Medicare plans work alongside or instead of Original Medicare to provide additional coverage.
Key differences include:
- Original Medicare has gaps in coverage, including deductibles, coinsurance, and no annual out-of-pocket maximum
- Blue Cross Medicare Advantage plans replace Original Medicare and often include extra benefits
- Blue Cross Medigap plans supplement Original Medicare by covering cost-sharing expenses
- Most Blue Cross Medicare plans include prescription drug coverage, which Original Medicare doesn't provide
Understanding these distinctions helps you determine which type of Blue Cross Medicare plan best fits your healthcare needs and budget.
Blue Cross Medicare Advantage Plans
Medicare Advantage plans from Blue Cross serve as an alternative to Original Medicare, providing all Part A and Part B coverage through a private insurance contract. Blue Cross Medicare Advantage plans bundle hospital insurance, medical coverage, and typically prescription drugs into a single plan.
These plans operate through managed care networks, meaning you'll typically need to use network providers except in emergencies. The trade-off for this network restriction is often lower premiums and additional benefits not covered by Original Medicare.
Types of Medicare Advantage Plans Available
Blue Cross Medicare Advantage plans come in several network configurations:
| Plan Type | Network Requirement | Referral Needed | Best For |
|---|---|---|---|
| HMO | In-network only (except emergencies) | Yes, from PCP | Lower premiums, coordinated care |
| PPO | In or out-of-network (lower cost in-network) | No | Flexibility to see specialists |
| PFFS | Any Medicare provider accepting plan terms | No | Rural areas with limited networks |
| SNP | In-network only | Yes | Specific health conditions or dual-eligible |
Each plan type offers different levels of flexibility and cost structures. HMO plans typically feature the lowest monthly premiums but require you to choose a primary care physician and get referrals for specialist care.
Additional Benefits Beyond Original Medicare
One significant advantage of Blue Cross Medicare Advantage plans is the inclusion of benefits that Original Medicare doesn't cover:
- Dental coverage for routine cleanings, fillings, and sometimes major work
- Vision benefits including eye exams and allowances for glasses or contacts
- Hearing services with coverage for exams and hearing aids
- Fitness programs like gym memberships or fitness classes
- Over-the-counter allowances for health-related items
- Transportation to medical appointments
- Telehealth services for virtual doctor visits
These extra benefits can provide substantial value, particularly if you require regular dental work or vision care. When evaluating Medicare Advantage health plans, consider which additional benefits matter most for your specific health situation.
Cost Structure for Medicare Advantage
Blue Cross Medicare Advantage plans typically involve several cost components:
- Monthly premium (in addition to Part B premium, which you still pay)
- Annual deductible (varies by plan, some have $0 deductibles)
- Copayments or coinsurance for services
- Maximum out-of-pocket limit (protects you from catastrophic costs)
Many Blue Cross Medicare Advantage plans feature $0 monthly premiums, though you'll still pay the standard Medicare Part B premium to the government. The maximum out-of-pocket limit is particularly valuable because Original Medicare has no such protection.
Blue Cross Medicare Supplement Plans
Medicare Supplement insurance, also called Medigap, helps cover the gaps in Original Medicare coverage. Blue Cross Medicare Supplement plans work differently than Medicare Advantage because they don't replace Original Medicare but instead supplement it.
When you have a Medigap plan, Medicare pays its share first, then your Medigap plan pays its share of approved charges. This coordination can significantly reduce your out-of-pocket costs for healthcare services.
Available Medigap Plan Types
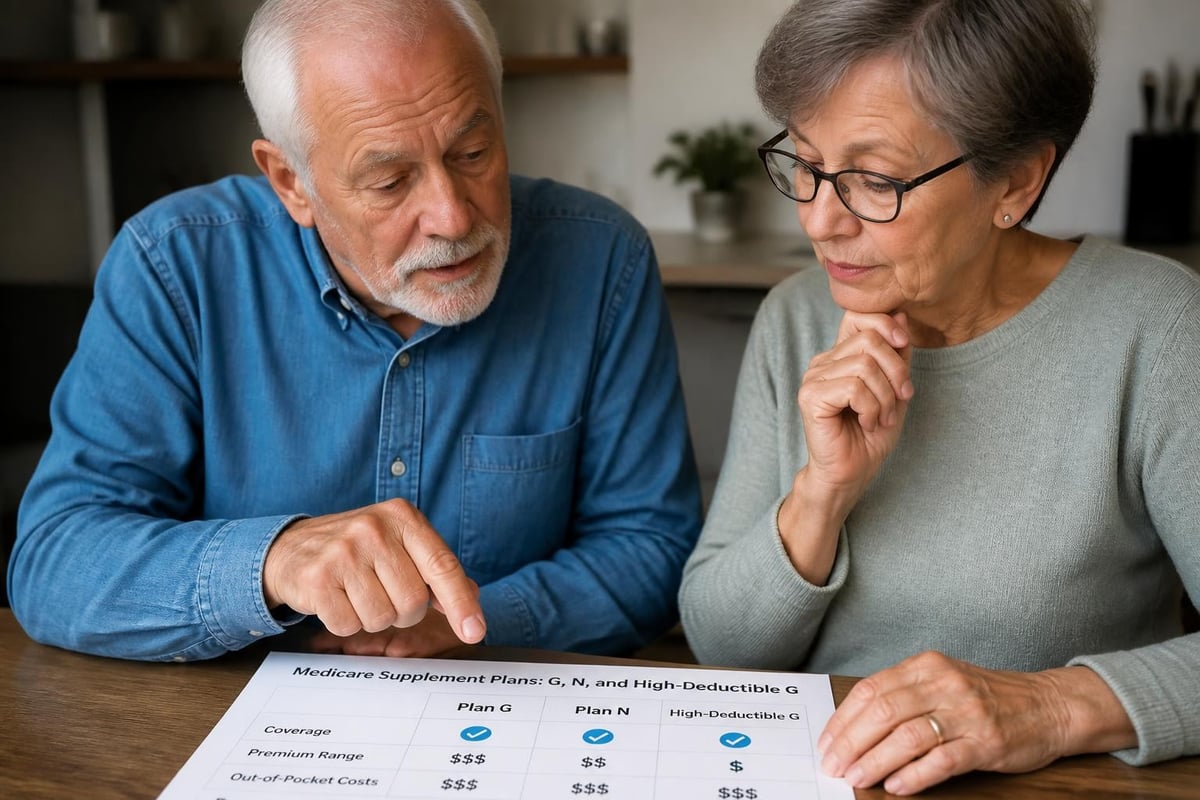
Medicare Supplement plans are standardized by the federal government, meaning a Plan G from one company offers the same basic benefits as Plan G from another company. Blue Cross Medicare offers several standardized Medigap plans:
- Plan A: Basic benefits including Part A coinsurance and hospital costs
- Plan B: Adds Part A deductible coverage
- Plan G: Comprehensive coverage except Part B deductible (most popular)
- Plan N: Lower premiums with small copays for doctor and emergency visits
- High-Deductible Plan G: Lower premiums but you pay a deductible before coverage begins
For individuals who want comprehensive coverage and predictable healthcare costs, Medicare Supplement Plans from Blue Cross provide financial protection and nationwide coverage flexibility.
How Medigap Differs From Medicare Advantage
Understanding the fundamental differences between these two Blue Cross Medicare options is critical:
| Feature | Medicare Supplement | Medicare Advantage |
|---|---|---|
| Works with Original Medicare | Yes, supplements it | No, replaces it |
| Network restrictions | None, any Medicare provider | Yes, typically HMO/PPO networks |
| Prescription drug coverage | Separate Part D needed | Usually included |
| Additional benefits | None | Often includes dental, vision, hearing |
| Guaranteed renewability | Yes, cannot be canceled | Must re-enroll annually |
| Cost predictability | High (covers most cost-sharing) | Variable (depends on services used) |
If you travel frequently or prefer seeing specialists without referrals, a Blue Cross Medicare Supplement plan might better suit your lifestyle. These plans provide coverage anywhere in the United States where Medicare is accepted.
Medigap Enrollment Timing
The best time to enroll in a Blue Cross Medicare Supplement plan is during your Medigap Open Enrollment Period, which lasts six months starting the first day of the month you're both 65 or older and enrolled in Medicare Part B.
During this period, you have guaranteed issue rights, meaning insurance companies cannot deny you coverage or charge higher premiums based on health conditions. Outside this window, you may face medical underwriting, higher costs, or even denial of coverage.
Blue Cross Medicare Part D Prescription Drug Plans
If you choose Original Medicare with or without a Medigap plan, you'll need separate prescription drug coverage through a Part D plan. Blue Cross Medicare offers standalone Part D plans that provide prescription drug coverage.
These plans feature formularies (lists of covered medications) organized into tiers, with generic drugs typically costing less than brand-name medications. Each plan negotiates prices with pharmacies and pharmaceutical companies, resulting in different costs depending on which plan you choose.
Part D Coverage Phases
Understanding how Part D coverage works throughout the year helps you anticipate costs:
- Deductible phase: You pay full cost until meeting the annual deductible (varies by plan)
- Initial coverage phase: You pay copays or coinsurance for medications
- Coverage gap: Costs increase after spending a certain amount on drugs
- Catastrophic coverage: After reaching out-of-pocket threshold, you pay minimal amounts
In 2026, changes to Medicare Part D eliminate the coverage gap ("donut hole") for many beneficiaries, providing more consistent cost-sharing throughout the year.
Choosing the Right Part D Plan
When selecting a Blue Cross Medicare Part D plan, consider these factors:
- Whether your current medications are on the plan's formulary
- The tier placement of your drugs (lower tiers cost less)
- Which pharmacies are in the plan's preferred network
- Monthly premium amounts
- Annual deductible requirements
- Coverage in the gap phase
Your specific medication needs should drive your Part D plan selection. A plan with a higher premium might actually cost less overall if it provides better coverage for expensive medications you take regularly.
Evaluating Blue Cross Medicare Coverage in Your Area
Blue Cross Medicare plan availability varies significantly by location. The Blue Cross Blue Shield company serving the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, offers region-specific plans with different networks, costs, and benefits.
Network Considerations
For Medicare Advantage plans, understanding provider and pharmacy networks is essential. Before enrolling:
- Verify your current doctors accept the specific Blue Cross Medicare Advantage plan
- Check if your preferred hospital is in-network
- Confirm your pharmacy participates in the plan's network
- Review specialist availability for any ongoing treatments
Switching plans during Annual Enrollment Period allows you to change coverage if your network needs change, but staying in-network throughout the year ensures lower costs.
Comparing Costs and Benefits
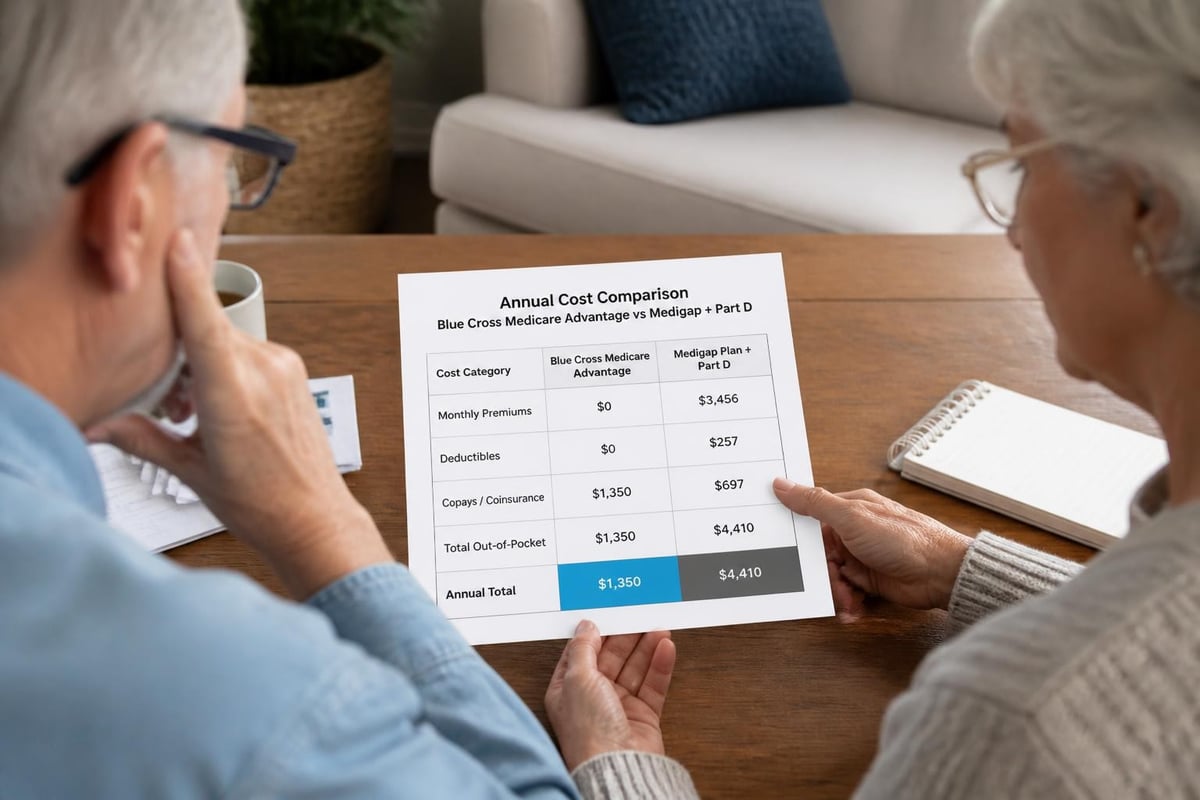
When evaluating blue cross medicare options, create a comprehensive cost comparison:
Monthly premium + estimated annual medical costs + prescription drug costs = total annual healthcare spending
A plan with a $0 monthly premium might seem attractive, but if it has higher copays for services you use frequently, you could spend more overall. Conversely, paying a higher monthly premium for comprehensive coverage might save money if you have significant healthcare needs.
When to Enroll in Blue Cross Medicare
Medicare has specific enrollment periods that determine when you can sign up for or change blue cross medicare coverage. Missing these windows can result in coverage gaps or late enrollment penalties.
Initial Enrollment Period
Your Initial Enrollment Period spans seven months: the three months before your 65th birthday month, your birthday month, and the three months after. During this time, you can enroll in Original Medicare and select either a Medicare Advantage plan or Medigap plan from Blue Cross Medicare.
For those receiving Social Security benefits before age 65, Medicare enrollment happens automatically. Others must actively apply for Medicare through the Social Security Administration.
Annual Enrollment Period
From October 15 through December 7 each year, all Medicare beneficiaries can make changes to their coverage for the following year. This Annual Enrollment Period allows you to:
- Switch from Original Medicare to a Medicare Advantage plan
- Change from one Medicare Advantage plan to another
- Drop Medicare Advantage and return to Original Medicare
- Add, drop, or switch Part D prescription drug plans
Changes made during this period take effect January 1 of the following year.
Special Enrollment Periods
Certain life events trigger Special Enrollment Periods that allow coverage changes outside the standard windows:
- Moving to a new service area
- Losing employer coverage
- Qualifying for Extra Help with prescription costs
- Moving into or out of a nursing home
- Qualifying for both Medicare and Medicaid
Understanding when you can enroll helps ensure continuous coverage without gaps or penalties.
Understanding Blue Cross Medicare Costs for 2026
Blue Cross Medicare plan costs vary based on multiple factors including your location, the specific plan you choose, and your healthcare utilization patterns. For 2026, several cost elements affect your total healthcare spending.
Premium Costs
Monthly premiums for Blue Cross Medicare plans range significantly:
- Medicare Advantage: $0 to $200+ monthly (plus Part B premium)
- Medigap: $100 to $400+ monthly depending on plan type and age
- Part D: $25 to $100+ monthly for standalone prescription coverage
Remember that even with a $0 premium Medicare Advantage plan, you still pay the standard Medicare Part B premium, which is $185 per month for most beneficiaries in 2026.
Out-of-Pocket Costs
Beyond premiums, you'll pay costs when using healthcare services:
Medicare Advantage copay examples:
- Primary care visit: $0-$20
- Specialist visit: $20-$50
- Emergency room: $90-$120
- Inpatient hospital stay: $250-$400 per day for limited days
Medigap coverage reduces or eliminates:
- Part A hospital deductible ($1,632 in 2026)
- Part B annual deductible ($240 in 2026)
- Part B coinsurance (typically 20% of approved amounts)
- Excess charges from doctors who don't accept Medicare assignment
The right choice depends on whether you prefer predictable monthly costs (Medigap) or lower premiums with variable out-of-pocket expenses (Medicare Advantage).
Getting Help With Blue Cross Medicare Decisions
Choosing the right blue cross medicare coverage requires careful evaluation of your health needs, budget, and preferences. The variety of plans and options can make the decision process complex, particularly if you're navigating Medicare for the first time.
Professional Guidance Benefits
Working with licensed insurance professionals who specialize in Medicare can provide several advantages:
- Personalized plan recommendations based on your specific situation
- Assistance comparing multiple Blue Cross Medicare options
- Guidance on enrollment timing and deadlines
- Help understanding how different plans work with your doctors
- Support with claims or coverage questions after enrollment
Independent agents can compare plans from multiple carriers, not just Blue Cross Medicare, ensuring you see all available options in your area.
Questions to Ask Before Enrolling
Before selecting any blue cross medicare plan, gather answers to these important questions:
- Does the plan cover my current medications, and at what cost?
- Are my doctors and hospitals in the plan's network?
- What is my estimated total annual cost including premiums and out-of-pocket expenses?
- Does the plan include benefits I value, such as dental or vision coverage?
- Can I afford the maximum out-of-pocket limit if I have significant health issues?
- How does this plan compare to other options available in my area?
Taking time to thoroughly evaluate your options leads to better long-term satisfaction with your Medicare coverage.
Resources for Medicare Information
Several reliable resources provide information about Blue Cross Medicare options and Medicare in general:
- Medicare.gov for official plan comparisons and enrollment
- State Health Insurance Assistance Programs (SHIP) for free counseling
- Blue Cross Blue Shield company websites for plan-specific details
- Licensed insurance agents who can provide personalized recommendations
When researching insurance Medicare options, verify that information is current for 2026, as plan details change annually.
Regional Availability in North Carolina
For residents in the Triad Area, Greensboro, Kernersville, High Point, and Winston Salem, Blue Cross Medicare plans are administered by Blue Cross Blue Shield of North Carolina. The specific plans available in this region may differ from those offered in other states.
Local Network Considerations
Healthcare systems serving the Triad Area participate in various Blue Cross Medicare networks. Before enrolling, verify that your preferred providers accept your specific plan:
- Major hospital systems in Greensboro and Winston Salem
- Primary care physicians throughout Kernersville and High Point
- Specialist practices across the Triad region
- Preferred pharmacies in your local area
Network participation can change annually, so reviewing provider directories each year during Annual Enrollment Period ensures your doctors remain in-network.
Getting Local Support
Working with local insurance professionals who understand the Triad Area healthcare landscape provides valuable insights. They can explain which Blue Cross Medicare plans work best with regional providers and help you understand coverage nuances specific to North Carolina.
For personalized assistance with Blue Cross Medicare options in Greensboro, Kernersville, High Point, or Winston Salem, contact Moser Insurance Group Inc at 336-862-1763 or email moserinsurancegroup@gmail.com.
Common Blue Cross Medicare Questions
Can I Keep My Doctor With Blue Cross Medicare?
Whether you can keep your current doctor depends on the plan type you choose. Medigap plans allow you to see any provider accepting Medicare patients nationwide. Medicare Advantage plans require using network providers except in emergencies, so you must verify your doctor participates in your specific plan's network.
What Happens If I Travel?
Blue Cross Medigap plans provide coverage anywhere in the United States where Medicare is accepted, making them ideal for frequent travelers. Medicare Advantage plans typically provide emergency coverage nationwide but may have limited coverage for non-emergency care outside your service area. Some plans offer nationwide PPO networks with broader travel coverage.
Can I Change Plans If I'm Not Satisfied?
You can change Medicare Advantage or Part D plans during Annual Enrollment Period (October 15 to December 7). However, switching from Medicare Advantage to Medigap outside your initial enrollment period may require medical underwriting, and you could be denied coverage or charged higher rates based on health conditions.
Does Blue Cross Medicare Cover Pre-Existing Conditions?
Yes, Medicare prohibits discrimination based on pre-existing conditions. During your Medigap Open Enrollment Period, you have guaranteed issue rights regardless of health status. Medicare Advantage plans cannot deny coverage based on pre-existing conditions, though they may limit coverage for certain treatments during the first year.
How Do Blue Cross Medicare Costs Compare to Other Carriers?
Blue Cross Medicare plan costs vary by region and plan type. While Blue Cross is often competitively priced, costs can differ significantly between carriers. Comparing multiple Medicare options from different companies ensures you find the best value for your specific needs and location.
Navigating blue cross medicare options requires understanding the differences between Medicare Advantage, Medigap, and Part D plans, along with how each fits your healthcare needs and budget. Whether you're approaching Medicare eligibility or considering a plan change during Annual Enrollment Period, thorough research and professional guidance lead to better coverage decisions. Moser Insurance Group Inc helps individuals and families in the Triad Area understand their Medicare options with clear guidance and personalized support, enabling you to make confident insurance decisions without pressure. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your Blue Cross Medicare options today.
Recent Comments