
Index universal life insurance represents a sophisticated financial product that blends permanent life insurance protection with the opportunity to build cash value linked to market indexes. As individuals and families in the Triad Area, Greensboro, Kernersville, High Point, and Winston Salem explore life insurance options, understanding how index universal life insurance works becomes increasingly important for making informed decisions. This comprehensive guide examines the mechanics, benefits, considerations, and costs associated with this growing segment of the permanent life insurance market.
Understanding Index Universal Life Insurance Basics
Index universal life insurance (IUL) is a type of permanent life insurance that offers lifetime coverage with a cash value component tied to the performance of a market index, typically the S&P 500. Unlike traditional universal life insurance policies that credit interest at a fixed rate declared by the insurer, index universal life insurance policies calculate cash value growth based on the upward movement of a stock market index.
The fundamental structure includes three key elements: death benefit protection that lasts as long as premiums are paid, flexible premium payments that allow policyholders to adjust contributions within certain limits, and cash value accumulation that grows based on index performance subject to caps and floors. This design positions IUL as a middle ground between whole life insurance's guaranteed growth and variable universal life's direct market exposure.
How the Indexing Mechanism Works
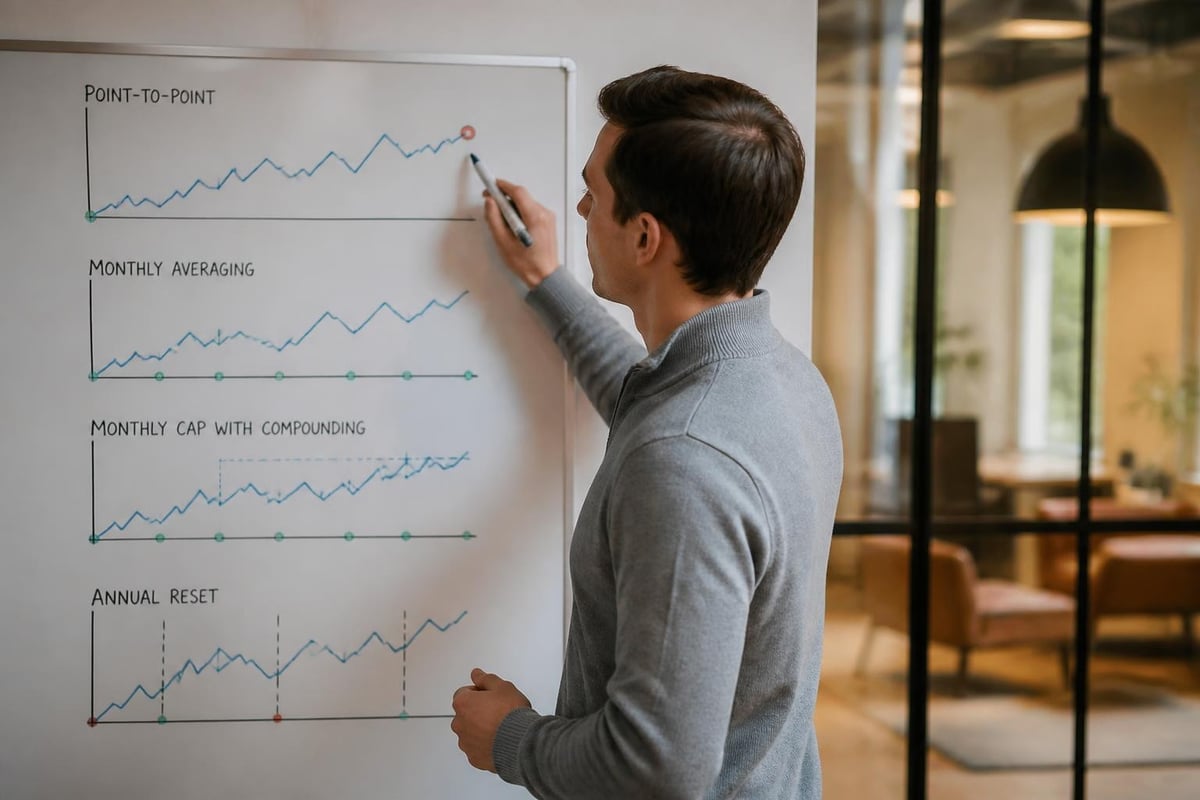
The crediting method determines how your cash value participates in index gains. Most policies use one of several calculation methods:
- Point-to-point: Measures index change from policy anniversary to anniversary
- Monthly averaging: Takes the average of monthly index values over the year
- Monthly cap: Credits gains monthly, each subject to a cap, then compounds
- Annual reset: Locks in gains annually and resets the starting point
According to research from the Society of Actuaries, the performance of index universal life insurance products varies significantly based on which crediting method insurers employ and how they set participation rates and caps.
Key Features and Policy Components
Index universal life insurance includes several distinctive features that differentiate it from other permanent life insurance products. Understanding these components helps prospective policyholders evaluate whether IUL aligns with their financial goals and risk tolerance.
Caps, Floors, and Participation Rates
The cap represents the maximum interest rate your cash value can earn in a given period, regardless of how high the index climbs. For example, if your policy has a 10% cap and the S&P 500 gains 15%, your cash value receives only a 10% credit. The floor, typically set at 0% or 1%, protects you from losses when the index declines. The participation rate determines what percentage of index gains you receive up to the cap.
| Component | Typical Range | What It Means |
|---|---|---|
| Cap Rate | 8% – 14% | Maximum annual credit you can receive |
| Floor Rate | 0% – 1% | Minimum credit (protects from market losses) |
| Participation Rate | 25% – 100% | Percentage of index gain you capture |
| Spread/Margin | 0% – 4% | Amount deducted from index gain before crediting |
These parameters directly impact long-term cash value growth. FINRA’s guidance on indexed products emphasizes understanding these limitations before purchasing, as illustrated projections may assume higher caps than insurers ultimately deliver.
Premium Flexibility and Payment Options
One significant advantage of index universal life insurance involves premium flexibility. Unlike whole life policies with fixed payments, IUL allows you to:
Increase premiums when finances permit, accelerating cash value growth and potentially creating tax-advantaged retirement income streams. Decrease or skip payments during financial hardship, provided sufficient cash value exists to cover policy charges. Make lump-sum contributions up to IRS limits without triggering modified endowment contract (MEC) status.
This flexibility appeals to business owners, commission-based professionals, and others with variable income. However, IRS Publication 525 outlines strict limits on how much you can contribute without converting the policy into a MEC, which changes the tax treatment of withdrawals and loans.
The Growth Potential and Downside Protection
The dual promise of market-linked growth with downside protection attracts many individuals to index universal life insurance. During bull markets, policyholders can capture meaningful gains (up to the cap), while the floor prevents losses during market corrections. This asymmetric return profile differs substantially from direct equity investment.
Realistic Growth Expectations
Historical backtesting suggests that IUL policies typically credit between 5% and 8% annually over extended periods, depending on market conditions and policy parameters. However, NAIC’s guidance on life insurance illustrations warns consumers that non-guaranteed projections used in sales presentations often assume optimistic scenarios that may not materialize.
Several factors influence actual credited returns:
- Current cap and participation rate settings (which insurers can adjust)
- The crediting method employed
- Sequence of returns (when gains and losses occur)
- Policy loan activity that reduces the indexed account value
- Index volatility patterns during the measurement period
Data from LIMRA’s industry research shows that indexed universal life insurance sales reached record levels in 2024, partly driven by consumer interest in products offering growth potential during periods of low fixed interest rates.
Costs, Fees, and Policy Charges
Understanding the cost structure of index universal life insurance is essential for evaluating long-term value. Unlike term life insurance with straightforward premiums, IUL policies include multiple internal charges that reduce cash value accumulation.
Internal Policy Expenses
The primary costs embedded in index universal life insurance include:
Cost of insurance (COI): Monthly charges for the death benefit, which increase with age and can rise substantially in later years. Administrative fees: Fixed monthly charges ($10-$30) plus potential percentage-based fees on cash value. Premium load: Some policies charge 3-8% of each premium payment before allocating funds to cash value. Surrender charges: Early policy termination triggers fees that decline over 10-15 years.
These expenses mean that significant premiums must be paid before meaningful cash value accumulation begins. NerdWallet’s consumer guide emphasizes understanding the break-even point, which typically occurs 8-12 years into the policy, depending on funding level and performance.
Comparing Cost Efficiency Across Products
When evaluating index universal life insurance against alternatives like whole life or term life coverage, consider the total cost per thousand dollars of coverage over your expected lifetime:
| Product Type | Cost/Structure | Cash Value Growth | Flexibility |
|---|---|---|---|
| Index Universal Life | Variable COI + fees | Index-linked (0%-cap%) | High premium flexibility |
| Whole Life | Fixed premium | Guaranteed + dividends | No flexibility |
| Term Life | Level term premium | None | No cash value |
| Universal Life | Variable COI + fees | Fixed declared rate | High premium flexibility |
For individuals in Greensboro, Kernersville, High Point, and Winston Salem seeking life insurance guidance, the cost-benefit analysis depends heavily on your time horizon, funding capacity, and whether tax-advantaged cash value accumulation justifies the higher expense versus purchasing term coverage and investing the difference.
Tax Advantages and Wealth-Building Strategies
The tax treatment of index universal life insurance creates opportunities for sophisticated financial planning, particularly for high-income individuals who have maxed out qualified retirement plans like 401(k)s and IRAs.
Tax-Deferred Growth and Tax-Free Access
Cash value inside an index universal life insurance policy grows tax-deferred, meaning you owe no annual taxes on credited interest. This contrasts with taxable investment accounts where dividends and capital gains trigger tax obligations. Additionally, the NAIC’s Life Insurance Buyer’s Guide explains that properly structured policy loans and withdrawals can provide tax-free income in retirement.
The strategy typically works as follows:
- Overfund the policy during working years (up to MEC limits)
- Allow cash value to compound tax-deferred for 15-30 years
- Take policy loans against cash value in retirement
- Leave loans unpaid during life; death benefit repays loans tax-free
This approach requires substantial premium commitments and careful monitoring. If policy performance disappoints and you cannot afford additional premiums, the policy may lapse with taxable income on previous gains.
Estate Planning Benefits
The death benefit from index universal life insurance passes income-tax-free to beneficiaries, making it useful for estate liquidity. Wealthy individuals in the Triad Area often use IUL within irrevocable life insurance trusts (ILITs) to remove proceeds from taxable estates while maintaining growth potential through indexing.
For 2026, the federal estate tax exemption sits at approximately $13.99 million per individual, but this may sunset after 2025 unless extended by legislation. Index universal life insurance offers a vehicle for transferring wealth efficiently when estate taxes concern your family's financial future.
Choosing the Right Funding Strategy
The amount you contribute to index universal life insurance significantly impacts policy performance, cost efficiency, and long-term sustainability. Three common funding approaches exist, each with distinct advantages and risks.
Minimum Premium Strategy
Paying only enough to keep the policy in force minimizes current out-of-pocket cost but results in minimal cash value growth. This approach treats IUL primarily as death benefit protection rather than a wealth-building tool. Given the relatively high cost structure compared to term insurance, minimum funding rarely represents the most cost-effective choice for pure protection needs.
Target Premium Strategy
Most carriers recommend a "target premium" designed to balance reasonable cash value accumulation with manageable payments. This middle-ground approach provides moderate cash value growth while maintaining some premium flexibility during financial challenges.
Maximum Funding (Just Below MEC Limits)
Affluent individuals often maximize contributions up to the IRS threshold that triggers MEC status. This aggressive funding strategy:
- Minimizes the cost of insurance as a percentage of premium
- Accelerates cash value growth
- Creates larger tax-free loan capacity for retirement
- Requires substantial ongoing premium commitments ($20,000-$100,000+ annually)
Before committing to high premium levels, work with qualified financial professionals to model various scenarios. You can reach Moser Insurance Group at 336-862-1763 or moserinsurancegroup@gmail.com to discuss whether maximum funding aligns with your broader financial plan and risk tolerance.
Performance Monitoring and Policy Management
Unlike term life insurance that requires minimal attention after purchase, index universal life insurance demands active management to ensure it performs as intended and remains in force throughout your lifetime.
Annual Policy Review Checklist
Conduct comprehensive reviews annually to verify your IUL policy stays on track:
- Current cash value vs. illustrated projections at policy issue
- Recent crediting rate and how it compared to the index movement
- Current cap and participation rates (insurers can adjust these)
- Cost of insurance charges and whether they've increased
- Outstanding policy loans and their impact on death benefit
- Required premiums to maintain coverage given current performance
Significant performance shortfalls may require increased premium contributions to prevent policy lapse. The Milliman industry insight on five-year trends reveals that some older IUL policies have experienced challenges as low interest rates reduced insurer profitability, prompting higher COI charges or reduced caps.
Warning Signs and Corrective Actions
Several red flags indicate your index universal life insurance policy needs attention:
Crediting rates consistently below illustrations: May require premium increases to maintain intended death benefit and cash value targets. Rising cost of insurance charges: Age-based increases are normal, but unexpected jumps warrant investigation. Declining cash value: Can occur due to high loan balances, poor index performance, or insufficient premiums. Lapse notices: Insurers must provide warnings when policies risk terminating, but catching problems early costs less than emergency funding.
Moser Insurance Group provides ongoing policy review services for clients throughout Greensboro, Kernersville, High Point, and Winston Salem, helping ensure your coverage adapts as your circumstances and policy performance evolve.
Comparing Index Universal Life to Alternatives
Determining whether index universal life insurance serves your needs better than alternatives requires examining your specific objectives, time horizon, risk tolerance, and budget.
Index Universal Life vs. Whole Life Insurance
Whole life insurance offers guaranteed cash value growth plus potential dividends from mutual insurers, providing more predictability than IUL's variable crediting. However, index universal life insurance typically offers higher growth potential during strong market periods and greater premium flexibility. Understanding different types of life insurance helps clarify which structure fits your priorities.
Index Universal Life vs. Variable Universal Life
Variable universal life (VUL) allows direct investment in subaccounts resembling mutual funds, offering unlimited upside potential but exposing cash value to full market volatility, including losses. Index universal life insurance provides downside protection through the floor but limits gains through the cap. VUL suits investors comfortable with market risk, while IUL appeals to those seeking a middle path between guaranteed products and market exposure.
Index Universal Life vs. Term Plus Investment Strategy
Financial advisors often debate whether buying lower-cost term insurance and investing the premium difference outperforms purchasing index universal life insurance. The comparison depends on:
- Investment discipline: Will you actually invest the difference consistently?
- Tax efficiency: IUL's tax advantages vs. taxable investment accounts
- Time horizon: Longer periods favor IUL's tax deferral and permanent coverage
- Estate needs: Term expires; IUL provides lifetime death benefit
Neither approach universally dominates; the optimal choice reflects your specific circumstances, financial behaviors, and comprehensive planning objectives.
Evaluating Carriers and Policy Design
Not all index universal life insurance policies are created equal. Carrier financial strength, product design, pricing competitiveness, and service quality all impact long-term satisfaction and performance.
Insurer Financial Strength Ratings
Because index universal life insurance represents a multi-decade commitment, selecting financially stable carriers is paramount. Major rating agencies assess insurer financial strength:
| Rating Agency | Top Rating | What It Measures |
|---|---|---|
| A.M. Best | A++ | Claims-paying ability and balance sheet strength |
| Standard & Poor's | AAA | Long-term creditworthiness |
| Moody's | Aaa | Financial strength and stability |
| Fitch | AAA | Ability to meet policyholder obligations |
Focus on carriers with ratings of A or better from multiple agencies. Even highly-rated insurers occasionally struggle; diversifying across multiple policies with different carriers reduces concentration risk for substantial coverage amounts.
Product Features to Compare
When evaluating specific index universal life insurance policies, examine:
Available index options: Some carriers offer multiple indexes (S&P 500, Nasdaq, Russell 2000) allowing diversification. Crediting methods: Point-to-point annual may suit some situations better than monthly averaging. Multiplier or bonus features: Enhanced crediting in early years to accelerate cash value. No-lapse guarantee options: Riders ensuring coverage continues even with poor performance. Guaranteed caps and participation rates: Some policies guarantee minimum levels for set periods.
Working with knowledgeable professionals helps navigate these technical distinctions. Moser Insurance Group at moserinsurancegroup.com provides personalized guidance on carrier selection and product design for residents of the Triad Area.
Common Misconceptions and Pitfalls
Despite its benefits, index universal life insurance is often misunderstood or misrepresented during the sales process. Awareness of common misconceptions helps you make more informed decisions.
"You Get Market Returns Without Market Risk"
While index universal life insurance participates in index gains, the cap significantly limits upside. During the 2013-2021 bull market when the S&P 500 averaged roughly 16% annually, IUL policies typically credited 8-12% due to caps. You receive some market upside with downside protection, not full market returns with no risk.
Over-Reliance on Illustrated Returns
Sales illustrations show how policies might perform at assumed crediting rates, often 6-7%. However, these are non-guaranteed projections. Actual returns depend on future market conditions, insurer pricing decisions on caps and participation rates, and whether you maintain illustrated premium levels. Always review pessimistic scenarios showing lower crediting rates (3-4%) to understand required funding under adverse conditions.
Ignoring the Cost Structure
Some presentations emphasize tax-free retirement income without adequately disclosing the substantial fees that must be overcome before meaningful cash value accumulates. In early years, 40-60% of premiums may go toward costs of insurance, administrative fees, and premium loads. This differs dramatically from low-cost index funds charging 0.05-0.20% annually.
Policy Lapse Risk
If premium payments stop or loans exceed cash value, index universal life insurance policies can lapse, potentially creating taxable income on gains and leaving you without coverage precisely when age makes replacement prohibitively expensive. Maintaining adequate funding throughout your lifetime is essential.
Making an Informed Decision
Deciding whether index universal life insurance fits your financial plan requires careful analysis of your complete situation, not just the product's features in isolation.
Who Benefits Most from Index Universal Life Insurance?
Ideal candidates typically share several characteristics:
- High income earners who've maximized qualified retirement plans
- Long time horizons of 20+ years before needing policy benefits
- Substantial premium capacity to fund beyond minimum levels
- Permanent life insurance needs for estate planning or income replacement
- Moderate risk tolerance seeking growth with downside protection
- Desire for tax diversification beyond qualified retirement accounts
Conversely, those with limited budgets, short time horizons, or purely seeking death benefit protection often find better value in term life insurance or guaranteed universal life products.
Questions to Ask Before Purchasing
Before committing to index universal life insurance, obtain clear answers to:
- What crediting rate scenarios has the carrier modeled (optimistic, middle, pessimistic)?
- How have caps and participation rates changed on this product over the past decade?
- What premium must I pay at various crediting rates to keep the policy in force until age 100?
- How do policy loans affect death benefit and credited interest?
- What happens if I need to reduce or stop premiums temporarily?
- What are total fees as a percentage of premium in years 1, 5, 10, and 20?
- How does this product compare to your carrier's other permanent life insurance options?
Reputable advisors welcome detailed questions and provide transparent answers. Pushy sales tactics or reluctance to show pessimistic scenarios should raise concerns.
Index universal life insurance offers a unique combination of permanent protection, flexible funding, tax advantages, and market-linked growth potential that appeals to many individuals seeking sophisticated financial planning tools. However, the complexity, cost structure, and performance variables demand thorough understanding before committing substantial premiums over decades. Whether you're exploring options in Greensboro, High Point, Kernersville, Winston Salem, or throughout the Triad Area, Moser Insurance Group provides personalized guidance to help you evaluate if index universal life insurance aligns with your goals. Contact us at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your specific situation without pressure and make confident insurance decisions backed by clear, honest education.
Recent Comments