

Understanding your life insurance options can feel overwhelming, especially when you're trying to make the right decision for your family's future. Level life insurance offers a straightforward approach to financial protection, providing predictable premiums and consistent death benefits throughout your policy term. This type of coverage has become increasingly popular among families in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, who value budget certainty and long-term planning. Whether you're protecting your mortgage, supporting your children's education, or ensuring your spouse's financial security, knowing how level life insurance works helps you make confident decisions without pressure.
Understanding Level Life Insurance Basics
Level life insurance represents a specific structure where both your premium payments and death benefit remain constant throughout the entire policy term. This predictability makes budgeting easier and eliminates surprises down the road.
Fixed Premiums for the Duration
When you purchase level life insurance, the monthly or annual premium you pay stays exactly the same from day one until the policy expires. This stability differs significantly from other insurance types where costs can increase over time.
Key premium advantages include:
- Predictable monthly budgeting without unexpected increases
- Protection against age-related price hikes
- Locked-in rates based on your health at application
- Easy financial planning for families and retirees
The premium amount gets determined when you apply, based on factors like your age, health status, occupation, and coverage amount. Once approved, that rate cannot change regardless of how your health changes during the term.
Consistent Death Benefit Protection
The death benefit in level life insurance remains unchanged throughout the policy period. If you purchase $500,000 in coverage, your beneficiaries receive that full amount whether you pass away in year one or year twenty of the term.
This consistency provides peace of mind because you know exactly what your family will receive. There's no depreciation, no reduction in value, and no complicated calculations. The payout remains level, which is where the policy type gets its name.
Common Term Lengths and Coverage Options
Level life insurance typically comes in standard term lengths that align with major life milestones and financial obligations. Understanding these options helps you match coverage to your specific needs.
Standard Term Periods
| Term Length | Best For | Typical Use Cases |
|---|---|---|
| 10 Years | Short-term debt, young professionals | Business loans, small mortgages, temporary income replacement |
| 20 Years | Growing families, medium-term obligations | Raising children through college, moderate mortgages, career-building years |
| 30 Years | Long-term family protection | Full mortgage coverage, infant to adulthood child support, comprehensive planning |
Most carriers offer these three primary term lengths, though some provide 15-year or 25-year options as well. The level term life insurance structure allows you to select coverage that expires when your financial responsibilities decrease.
Coverage Amount Considerations
Determining how much coverage you need requires honest assessment of your family's financial situation. Industry experts often recommend coverage equal to 10-12 times your annual income, though individual circumstances vary.
Factors influencing coverage amounts:
- Outstanding mortgage balance and remaining years
- Number of dependents and their ages
- Future education costs for children
- Income replacement needs for your spouse
- Final expenses and estate planning goals
- Existing savings and investments
Working with professionals who understand your complete financial picture ensures you're neither over-insured nor under-protected. For families in the Greensboro and High Point areas, local guidance tailored to North Carolina's cost of living provides more accurate recommendations.
Benefits of Choosing Level Life Insurance
The advantages of level life insurance extend beyond simple premium stability. This coverage type offers multiple benefits that make it attractive for diverse financial situations.
Budget Predictability and Planning
Knowing your exact insurance cost for the next 10, 20, or 30 years simplifies long-term financial planning considerably. You can confidently include this expense in retirement planning, college savings strategies, and other financial goals.
Families appreciate this certainty because it removes variables from monthly budgets. When you're managing mortgage payments, healthcare costs, and retirement savings, having one constant expense provides stability. This predictability proves especially valuable for those approaching retirement who want to lock in affordable rates before leaving employer-sponsored benefits.
Simplicity and Transparency
Level life insurance policies are relatively straightforward compared to more complex permanent insurance products. You pay a premium, maintain coverage for a set period, and your beneficiaries receive a predetermined death benefit if you pass away during that term.
This transparency appeals to people who value clear, understandable financial products. There are no hidden fees, no complicated cash value calculations, and no confusing policy statements. The advantages and disadvantages of level term life insurance become easy to evaluate because the structure remains simple.
Affordability for Comprehensive Protection
Level term life insurance typically costs significantly less than permanent policies with similar death benefits. This affordability allows families to purchase higher coverage amounts during the years they need protection most.
For example, a healthy 35-year-old might pay $40-60 monthly for $500,000 in 20-year level term coverage, whereas comparable whole life insurance could cost $400-500 monthly. This price difference enables families to allocate resources to other financial priorities while maintaining robust protection.
How Level Life Insurance Compares to Other Types
Understanding where level life insurance fits within the broader insurance landscape helps you make informed comparisons and choices.
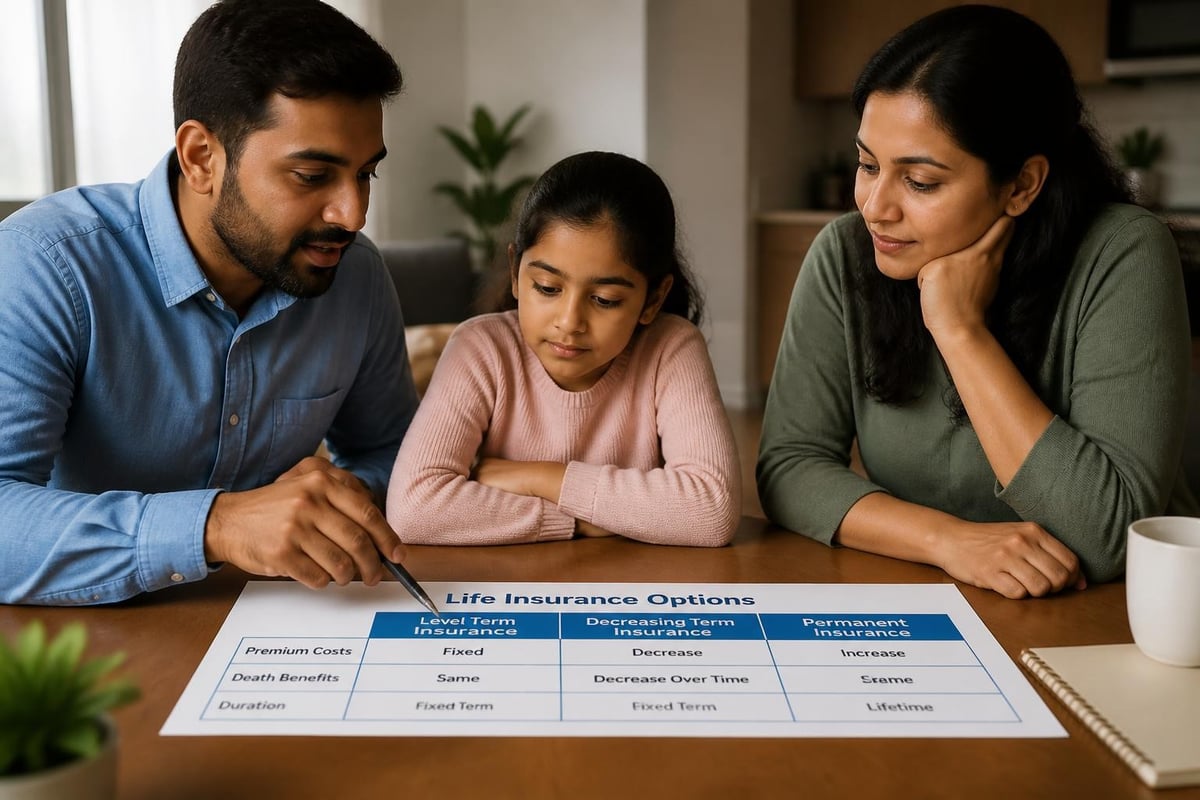
Level Term vs. Decreasing Term Insurance
While level life insurance maintains a constant death benefit, decreasing term insurance features a death benefit that reduces over time. The premium typically stays the same, but your coverage amount decreases annually.
Decreasing term insurance often aligns with declining debts like mortgages. As your loan balance decreases, so does your coverage. However, level term provides more flexibility because your needs might change unexpectedly, and having consistent coverage offers better protection.
Level Term vs. Permanent Insurance Options
Permanent insurance products like whole life insurance last your entire lifetime and include cash value accumulation. Level term insurance expires after the chosen term and builds no cash value.
Comparison of key features:
| Feature | Level Term Insurance | Permanent Insurance |
|---|---|---|
| Duration | Fixed term (10-30 years) | Lifetime coverage |
| Premium | Lower, stays level | Higher, may stay level or vary |
| Cash Value | None | Builds over time |
| Best For | Temporary needs, budget-conscious families | Lifelong protection, estate planning |
| Cost at Age 35 | $40-80/month for $500K | $400-600/month for $500K |
For families in Kernersville and Winston Salem balancing multiple financial priorities, level term often provides the most coverage for available budget. Understanding different types of life insurance helps you determine which structure best fits your situation.
Who Should Consider Level Life Insurance
Level life insurance serves specific financial situations particularly well. Recognizing whether your circumstances align with these scenarios helps determine if this coverage type suits your needs.
Young Families Building Financial Security
Parents with young children represent ideal candidates for level life insurance. The affordable premiums allow single-income or dual-income families to secure substantial coverage during the critical years when dependents rely entirely on parental income.
A 30-year term policy can provide protection from your child's birth through college graduation and beyond. This coverage ensures that if something happens to a parent, the surviving family members have financial resources for daily living expenses, education costs, and long-term security.
Homeowners Protecting Mortgage Obligations
Aligning your level life insurance term with your mortgage length creates a safety net for your family's housing security. If you have a 20-year mortgage, a 20-year level term policy ensures your family could pay off the home if you pass away unexpectedly.
This strategy provides peace of mind knowing your spouse and children won't face losing their home during an already difficult time. The death benefit can cover the outstanding mortgage balance, property taxes, maintenance costs, and other housing-related expenses.
Professionals with Income-Dependent Families
High earners whose families depend on their income should consider substantial level life insurance coverage. If your salary supports your household's lifestyle, education plans, and retirement savings, replacing that income becomes critical if you're no longer there.
Many professionals in the Triad Area choose level term policies equal to 10-15 times their annual income. This multiple ensures the death benefit, when invested conservatively, could generate replacement income for surviving family members through interest and gradual principal withdrawals.
Small Business Owners and Partners
Business owners often use level life insurance for multiple purposes: protecting business loans, funding buy-sell agreements, or ensuring business continuity if a key person dies. The predictable costs make business planning more accurate.
A 20-year term life insurance policy might align with a business loan term or the period until a partner reaches retirement age. This alignment ensures appropriate protection during critical business years.
Understanding What Level Life Insurance Covers and Excludes
Knowing exactly what your policy includes and excludes prevents surprises when your family needs to file a claim. Most level life insurance policies offer comprehensive coverage with specific limitations.
Standard Coverage Inclusions
Level life insurance pays the full death benefit for most causes of death, including accidents, illnesses, natural causes, and medical conditions. Once the policy is in force past any waiting periods, your beneficiaries receive payment regardless of how you die.
Common covered scenarios include:
- Death from cancer, heart disease, or other illnesses
- Accidental death from vehicle accidents, falls, or injuries
- Death from stroke, diabetes complications, or respiratory failure
- Natural causes and age-related decline
The key requirement is that death occurs during the active policy term. If you outlive your term, the policy simply expires with no payout. What level term life insurance covers extends to nearly all death scenarios once the policy activates.
Important Policy Exclusions
While coverage is broad, certain exclusions apply to most level life insurance policies. Understanding these limitations helps set accurate expectations.
The suicide clause typically prevents payment if death by suicide occurs within the first two years of the policy. After this contestability period, even suicide becomes a covered event. This clause protects insurers from adverse selection while providing eventual coverage.
Fraudulent application information represents another exclusion. If you misrepresent health conditions, dangerous hobbies, or other material facts during application, the insurer can deny claims or rescind the policy. Honest disclosure during application prevents these issues.
Some policies exclude death during commission of illegal activities or while under the influence of non-prescribed controlled substances. War and aviation exclusions may apply depending on your occupation and activities.
Costs and Factors Affecting Your Premium
Understanding what influences your level life insurance premium helps you anticipate costs and potentially qualify for better rates. Multiple factors contribute to your final price.
Age and Health Status Impact
Your age at application significantly affects premium costs. Insurers price policies based on life expectancy, so younger applicants pay substantially less than older applicants for identical coverage.
Sample monthly premiums for $500,000 20-year level term:
| Age | Excellent Health | Average Health | Below Average Health |
|---|---|---|---|
| 30 | $25-35 | $40-55 | $70-95 |
| 40 | $45-60 | $75-95 | $125-160 |
| 50 | $110-145 | $180-230 | $300-400 |
Your current health status matters tremendously. Conditions like high blood pressure, diabetes, obesity, or cholesterol issues increase premiums. However, well-managed conditions typically result in better rates than uncontrolled health problems. Factors that make life insurance more expensive include smoking, dangerous occupations, and risky hobbies.
Lifestyle and Occupation Considerations
Tobacco use represents one of the largest premium increases, often doubling or tripling costs compared to non-tobacco rates. Insurers typically define tobacco use as any cigarette, cigar, pipe, or nicotine product use within the past 12 months.
Dangerous occupations like construction work at heights, commercial fishing, logging, or law enforcement can increase premiums. High-risk hobbies including skydiving, scuba diving, rock climbing, or racing also affect rates.
Gender and Coverage Amount
Statistical life expectancy differences mean women typically pay slightly less than men for identical coverage. Women's longer average lifespan translates to lower risk for insurers.
The coverage amount you select directly impacts premium costs. Doubling your coverage approximately doubles your premium. However, purchasing one larger policy often costs less than buying multiple smaller policies due to administrative efficiencies.
Application Process and Medical Underwriting
Securing level life insurance involves several steps designed to assess your risk and determine appropriate pricing. Understanding this process helps you prepare and move through it efficiently.
Initial Application and Information Gathering
The application process begins with basic information including your age, address, occupation, income, and desired coverage amount. You'll answer detailed health questions about current conditions, medications, family medical history, and lifestyle factors.
Honesty during this stage is crucial. Misrepresentations can lead to claim denials years later when your family needs benefits most. If you have health concerns, discussing them upfront often leads to better outcomes than hiding information.
Medical Examination Requirements
Most level life insurance policies require a medical exam for coverage amounts above certain thresholds, typically $250,000 or higher. The exam usually occurs at your home or office at no cost to you.
Standard exam components include:
- Height and weight measurements
- Blood pressure and pulse readings
- Blood sample for cholesterol, glucose, and disease screening
- Urine sample for kidney function and substance screening
- Medical history review and lifestyle questions
Some insurers offer simplified or guaranteed issue policies without medical exams, though these typically cost more and offer lower coverage amounts. For healthy applicants, completing the exam usually results in better rates.
Underwriting Timeline and Approval
After your exam, the insurance company's underwriters review your application, medical results, and sometimes request records from your physicians. This process typically takes 4-6 weeks, though it can extend longer if medical records are delayed.
The underwriter assigns you a health classification (preferred plus, preferred, standard, or substandard) that determines your final premium. You'll receive an offer based on this classification, which you can accept, decline, or sometimes negotiate.
If you're reaching Medicare age and considering your broader insurance needs, connecting with resources about Medicare enrollment alongside your life insurance planning creates comprehensive protection.
Converting or Renewing Your Level Term Policy
What happens when your level term policy approaches expiration? Understanding your options before the term ends prevents coverage gaps and potentially saves money.
Conversion Privileges and Options
Many level life insurance policies include conversion privileges allowing you to convert term coverage to permanent insurance without new medical underwriting. This option proves valuable if your health has declined since you originally purchased the policy.
Conversion typically must occur before a specific age (often 65-70) or before a certain number of years remain on your term. The permanent policy premium reflects your age at conversion, which will be higher than your original term premium, but you won't face medical exam requirements or potential declines due to health conditions.
Renewal Considerations and Costs
Some policies offer renewal options when your term expires, allowing you to continue coverage for additional periods. However, renewal premiums reflect your current age and can increase dramatically, sometimes 5-10 times your original premium.
For example, if you paid $50 monthly for a 20-year term that's now expiring at age 55, renewal might cost $300-500 monthly for the same coverage. This steep increase makes renewal less attractive than purchasing a new policy if you're still in good health.
Assessing Continued Need for Coverage
As your term approaches expiration, evaluate whether you still need life insurance. If your mortgage is paid, children are financially independent, and you have adequate retirement savings, you might not require continued coverage.
However, if financial obligations remain or you want to leave an inheritance, exploring new term coverage or conversion to permanent insurance makes sense. Professional guidance helps you assess your situation objectively and make informed decisions without pressure.
Working with Insurance Professionals in North Carolina
Navigating life insurance options becomes significantly easier when you work with knowledgeable professionals who understand your local market and personal circumstances.
Benefits of Local Expertise
Insurance professionals familiar with the Triad Area understand regional factors affecting your coverage needs. Cost of living differences between Greensboro, High Point, Winston Salem, and Kernersville influence appropriate coverage amounts.
Local agents also understand North Carolina-specific regulations, available carriers in your area, and community resources that complement your insurance planning. This regional knowledge provides more accurate recommendations than generic online tools.
Educational Approach to Insurance Decisions
The best insurance professionals focus on education rather than sales pressure. You should feel empowered to ask questions, understand your options thoroughly, and make decisions at your own pace.
Understanding how different policy types work becomes easier when someone explains concepts in plain language tailored to your situation. Look for professionals who listen to your concerns, explain trade-offs clearly, and respect your timeline for decisions.
Personalized Coverage Recommendations
Your insurance needs differ from your neighbor's, even if you're similar ages with comparable incomes. Personalized recommendations consider your specific financial obligations, family structure, health status, risk tolerance, and long-term goals.
Quality professionals complete comprehensive needs analysis before recommending coverage amounts or policy types. They help you understand what level term life insurance provides in context of your complete financial picture, including retirement planning, existing savings, and other insurance coverages.
Ongoing Support and Service
Your relationship with an insurance professional shouldn't end when you sign the application. Quality service includes helping with beneficiary updates, answering questions during the policy term, assisting with claims if needed, and reviewing coverage as your life changes.
Having a consistent contact who knows your situation provides peace of mind. When questions arise about your policy, you can reach someone familiar with your coverage rather than navigating impersonal call centers.
Comparing Level Life Insurance Quotes Effectively
Shopping for level life insurance requires comparing more than just monthly premiums. Multiple factors influence the true value of different policy options.
Beyond the Monthly Premium
While premium cost matters significantly, especially for budget-conscious families, the lowest price doesn't always represent the best value. Consider the insurer's financial strength ratings, claims-paying history, and reputation for customer service.
Important comparison factors:
- Financial stability ratings from AM Best, Moody's, or Standard & Poor's
- Customer satisfaction scores and complaint ratios
- Conversion privileges and flexibility options
- Accelerated death benefit riders for terminal illness
- Waiver of premium for disability coverage
- Renewal terms and conditions
A slightly higher premium from a highly-rated, financially stable company often provides better long-term value than the absolute cheapest option from an unknown carrier.
Understanding Policy Features and Riders
Available riders enhance your base policy with additional benefits. Common riders include accelerated death benefits allowing you to access a portion of your death benefit if diagnosed with a terminal illness, typically defined as less than 12 months to live.
Waiver of premium riders continue your coverage without requiring premium payments if you become totally disabled. This protection ensures your policy remains in force even if you cannot work.
Children's term riders provide small amounts of coverage on your children for minimal additional cost. Some policies include these features automatically while others charge extra.
Reading the Fine Print
Policy details matter significantly when comparing options. Understanding what level term life insurance actually covers requires reviewing the full policy contract, not just the marketing materials.
Pay attention to contestability periods, suicide clauses, exclusions for specific activities or conditions, and exact definitions of terms like "total disability" for rider benefits. These details can significantly impact whether your family receives benefits when needed.
Timing Your Level Life Insurance Purchase
When you purchase life insurance affects both your premiums and your family's protection. Strategic timing can save money and provide better coverage.
Advantages of Buying While Young and Healthy
Every year you wait to purchase life insurance increases your premium due to age-based pricing. The difference between purchasing at age 30 versus 35 can amount to thousands of dollars over a 20-year term.
Additionally, health conditions can develop unexpectedly. Purchasing coverage while you're healthy ensures you qualify for preferred rates. Waiting until after a diabetes diagnosis, heart condition, or cancer screening can dramatically increase costs or even result in declined applications.
Life Events Triggering Coverage Needs
Certain life milestones create immediate insurance needs. Getting married, buying a home, having children, or starting a business all create financial obligations that life insurance can protect.
Common trigger events:
- Marriage and combining financial lives
- Home purchase with mortgage obligations
- Birth or adoption of children
- Career advancement with increased income
- Starting or purchasing a business
- Receiving significant debt or loans
Addressing insurance needs promptly after these events ensures protection exists before unexpected circumstances occur. Many people delay coverage decisions indefinitely, leaving families vulnerable during the gap.
Annual Review and Adjustment Opportunities
Even after purchasing level life insurance, reviewing your coverage annually ensures it remains appropriate. Life changes like additional children, increased mortgage size, or spouse career changes might warrant additional coverage.
While your existing level term policy maintains its original premium, you can purchase supplemental policies to increase total coverage. Conversely, if financial obligations decrease significantly, you might choose not to renew certain policies at term expiration.
Getting Started with Level Life Insurance Coverage
Taking action on life insurance protection doesn't require complicated processes or extensive time commitments. Understanding next steps helps you move forward confidently.
Determining Your Coverage Needs
Start by calculating your family's financial obligations and income replacement needs. Add outstanding mortgage balance, desired years of income replacement, children's education costs, final expenses, and any other debts.
Subtract existing life insurance through employers, savings, and other liquid assets. The remaining amount represents your coverage gap that level life insurance should fill.
Online calculators provide starting points, but personalized analysis with a professional ensures accuracy. Factors like Social Security survivor benefits, spouse earning potential, and available family support influence appropriate coverage amounts.
Gathering Required Information
Preparing for your insurance application streamlines the process. Collect information about your current medications, doses, and prescribing physicians. Note any diagnoses, surgeries, or hospitalizations from recent years with approximate dates.
Family medical history including parents' and siblings' major health conditions helps underwriters assess your risk. Information about your occupation, income, and existing life insurance policies completes the basic application requirements.
Connecting with Knowledgeable Professionals
When you're ready to explore your options, connecting with experienced insurance professionals who prioritize education and personalized service makes the process significantly easier. In the Greensboro, Kernersville, High Point, and Winston Salem areas, you can reach out to discuss your specific situation and receive clear guidance without pressure.
Contact Moser Insurance Group Inc at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com to start a conversation about protecting your family's financial future. Professional support helps you understand your options thoroughly and make confident decisions that align with your unique circumstances and goals.
Level life insurance provides straightforward, affordable protection that gives families peace of mind through predictable premiums and consistent death benefits. Whether you're protecting a young family, covering mortgage obligations, or ensuring income replacement, understanding how this coverage works empowers you to make informed decisions. Moser Insurance Group Inc helps individuals and families throughout the Triad Area navigate life insurance options with clear explanations and personalized guidance tailored to your specific needs. Ready to explore how level life insurance fits into your financial protection plan? Contact Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your options without pressure or obligation.
Recent Comments