

Medicare beneficiaries face an important decision when choosing their healthcare coverage. While Original Medicare provides essential hospital and medical insurance, medicare advantage health plans offer an alternative approach that bundles services together through private insurance companies. These plans continue to grow in popularity across North Carolina, particularly in the Triad Area, Greensboro, Kernersville, High Point, and Winston Salem, where residents appreciate the convenience and additional benefits these options provide. Understanding how these plans work, what they cover, and whether they align with your healthcare needs is crucial for making an informed decision about your Medicare coverage.
Understanding How Medicare Advantage Health Plans Work
Medicare Advantage health plans, also known as Medicare Part C, represent a comprehensive alternative to Original Medicare. These plans are offered by private insurance companies approved by Medicare and must cover everything that Original Medicare Parts A and B cover. However, they typically include additional benefits that Original Medicare doesn't provide.
The fundamental structure includes:
- Coverage for hospital care (Part A services)
- Medical services and doctor visits (Part B services)
- Often prescription drug coverage (Part D)
- Additional benefits like dental, vision, and hearing
- Fitness programs and wellness services
When you enroll in medicare advantage health plans, you're still in Medicare, but you receive your benefits through the private insurance company rather than directly through the federal Medicare program. The insurance company receives a fixed payment from Medicare each month to manage your care, regardless of how many services you actually use.
Key Differences From Original Medicare
The Medicare coverage choices between Original Medicare and Medicare Advantage create distinct experiences for beneficiaries. Original Medicare allows you to see any doctor or hospital that accepts Medicare nationwide without needing referrals. Medicare advantage health plans typically require you to use a network of doctors and hospitals, similar to employer-sponsored health insurance.
| Feature | Original Medicare | Medicare Advantage |
|---|---|---|
| Provider Network | Any Medicare provider nationwide | Specific network (HMO/PPO) |
| Additional Benefits | Limited to Parts A & B | Often includes dental, vision, hearing |
| Prescription Coverage | Requires separate Part D plan | Usually included |
| Out-of-Pocket Maximum | No limit | Annual cap protects you |
| Referrals Required | No | Often yes (especially HMOs) |
Most medicare advantage health plans include an out-of-pocket maximum, which Original Medicare lacks. This means once you reach a certain amount in copays and coinsurance for the year, the plan covers all remaining costs at 100 percent. This financial protection can be particularly valuable for individuals with chronic conditions or unexpected health issues.
Types of Medicare Advantage Health Plans Available
The marketplace offers several types of medicare advantage health plans, each with different rules about how you access care and what you pay. Understanding these distinctions helps you select the option that best fits your lifestyle and healthcare preferences.
Health Maintenance Organization (HMO) Plans
HMO plans are the most common type of medicare advantage health plans in areas like Greensboro and Kernersville. These plans require you to choose a primary care physician who coordinates all your care and provides referrals to specialists within the network.
HMO characteristics include:
- Lower monthly premiums compared to other plan types
- No coverage for out-of-network care except emergencies
- Primary care physician acts as your healthcare coordinator
- Referrals needed for specialist visits
- Strong focus on preventive care and wellness
Preferred Provider Organization (PPO) Plans
PPO plans offer more flexibility than HMOs but typically cost more in monthly premiums. You can see any doctor who accepts Medicare, though you'll pay less when using in-network providers. These medicare advantage health plans don't require referrals to see specialists.
Special Needs Plans (SNPs)
Special Needs Plans are medicare advantage health plans designed for people with specific diseases or characteristics. For example, Dual Eligible Special Needs Plans (D-SNPs) serve individuals who qualify for both Medicare and Medicaid. Chronic Condition SNPs focus on beneficiaries with conditions like diabetes, heart failure, or cancer.
Private Fee-for-Service (PFFS) Plans
These less common medicare advantage health plans allow you to see any Medicare-approved doctor or hospital that accepts the plan's terms and conditions. The plan determines how much it pays providers and how much you pay when you receive care.
Coverage and Benefits Included in Medicare Advantage Health Plans
Medicare advantage health plans must cover all services that Original Medicare covers, but most go significantly beyond those basic requirements. According to recent Medicare Advantage plan offerings, the majority of plans now include prescription drug coverage and supplemental benefits.
Standard Medical Coverage
All medicare advantage health plans provide comprehensive hospital and medical coverage. This includes inpatient hospital stays, skilled nursing facility care, hospice care, doctor visits, preventive services, and durable medical equipment. The plans must follow Medicare's coverage rules but can charge different copayments and coinsurance amounts than Original Medicare.
Core services covered:
- Hospital stays and surgeries
- Primary care and specialist visits
- Laboratory tests and diagnostic services
- Preventive screenings and vaccines
- Mental health services
- Physical and occupational therapy
Prescription Drug Coverage
Most medicare advantage health plans include Part D prescription drug coverage integrated into the plan. This eliminates the need to purchase a separate Part D plan. Each plan has its own formulary (list of covered drugs) and may require prior authorization for certain medications or encourage generic alternatives through tiered copayments.
Supplemental Benefits Beyond Original Medicare
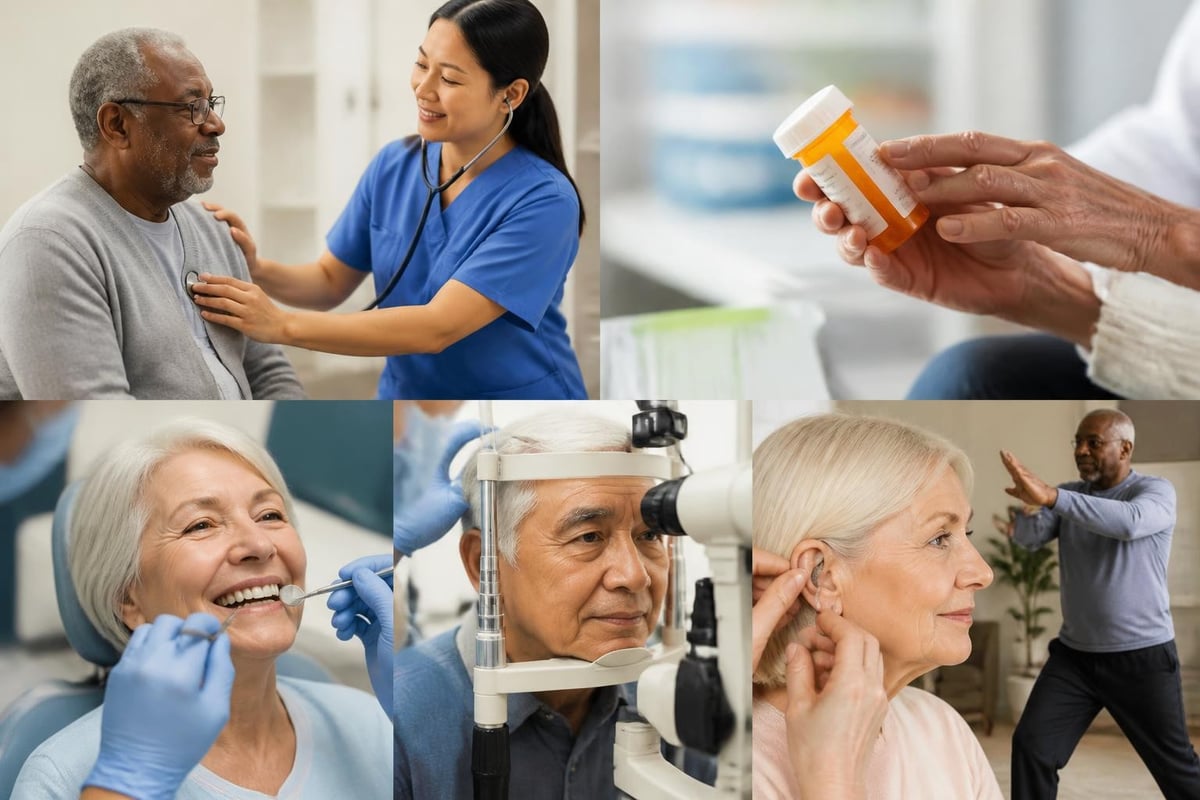
Medicare advantage health plans differentiate themselves through additional benefits not covered by Original Medicare. These supplemental benefits address common healthcare needs among seniors and contribute to overall wellness. Many plans serving High Point and Winston Salem have expanded these offerings in 2026.
| Benefit Type | Common Coverage | Typical Value |
|---|---|---|
| Dental | Cleanings, exams, sometimes major work | $1,000-$3,000 annually |
| Vision | Eye exams, glasses or contacts | $150-$300 allowance |
| Hearing | Exams and hearing aids | $500-$2,000 per aid |
| Fitness | Gym memberships, fitness programs | $0-$30 monthly value |
| Over-the-Counter | Allowance for health products | $25-$100 quarterly |
| Transportation | Rides to medical appointments | 12-48 trips annually |
Some medicare advantage health plans have begun offering non-medical benefits like meal delivery after hospital discharge, in-home support services, and even benefits that address social determinants of health such as utility assistance or home safety modifications.
Costs Associated With Medicare Advantage Health Plans
Understanding the complete cost structure of medicare advantage health plans requires looking beyond the monthly premium. While some plans advertise zero-dollar premiums, you'll still pay other costs when you receive care. The official Medicare health plans page provides tools to compare costs across available options.
Premium Payments
The monthly premium for medicare advantage health plans varies widely based on the plan type, coverage level, and your geographic area. In the Triad Area, premiums for 2026 range from zero dollars to over $200 monthly. Remember that you must continue paying your Medicare Part B premium (currently $185 in 2026) even if your Medicare Advantage plan has a zero-dollar premium.
Deductibles and Cost-Sharing
Medicare advantage health plans use different cost-sharing structures:
- Annual deductibles: Some plans require you to pay a deductible before coverage begins, while others have zero deductibles
- Copayments: Fixed dollar amounts for specific services (such as $20 for primary care visits)
- Coinsurance: Percentage of the cost you pay (such as 20 percent of the Medicare-approved amount)
Out-of-Pocket Maximums
Every Medicare Advantage plan includes an annual out-of-pocket maximum, which caps your total spending on covered services. For 2026, the maximum allowable out-of-pocket limit is $8,850 for in-network services. Once you reach this amount, the plan pays 100 percent of covered services for the remainder of the year.
This protection differs significantly from Original Medicare, which has no out-of-pocket maximum. For those considering Medicare Supplement Plans as an alternative, it's worth noting that Medigap plans work differently by covering the gaps in Original Medicare rather than replacing it entirely.
Enrollment Periods and Eligibility Requirements
Medicare advantage health plans follow specific enrollment periods established by Medicare. Missing these windows can delay your coverage or result in penalties, so understanding the timeline is essential for residents throughout Greensboro, Kernersville, and surrounding communities.
Initial Enrollment Period
Your Initial Enrollment Period occurs when you first become eligible for Medicare, typically the seven-month period around your 65th birthday. During this time, you can choose between Original Medicare or medicare advantage health plans without answering health questions or facing coverage denials.
The timeline includes:
- Three months before your birthday month
- Your birthday month
- Three months after your birthday month
Annual Enrollment Period (AEP)
The Annual Enrollment Period runs from October 15 through December 7 each year. During AEP, anyone with Medicare can switch from Original Medicare to medicare advantage health plans, change from one Medicare Advantage plan to another, or return to Original Medicare. Changes made during this period take effect January 1 of the following year.
Medicare Advantage Open Enrollment Period
From January 1 through March 31, people already enrolled in medicare advantage health plans have an additional opportunity to make changes. During this period, you can switch to a different Medicare Advantage plan or drop your Medicare Advantage plan and return to Original Medicare. You can make only one change during this period.
Special Enrollment Periods
Certain life events trigger Special Enrollment Periods that allow you to change your medicare advantage health plans outside the standard enrollment windows. These qualifying events include moving to a new service area, losing other credible coverage, moving into or out of a nursing home, or qualifying for both Medicare and Medicaid.
Choosing the Right Medicare Advantage Plan for Your Needs
Selecting among medicare advantage health plans requires careful evaluation of your healthcare needs, preferred doctors, prescription medications, and budget. The Medicare Advantage rates and statistics published by CMS provide valuable data for comparing plans in your area.
Evaluating Your Healthcare Needs
Start by assessing your current and anticipated healthcare needs. Consider how often you visit doctors, what specialists you see, what medications you take regularly, and whether you have upcoming procedures planned. People with chronic conditions requiring frequent specialist visits may prioritize different features than those in excellent health who primarily need preventive care.
Questions to ask yourself:
- How often do I visit my primary care doctor?
- Do I see specialists regularly?
- What prescription medications do I take?
- Do I prefer a specific hospital or healthcare system?
- How important are extra benefits like dental and vision?
- Am I comfortable with network restrictions?
Checking Provider Networks
Before enrolling in medicare advantage health plans, verify that your current doctors and preferred hospitals participate in the plan's network. In High Point and Winston Salem, major healthcare systems may have different relationships with various Medicare Advantage carriers. Contact your doctors' offices directly to confirm they accept the specific plan you're considering, not just that they accept "Medicare Advantage" in general.
Comparing Prescription Drug Coverage
If you take regular medications, carefully review each plan's formulary. Medicare advantage health plans can change their formularies monthly, but they must notify you before removing a drug you're currently taking. Check whether your medications are covered, what tier they're in, whether they require prior authorization or step therapy, and what your copayments will be.
Understanding Plan Ratings
Medicare uses a five-star quality rating system to evaluate medicare advantage health plans based on customer service, member complaints, healthcare quality, and member satisfaction. While ratings provide useful information, a lower-rated plan that includes your doctors and medications may serve you better than a highly-rated plan with a network that doesn't fit your needs.
Network Restrictions and How They Affect Your Care
Network design represents one of the most significant differences between medicare advantage health plans and Original Medicare. Understanding these restrictions helps you avoid unexpected costs and access issues when you need care in Kernersville, Greensboro, or while traveling.
In-Network vs. Out-of-Network Care
HMO plans typically provide no coverage for out-of-network care except in emergencies. If you see a doctor outside the network, you'll be responsible for the entire bill. PPO plans offer more flexibility, covering out-of-network care at a higher cost-sharing rate. You'll pay lower copayments and coinsurance when you stay in-network but retain the option to go out-of-network when needed.
Geographic Service Areas
Medicare advantage health plans operate within specific service areas, usually defined by county. If you live in the Triad Area but spend significant time elsewhere (such as winter months in Florida), verify whether your plan provides coverage in both locations. Some plans offer national PPO networks, while others limit coverage to emergencies when you're outside the service area.
Referral Requirements and Prior Authorizations
Many medicare advantage health plans require referrals from your primary care physician before seeing specialists. Additionally, certain services, procedures, or medications may require prior authorization from the insurance company before coverage applies. Recent discussions about reducing prior authorizations show that some carriers are working to streamline these processes for 2026.
Common Misconceptions About Medicare Advantage Health Plans
Several misunderstandings about medicare advantage health plans can lead to confusion or poor decision-making. Clarifying these misconceptions helps beneficiaries make informed choices based on accurate information.
"Medicare Advantage Is Free"
While some medicare advantage health plans have zero-dollar premiums, they're not free. You continue paying your Part B premium and face cost-sharing when you receive care. Plans with zero premiums often have higher copayments, coinsurance, or deductibles than plans with monthly premiums.
"You Can't Switch Back to Original Medicare"
You can return to Original Medicare during specific enrollment periods. However, if you try to purchase a Medigap policy after your Initial Enrollment Period, insurance companies in most states can deny coverage or charge higher premiums based on your health status. This makes the decision to leave Original Medicare initially more significant than the decision to return later.
"All Plans Cover the Same Things"
While all medicare advantage health plans must cover what Original Medicare covers, they differ significantly in additional benefits, cost-sharing structures, formularies, and networks. Two plans in the same zip code can provide vastly different experiences and costs depending on your specific healthcare needs.
"Medicare Advantage Always Saves Money"
Whether medicare advantage health plans save money depends on your individual circumstances. For healthy individuals who rarely need care, the low or zero premiums can result in savings. For people with significant healthcare needs who frequently reach their out-of-pocket maximum, the total annual costs might exceed what they would pay with Original Medicare plus a Medigap plan and Part D coverage.
How Medicare Advantage Plans Are Regulated and Protected
Medicare advantage health plans operate under strict federal regulations designed to protect beneficiaries. The Centers for Medicare & Medicaid Services oversees these plans, ensuring they meet quality standards and follow Medicare rules.
Annual Contract Renewals
Every year, Medicare Advantage plans must renew their contracts with CMS. Plans can exit the market, change their service areas, or modify their benefits subject to CMS approval. If your plan leaves the market or your county, you receive a Special Enrollment Period to select new coverage.
Coverage Appeals and Grievances
If medicare advantage health plans deny coverage for a service you believe should be covered, you have the right to appeal. The appeals process includes multiple levels, starting with the plan's internal review and potentially proceeding to independent review by Medicare if necessary. Plans must provide written denial notices explaining your appeal rights.
Quality Oversight
CMS monitors medicare advantage health plans through quality measures including preventive care rates, management of chronic conditions, customer service performance, and member satisfaction surveys. Plans that consistently underperform may face sanctions or contract termination.
Making the Transition to Medicare Advantage
Once you've selected among medicare advantage health plans, understanding the transition process ensures smooth coverage implementation. Working with an experienced advisor can help navigate enrollment complexities, especially for residents new to Medicare in Winston Salem, High Point, or Greensboro.
Enrollment Process Steps
- Verify eligibility: Confirm you have Medicare Parts A and B
- Compare available plans: Review options in your service area
- Gather information: Collect details about your doctors, medications, and healthcare needs
- Complete enrollment: Submit your application during an eligible enrollment period
- Receive confirmation: Get your membership materials and ID card
What Happens to Your Current Coverage
When you enroll in medicare advantage health plans, your Original Medicare coverage doesn't disappear but becomes secondary. If you have a Medigap policy, you should consider canceling it since it won't work with Medicare Advantage and you'll be paying for redundant coverage. If you have a standalone Part D plan, it will automatically terminate when your Medicare Advantage plan with drug coverage begins.
Effective Dates and Waiting Periods
Coverage typically begins on the first day of the month following your enrollment. If you enroll during the Annual Enrollment Period (October 15 – December 7), your coverage starts January 1. There are no waiting periods for pre-existing conditions with medicare advantage health plans.
Regional Considerations for the Triad Area
Medicare advantage health plans available in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, reflect the local healthcare landscape. Residents benefit from multiple carrier options and competitive plan designs tailored to North Carolina beneficiaries.
Local Provider Networks
Major healthcare systems in the region partner with various Medicare Advantage carriers. Understanding which plans include your preferred providers helps narrow your options. For instance, if you prefer receiving care at a specific hospital system in Greensboro, verify which medicare advantage health plans include that facility in their network.
Plan Availability by County
Different counties within the Triad Area may have varying plan availability. While some carriers offer plans across multiple counties, others focus on specific geographic areas. When comparing options, ensure you're reviewing plans actually available in your specific county of residence.
Community Resources and Support
Local resources can help you understand medicare advantage health plans available in your area. Independent insurance advisors familiar with the Triad Area, like those at Moser Insurance Group Inc, provide personalized guidance based on your specific situation. You can reach out at 336-862-1763 or moserinsurancegroup@gmail.com for assistance with your Medicare questions. For detailed information about insurance and Medicare options specific to North Carolina residents, visiting moserinsurancegroup.com offers valuable insights.
Future Trends in Medicare Advantage
Medicare advantage health plans continue evolving to address changing healthcare needs and delivery models. Understanding emerging trends helps beneficiaries anticipate how their coverage might change in coming years.
Expanded Supplemental Benefits
Plans increasingly offer benefits that address social determinants of health, including nutrition support, housing assistance, and caregiver support. These non-medical benefits recognize that healthcare extends beyond doctor visits and medications to include factors that influence overall wellbeing.
Technology Integration
Telehealth services, remote monitoring, and digital health tools are becoming standard features of medicare advantage health plans. These technologies increase access to care, particularly for rural residents in parts of the Triad Area, and allow for more proactive management of chronic conditions.
Value-Based Care Models
Medicare advantage health plans increasingly emphasize value-based care arrangements with providers, rewarding quality outcomes rather than volume of services. These models align incentives toward keeping beneficiaries healthy rather than simply treating illness after it occurs.
Policy and Regulatory Changes
Ongoing policy discussions about Medicare's future may affect medicare advantage health plans. Beneficiaries should stay informed about potential regulatory changes that could impact their coverage options, costs, or benefits. Resources like the American Hospital Association’s Medicare Advantage updates provide insights into policy developments affecting these plans.
Navigating medicare advantage health plans requires careful consideration of your healthcare needs, budget, and preferences, but you don't have to make these decisions alone. Understanding the coverage options, costs, network structures, and enrollment requirements empowers you to select a plan that truly supports your health and financial wellbeing. Moser Insurance Group Inc specializes in helping individuals and families throughout the Triad Area understand their Medicare options without pressure or confusion. Whether you're approaching 65, currently enrolled in Original Medicare, or reconsidering your existing Medicare Advantage plan, our team provides clear guidance tailored to your unique situation. Contact us at 336-862-1763 or moserinsurancegroup@gmail.com to discuss which medicare advantage health plans might work best for you.
Recent Comments