

Medicare HMO plans represent one of the most popular ways to receive Medicare benefits, offering a structured approach to healthcare that emphasizes coordinated care and cost predictability. As a type of Medicare Advantage Plan, these health maintenance organizations provide all Medicare Part A and Part B benefits while often including additional coverage like prescription drugs, dental, and vision. Understanding how medicare hmo plans function, their benefits, limitations, and costs can help you make an informed decision about your healthcare coverage. For residents in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, selecting the right plan requires careful consideration of local provider networks and personal healthcare needs.
How Medicare HMO Plans Work
Medicare HMO plans operate through a structured network of healthcare providers who have contracted with the insurance company. When you enroll in an HMO, you select a primary care physician (PCP) from the plan's network who becomes your main point of contact for all healthcare needs.
Your PCP coordinates your care, manages routine checkups, and provides referrals when you need to see specialists. This gatekeeper model ensures that all your healthcare services are coordinated through a central provider who understands your complete medical history.
Key operational features include:
- Primary care physician requirement for all non-emergency care
- Referrals needed before seeing specialists
- Coverage limited to network providers (except emergencies)
- Care coordination managed by your PCP
- Prior authorization required for certain services
The network structure means you must receive care from providers who have agreements with your HMO plan. Going outside the network typically results in no coverage unless you face a medical emergency. This differs significantly from other plan types that may offer partial out-of-network benefits.
Coverage Requirements and Restrictions
Medicare hmo plans must cover all services that Original Medicare covers, but they deliver these benefits through their specific network. The plan establishes contracts with hospitals, doctors, specialists, and other healthcare providers in specific geographic areas.
Geographic limitations matter significantly. Most HMOs provide coverage only within their service area, which typically encompasses specific counties or regions. If you spend significant time in multiple locations throughout the year, you need to verify coverage availability in each area.
| Coverage Aspect | HMO Requirement | Flexibility Level |
|---|---|---|
| Primary Care Physician | Required selection | Must choose from network |
| Specialist Referrals | PCP referral needed | Network specialists only |
| Service Area | Geographic restriction | Emergency coverage only outside area |
| Prior Authorization | Often required | Varies by service type |
Emergency and urgently needed care represent the primary exceptions to network restrictions. If you experience a medical emergency anywhere in the United States, your medicare hmo plan provides coverage. Similarly, if you urgently need care while traveling outside your service area, the plan typically covers these services.
Cost Structure of Medicare HMO Plans
Understanding the financial aspects of medicare hmo plans helps you budget for healthcare expenses and compare options effectively. These plans feature multiple cost components that work together to determine your total healthcare spending.
Monthly premiums represent your regular payment to maintain coverage. Many HMOs charge zero or low premiums beyond the standard Medicare Part B premium. Some plans in competitive markets offer $0 premium options with comprehensive benefits, while others charge additional monthly amounts for enhanced coverage.
Out-of-Pocket Expenses
Beyond premiums, you encounter costs when receiving healthcare services. Medicare hmo plans structure these expenses through copayments, coinsurance, and deductibles that vary significantly between plans.
- Copayments: Fixed dollar amounts for specific services (e.g., $15 for primary care visits, $40 for specialists)
- Coinsurance: Percentage of the service cost you pay (e.g., 20% of hospital costs)
- Deductibles: Amount you pay before plan coverage begins for certain services
- Maximum out-of-pocket limit: Annual cap on your cost-sharing expenses
The maximum out-of-pocket protection provides crucial financial security. Once you reach this limit through copayments, coinsurance, and deductibles, your plan covers 100% of covered services for the remainder of the year. In 2026, these limits cannot exceed amounts set by Medicare, though plans may set lower maximums.
Medicare Advantage Plans, including HMOs, often include prescription drug coverage as part of the package. This integrated approach can simplify your healthcare coverage compared to managing separate Medicare Part D enrollment.
Benefits Beyond Original Medicare
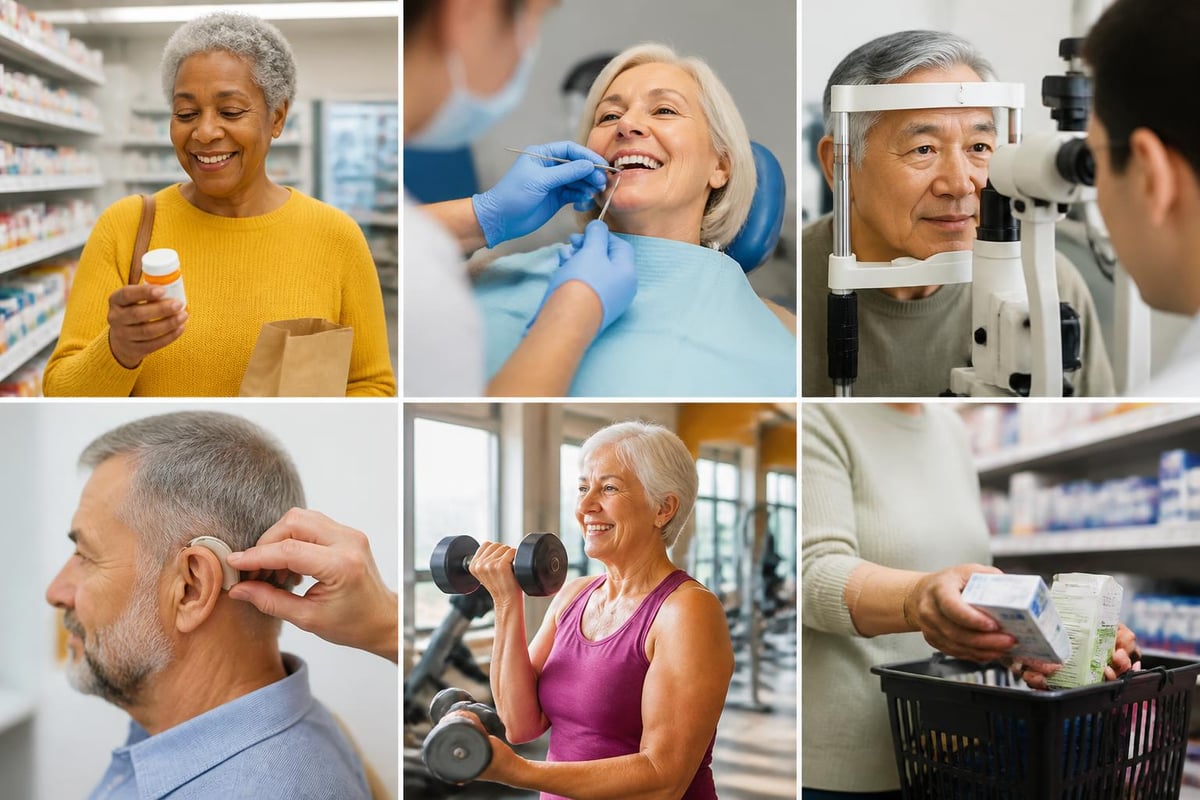
Medicare hmo plans frequently offer supplemental benefits that Original Medicare doesn't cover. These additional services represent significant value propositions that make HMOs attractive to many beneficiaries.
Common enhanced benefits include:
- Prescription drug coverage integrated into the plan
- Dental services including cleanings, X-rays, and sometimes major work
- Vision care with routine eye exams and eyewear allowances
- Hearing services including exams and hearing aid coverage
- Fitness programs like gym memberships or SilverSneakers
- Over-the-counter allowances for health-related products
Some plans specifically targeting residents in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, tailor their supplemental benefits to local needs and preferences. For example, certain plans may partner with regional fitness centers or offer transportation services to medical appointments.
Wellness and Preventive Services
Medicare hmo plans emphasize preventive care to maintain member health and reduce long-term costs. Most plans cover preventive services at no cost, including annual wellness visits, screenings, and vaccinations.
The care coordination model inherent to HMOs supports proactive health management. Your primary care physician tracks your preventive care schedule, sends reminders for necessary screenings, and monitors chronic conditions before they escalate into serious health issues.
Choosing the Right Medicare HMO Plan
Selecting among available medicare hmo plans requires evaluating multiple factors that align with your personal circumstances, health status, and financial situation. The decision process becomes more manageable when you break it into specific considerations.
Provider Network Evaluation
Check whether your preferred doctors, specialists, and hospitals participate in the HMO network. Changing providers can disrupt established care relationships and require building new rapport with unfamiliar physicians.
Steps to verify network participation:
- Request a provider directory from the plan
- Call your current doctors to confirm their participation
- Verify hospital affiliations for your preferred medical centers
- Check specialist availability for any ongoing treatment needs
- Review network size and accessibility in your area
Residents in the Triad Area should specifically verify that providers in Greensboro, Kernersville, High Point, and Winston Salem participate in any plan under consideration. Network coverage can vary significantly between neighboring communities.
Prescription Drug Coverage Analysis
If the medicare hmo plan includes Part D prescription drug coverage, review the formulary to ensure your medications are covered. Plans organize drugs into tiers, with different cost-sharing for each tier.
| Tier | Drug Type | Typical Cost-Sharing |
|---|---|---|
| Tier 1 | Generic drugs | Lowest copay |
| Tier 2 | Preferred brand drugs | Moderate copay |
| Tier 3 | Non-preferred brand drugs | Higher copay |
| Tier 4 | Specialty drugs | Highest cost-sharing (often coinsurance) |
Contact the plan or use their online tools to verify your specific medications appear on the formulary and check required cost-sharing. Some drugs require prior authorization or step therapy, which your doctor must address before the plan covers the medication.
Comparing HMO Plans with Other Medicare Options
Understanding how medicare hmo plans differ from other available options helps you determine which approach best serves your needs. Medicare offers several plan types, each with distinct characteristics.
Original Medicare (Parts A and B) provides broad provider access without network restrictions. You can see any doctor or specialist who accepts Medicare without needing referrals. However, Original Medicare doesn't include prescription drug coverage or caps on out-of-pocket expenses.
PPO Medicare Advantage Plans offer more flexibility than HMOs. While they maintain provider networks, PPOs allow you to see out-of-network providers at higher cost-sharing. You don't need a primary care physician or referrals for specialists.
Medicare Supplement Plans (Medigap) work alongside Original Medicare to cover gaps like deductibles and coinsurance. These standardized plans provide predictable coverage but require separate Part D enrollment for prescription drugs.
Many people exploring Medicare Supplement Plans alongside Medicare Advantage options benefit from understanding the fundamental differences in how these plans deliver benefits and manage costs.
When HMOs Make the Most Sense
Medicare hmo plans work particularly well for beneficiaries who:
- Prefer coordinated care through a primary care physician
- Value low or zero premiums
- Want comprehensive benefits including prescription drugs
- Don't mind network restrictions
- Primarily receive care in a specific geographic area
- Appreciate predictable copayments rather than percentage-based coinsurance
Conversely, HMOs may not suit those who travel frequently, want unlimited provider choice, or prefer managing their own specialist referrals without PCP involvement.
Enrollment Periods and Plan Changes
Timing matters significantly when enrolling in or changing medicare hmo plans. Medicare establishes specific periods when you can make coverage decisions, with limited exceptions outside these windows.
Initial Enrollment Period occurs when you first become eligible for Medicare, typically the seven-month period surrounding your 65th birthday. During this time, you can choose Original Medicare or enroll in a Medicare Advantage Plan like an HMO.
The Annual Enrollment Period runs from October 15 through December 7 each year. During these weeks, any Medicare beneficiary can switch from Original Medicare to Medicare Advantage, change between different Advantage plans, or return to Original Medicare. Changes take effect January 1 of the following year.
Special Enrollment Periods
Certain qualifying events trigger Special Enrollment Periods that allow plan changes outside the standard windows:
- Moving outside your plan's service area
- Losing current coverage
- Qualifying for Extra Help with prescription costs
- Entering or leaving a skilled nursing facility
- Institutional equivalent care status changes
The Medicare Advantage Open Enrollment Period from January 1 through March 31 allows current Medicare Advantage enrollees to switch to different Advantage plans or return to Original Medicare once during this period.
Network Adequacy and Access to Care
The quality of an HMO network directly impacts your healthcare experience. Beyond simply checking whether your doctor participates, evaluate the network's overall adequacy for your anticipated needs.
Specialist availability matters particularly if you manage chronic conditions requiring ongoing specialty care. Research whether the network includes sufficient specialists in relevant fields located reasonably close to your home in the Triad Area.
Appointment availability represents another crucial factor. Some networks include many providers but face capacity constraints that result in long wait times for appointments. When evaluating plans, consider asking:
- How quickly can new patients schedule appointments?
- What is typical wait time for specialist referrals?
- Are providers accepting new Medicare Advantage patients?
- Do network providers maintain convenient office hours?
- Are telehealth options available through network providers?
Hospital quality within the network deserves careful attention, especially for beneficiaries with conditions that may require inpatient care. Review hospital ratings, specialty services, and proximity to your residence.
Star Ratings and Plan Quality
Medicare assigns Star Ratings to Medicare Advantage Plans based on quality and performance measures. These ratings, ranging from one to five stars, provide standardized quality comparisons across plans.
Five-star Medicare Advantage plans represent the highest-rated options and may offer Special Enrollment Periods allowing enrollment outside standard windows. The rating system evaluates plans across five categories:
- Staying healthy: Screenings, tests, and vaccines
- Managing chronic conditions: How well the plan helps members manage ongoing health issues
- Member experience: Customer service and member satisfaction
- Member complaints and plan performance: Appeals, complaints, and disenrollment rates
- Health plan customer service: Phone system performance and responsiveness
Higher-rated plans often demonstrate better care coordination, stronger preventive services, and superior member satisfaction. When comparing medicare hmo plans, review Star Ratings alongside other factors like network adequacy and cost structure.
Medical Management and Prior Authorization
Medicare hmo plans implement medical management processes to ensure appropriate care utilization and control costs. Understanding these processes helps you navigate the system effectively and avoid coverage denials.
Prior authorization requirements mean your doctor must receive plan approval before providing certain services, medications, or procedures. The plan reviews medical necessity based on clinical guidelines and your specific situation.
Services commonly requiring prior authorization include:
- Advanced imaging (MRI, CT scans, PET scans)
- Specialty medications
- Inpatient hospital stays
- Durable medical equipment
- Home health services
- Skilled nursing facility care
Your healthcare providers typically handle prior authorization requests, but you should understand when authorization is needed and allow sufficient time before scheduled services. Denied authorizations can be appealed through the plan's formal process.
Step therapy requirements for certain medications require trying lower-cost or preferred drugs before the plan covers more expensive alternatives. If initial medications prove ineffective or cause adverse reactions, your doctor can document medical necessity for alternative treatments.
Regional Considerations for the Triad Area
Residents of Greensboro, Kernersville, High Point, and Winston Salem have access to multiple medicare hmo plans with varying provider networks and benefits. Local healthcare infrastructure influences plan design and network composition in the Triad Area.
Major healthcare systems in the region contract with different plans, affecting network breadth and depth. Research which plans include your preferred healthcare systems and physician groups. Some plans maintain robust networks across all four cities, while others concentrate providers in specific communities.
Geographic factors within the Triad Area can impact your experience:
- Travel distances between your residence and network providers
- Traffic patterns affecting appointment accessibility
- Provider concentration in urban versus suburban areas
- Hospital locations relative to your home
If you live in one Triad Area city but frequently visit family or maintain a second residence in another, verify that your chosen plan provides adequate coverage across your routine locations.
For personalized guidance on comparing plans available in your specific zip code, contact Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com. Local expertise helps identify plans with strong networks in your immediate area and explains nuances of regional coverage.
Care Coordination Benefits
The structured care coordination model distinguishes medicare hmo plans from other Medicare options. While some perceive the referral requirement as restrictive, it offers distinct advantages for comprehensive health management.
Your primary care physician maintains a complete view of your health status, medications, treatments, and specialist consultations. This centralized knowledge helps prevent:
- Duplicate tests and procedures
- Drug interactions from multiple prescribers
- Fragmented care from uncoordinated specialists
- Conflicting treatment recommendations
- Information gaps between providers
Electronic health records within integrated health systems enhance coordination further. When your PCP, specialists, and hospitals share interconnected record systems, all providers access consistent information about your health history, active medications, and treatment plans.
Utilization Management and Coverage Decisions
Medicare hmo plans apply utilization management techniques to promote evidence-based care and appropriate service utilization. These programs review patterns of care, identify opportunities for improved outcomes, and ensure services align with medical guidelines.
Coverage determinations occur when you request specific services or treatments. The plan evaluates whether the service is medically necessary, covered under your benefits, and follows appropriate clinical pathways. Complex or high-cost services receive more intensive review.
Understanding your appeal rights is essential. If the plan denies coverage for a service your doctor recommends, you can:
- Request a standard reconsideration within 60 days of the denial
- Pursue an expedited appeal if standard timeframes could seriously jeopardize your health
- Escalate to an independent review organization if the plan upholds the denial
- Continue through additional appeal levels up to Administrative Law Judge hearings
Your doctor can assist with appeals by providing clinical documentation supporting medical necessity. Don't abandon needed care due to an initial denial without pursuing available appeal options.
Integration with Other Coverage
Some beneficiaries maintain other insurance coverage alongside medicare hmo plans. Understanding how different coverage types coordinate is essential for maximizing benefits and avoiding unexpected costs.
Employer or union coverage may continue after you become Medicare-eligible. Coordination of benefits rules determine which coverage pays first (primary) and which pays second (secondary). The determination depends on factors including:
- Employer size (20+ employees affects coordination)
- Whether coverage is active or retiree
- Specific plan rules in employer coverage
Medicaid coordination benefits individuals who qualify for both Medicare and Medicaid (dual eligible). Special Medicare Advantage Plans called Dual Eligible Special Needs Plans (D-SNPs) specifically serve this population with integrated benefits.
Veterans Affairs benefits don't coordinate with Medicare Advantage Plans. You can maintain both but must choose which system to use for specific services. Using VA facilities means your HMO doesn't provide coverage for those services.
Visit moserinsurancegroup.com to explore how different coverage types interact with Medicare Advantage Plans and develop an integrated strategy that maximizes your total benefits.
Choosing the right medicare hmo plan requires careful evaluation of networks, costs, benefits, and how well the plan's structure aligns with your healthcare preferences and needs. Whether you're new to Medicare or reconsidering your current coverage, Moser Insurance Group Inc provides clear guidance and personalized support to help you understand your options without pressure. Contact us at 336-862-1763 or moserinsurancegroup@gmail.com to discuss which Medicare Advantage Plans best fit your situation in the Triad Area.
Recent Comments