

Medicare can feel overwhelming when you're approaching age 65 or helping a family member navigate their healthcare options. Understanding the 4 parts of Medicare is essential for making informed decisions about your healthcare coverage. Each part serves a distinct purpose, covering different aspects of medical care from hospital stays to prescription medications. Whether you live in the Triad Area, Greensboro, Kernersville, High Point, or Winston Salem, knowing how these parts work together will help you build a comprehensive healthcare plan that meets your needs. For personalized guidance, contact Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com.
What Are the 4 Parts of Medicare?
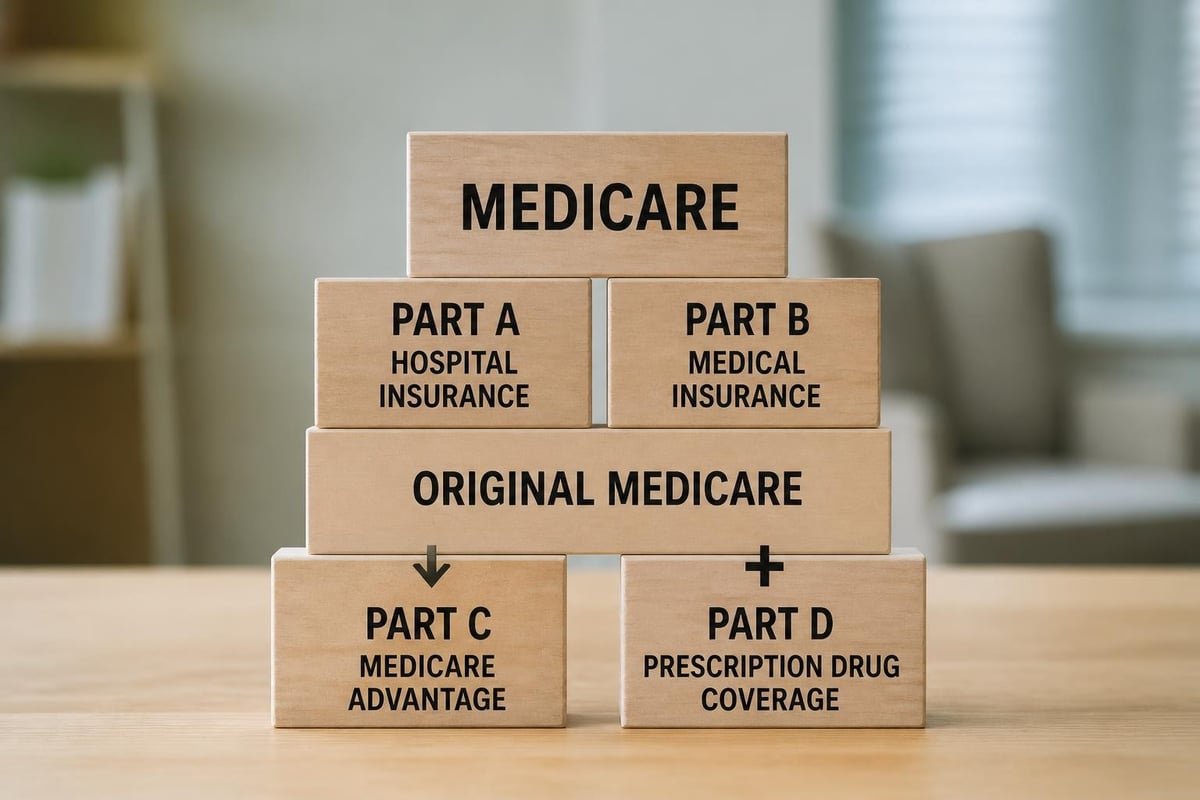
Medicare divides into four distinct parts, each designed to address specific healthcare needs. Part A covers hospital insurance, Part B handles medical insurance, Part C offers Medicare Advantage plans as an alternative delivery system, and Part D provides prescription drug coverage.
These parts work independently yet complement each other to create comprehensive health coverage. Most beneficiaries combine multiple parts to ensure they have adequate protection against medical expenses.
The Structure of Medicare Coverage
Original Medicare consists of Parts A and B, which the federal government administers directly. Parts C and D are optional components offered through private insurance companies approved by Medicare.
Understanding how these parts interact helps you avoid coverage gaps and unnecessary expenses. Some people choose Original Medicare with a separate Part D plan, while others opt for Medicare Advantage (Part C) that bundles everything together.
Medicare Part A: Hospital Insurance
Part A provides coverage for inpatient hospital care, skilled nursing facility stays, hospice care, and some home health services. Most people qualify for premium-free Part A if they or their spouse paid Medicare taxes for at least 10 years (40 quarters) during their working life.
What Part A Covers
- Inpatient hospital stays: Semi-private rooms, meals, general nursing, and hospital services
- Skilled nursing facility care: Following a qualifying hospital stay of at least three days
- Hospice care: Pain relief, symptom management, and support services for terminal illnesses
- Home health care: Part-time or intermittent skilled nursing care and home health aide services
Part A operates on a benefit period system rather than a calendar year. A benefit period begins when you're admitted to a hospital or skilled nursing facility and ends when you haven't received inpatient care for 60 consecutive days.
Part A Costs in 2026
| Cost Type | Amount |
|---|---|
| Monthly Premium | $0 for most (up to $505 if fewer than 30 quarters worked) |
| Hospital Deductible | $1,676 per benefit period |
| Days 1-60 | $0 coinsurance |
| Days 61-90 | $419 per day |
| Days 91+ (Lifetime Reserve) | $838 per day |
The key differences between Medicare Part A and Part B become clearer when you examine their specific coverage areas and cost structures. Part A focuses primarily on facility-based care, while Part B addresses outpatient services.
Medicare Part B: Medical Insurance
Medicare Part B covers medically necessary services and preventive care. This includes doctor visits, outpatient care, medical equipment, and many preventive services designed to keep you healthy.
Core Part B Benefits
Covered services include:
- Doctor visits and outpatient care
- Preventive services (screenings, vaccines, annual wellness visits)
- Ambulance services
- Durable medical equipment (wheelchairs, walkers, hospital beds)
- Mental health services
- Limited outpatient prescription drugs (chemotherapy, some medications administered in a clinical setting)
Part B requires monthly premiums that most beneficiaries pay. The standard premium adjusts annually based on healthcare costs and inflation.
Part B Premium Structure
For 2026, the standard Part B premium is based on your modified adjusted gross income from two years prior (2024 tax returns). Higher-income beneficiaries pay Income-Related Monthly Adjustment Amounts (IRMAA).
| Income (Individual) | Income (Joint) | Monthly Premium |
|---|---|---|
| $106,000 or less | $212,000 or less | Standard rate |
| $106,001-$133,000 | $212,001-$266,000 | Standard + IRMAA Tier 1 |
| $133,001-$167,000 | $266,001-$334,000 | Standard + IRMAA Tier 2 |
| Above $500,000 | Above $750,000 | Standard + IRMAA Tier 4 |
Part B also includes an annual deductible (typically around $240-$250) and generally requires 20% coinsurance for most covered services. This coinsurance has no annual cap, which is why many people choose to add Medicare Supplement plans to help cover these out-of-pocket costs.
Medicare Part C: Medicare Advantage Plans
Medicare Part C, commonly called Medicare Advantage, represents an alternative way to receive your Medicare benefits. Private insurance companies approved by Medicare offer these plans, which must cover everything Original Medicare covers but often include additional benefits.
How Medicare Advantage Works
When you enroll in a Medicare Advantage plan, you still have Medicare, but your coverage comes through the private insurance company rather than directly from the federal government. You must continue paying your Part B premium, plus any additional premium the Medicare Advantage plan charges.
Key features of Medicare Advantage:
- Combines hospital insurance, medical insurance, and usually prescription drug coverage
- Often includes dental, vision, and hearing benefits
- May offer fitness programs, transportation, and over-the-counter allowances
- Uses provider networks (HMO, PPO, or PFFS structures)
- Implements out-of-pocket maximums for cost protection
Comparing Medicare Advantage Options
Different types of Medicare Advantage plans serve different needs. Understanding these variations helps you select the right fit for your healthcare situation and budget.
| Plan Type | Provider Flexibility | Referral Required | Typical Premium Range |
|---|---|---|---|
| HMO | Network only (except emergencies) | Yes, from PCP | $0-$100+ |
| PPO | In and out of network | No | $30-$200+ |
| PFFS | Any Medicare provider accepting plan terms | No | Varies widely |
| SNP | Network only, specialized | Varies | Often $0 |
The comparison between Medicare Part B and Part C highlights fundamental differences in how you access care. While Part B gives you freedom to see any Medicare-accepting provider, Medicare Advantage plans typically use networks to manage costs and coordinate care.
Residents in the Triad Area have access to numerous Medicare Advantage options. If you're exploring top Medicare Advantage plans in Greensboro, Kernersville, High Point, or Winston Salem, working with a knowledgeable agent can help you compare benefits, networks, and costs specific to your area.
Medicare Part D: Prescription Drug Coverage
Part D provides prescription drug coverage through private insurance companies approved by Medicare. These standalone plans work alongside Original Medicare, while Medicare Advantage plans typically include integrated Part D coverage.
Understanding Part D Coverage
Prescription drug plans organize medications into tiers, with different copayments or coinsurance for each tier. Generic drugs typically cost less than brand-name medications, and specialty drugs often require the highest out-of-pocket costs.
Most Part D plans follow this coverage structure:
- Deductible phase: You pay full drug costs until meeting your deductible
- Initial coverage phase: You pay copays or coinsurance until total drug costs reach a certain threshold
- Coverage gap: Costs increase temporarily in this phase
- Catastrophic coverage: Very high out-of-pocket costs trigger lower copayments
Part D Costs and Considerations
Monthly premiums for Part D plans vary significantly based on the plan's formulary (list of covered drugs), pharmacy network, and coverage levels. In 2026, beneficiaries should expect average premiums ranging from $25 to $80 monthly, though some plans cost more.
Important factors when selecting Part D:
- Does the plan cover your specific medications?
- Are your preferred pharmacies in the plan's network?
- What are the tier placements for your drugs?
- Does the plan require prior authorization or step therapy?
- What are your total estimated annual costs (premiums plus out-of-pocket drug expenses)?
Higher-income beneficiaries also pay IRMAA for Part D, using the same income thresholds as Part B. This additional amount adds to your monthly plan premium.
Enrollment Periods for the 4 Parts of Medicare
Understanding when you can enroll in the 4 parts of Medicare prevents costly penalties and coverage gaps. Different enrollment windows apply depending on your situation.
Initial Enrollment Period
Your Initial Enrollment Period (IEP) begins three months before your 65th birthday month, includes your birthday month, and extends three months after. This seven-month window allows you to enroll in Parts A and B, and if desired, Parts C and D.
Timeline example for someone turning 65 in July 2026:
- IEP starts: April 1, 2026
- Birthday month: July 2026
- IEP ends: October 31, 2026
Missing this window can result in late enrollment penalties that last as long as you have Medicare coverage.
Other Important Enrollment Windows
| Period | Timing | Purpose |
|---|---|---|
| General Enrollment Period | January 1 – March 31 annually | For those who missed IEP |
| Annual Enrollment Period | October 15 – December 7 annually | Switch Medicare Advantage or Part D plans |
| Medicare Advantage Open Enrollment | January 1 – March 31 annually | Switch from Medicare Advantage to Original Medicare or change Medicare Advantage plans |
| Special Enrollment Periods | Triggered by qualifying events | Move, lose coverage, etc. |
Combining the 4 Parts of Medicare
Most beneficiaries don't rely on just one part of Medicare. The 4 parts of Medicare work together to create comprehensive coverage, though the exact combination depends on individual needs and preferences.
Common Coverage Combinations
Option 1: Original Medicare + Part D
- Parts A and B provide hospital and medical coverage
- Standalone Part D plan adds prescription coverage
- Many people add a Medigap (Medicare Supplement) plan to cover Original Medicare's gaps
Option 2: Medicare Advantage (Part C)
- Replaces Original Medicare Parts A and B
- Usually includes integrated Part D prescription coverage
- Often adds extra benefits like dental and vision
- Cannot be combined with Medigap
Choosing Your Coverage Path
The decision between these approaches depends on several factors. Consider your healthcare needs, preferred doctors, prescription medications, budget, and travel habits.
People who value provider flexibility often prefer Original Medicare with a supplement. Those seeking additional benefits like dental coverage or lower premiums frequently choose Medicare Advantage. In the Triad Area, both options offer robust choices, and 5-star Medicare Advantage plans provide high-quality care with excellent member satisfaction.
Costs Across the 4 Parts of Medicare
Understanding the complete cost picture helps you budget effectively for healthcare in retirement. Each part carries different expenses, and your total costs depend on which combination you choose.
Breaking Down Medicare Expenses
Fixed costs include:
- Part B monthly premium (standard or IRMAA-adjusted)
- Part D monthly premium (if applicable)
- Medicare Advantage plan premium (if applicable)
- Medigap premium (if you choose a supplement)
Variable costs include:
- Part A deductible when hospitalized
- Part B deductible and 20% coinsurance
- Part D deductibles and copays
- Medicare Advantage copays and coinsurance
Sample Cost Comparison
| Coverage Type | Estimated Monthly Premium | Annual Out-of-Pocket Maximum |
|---|---|---|
| Original Medicare + Part D | $170-$220 | Unlimited (Part B) |
| Original Medicare + Part D + Medigap Plan G | $320-$450 | Limited to Part B deductible |
| Medicare Advantage with drug coverage | $0-$150 | $3,000-$8,000 |
These estimates vary significantly based on your location, health status, and chosen plans. Working with an independent insurance advisor helps you compare actual costs for plans available in Greensboro, Kernersville, High Point, Winston Salem, and throughout the Triad Area.
Special Considerations for the 4 Parts of Medicare
Certain situations require additional attention when navigating the 4 parts of Medicare. Understanding these scenarios prevents confusion and ensures you maintain proper coverage.
Working Past 65
If you or your spouse work past 65 and have employer coverage, you may delay Medicare enrollment without penalty. However, you must enroll when your employer coverage ends to avoid late enrollment penalties.
Employer size matters:
- 20+ employees: You can delay Part B without penalty
- Fewer than 20 employees: Medicare typically becomes primary; delaying may create gaps
Coordination with Other Coverage
Medicare coordinates with other insurance types, including employer plans, retiree coverage, TRICARE, Veterans benefits, and Medicaid. Understanding which coverage pays first (primary vs. secondary) maximizes your benefits and minimizes out-of-pocket costs.
For those exploring how Medicare works alongside other coverage, detailed information about Medicare basics can clarify coordination of benefits rules.
Getting Help with the 4 Parts of Medicare
Making sense of the 4 parts of Medicare doesn't have to be a solo journey. Resources exist to help you understand your options and make confident decisions.
Professional Guidance
Independent insurance agents provide valuable assistance without cost to you. They can:
- Explain how each part works in plain language
- Compare plans from multiple insurance companies
- Help you understand costs and coverage gaps
- Assist with enrollment paperwork
- Provide ongoing support when questions arise
The benefit of working with an independent agent is their ability to show you options from many carriers rather than being limited to one company's products. Visit moserinsurancegroup.com or call 336-862-1763 to discuss your Medicare options with experienced professionals who serve the Triad Area.
Online Resources and Tools
Several reputable websites offer Medicare information:
- Medicare.gov: Official government resource with plan finder tools
- State Health Insurance Assistance Programs (SHIP): Free, unbiased Medicare counseling
- Social Security Administration: Handles Part A and Part B enrollment
The comprehensive breakdown of Medicare parts A through D provides technical details about coverage differences that can supplement conversations with your insurance advisor.
Changes and Updates to Medicare in 2026
Medicare evolves each year, with adjustments to premiums, deductibles, and covered services. Staying informed about these changes helps you adapt your coverage as needed.
2026 Updates
Annual changes typically include premium adjustments for Parts B and D, deductible increases across all parts, IRMAA threshold modifications, and Medicare Advantage benefit updates. Additionally, the Inflation Reduction Act continues to phase in Part D improvements, including catastrophic coverage enhancements.
Plan benefits change annually, even if you keep the same plan. Reviewing your coverage during the Annual Enrollment Period ensures your plan still meets your needs and remains cost-effective.
Looking Ahead
Medicare continues to expand preventive services and modernize coverage. Telehealth benefits, which expanded during the COVID-19 pandemic, remain available for many services. New preventive screenings receive coverage as medical evidence supports their effectiveness.
Understanding whether Medicare Advantage is right for you becomes increasingly important as these plans add innovative benefits and expand availability in areas like the Triad Area, Greensboro, Kernersville, High Point, and Winston Salem.
Common Mistakes to Avoid
Navigating the 4 parts of Medicare successfully means avoiding common pitfalls that create coverage gaps or unnecessary expenses.
Enrollment Errors
Missing your Initial Enrollment Period triggers late enrollment penalties. For Part B, you pay an additional 10% for each 12-month period you were eligible but didn't enroll. Part D penalties equal 1% of the national base premium multiplied by the number of months you went without coverage.
Not researching plans thoroughly can leave you with inadequate coverage. Compare multiple options before choosing, considering not just premiums but also total out-of-pocket costs, provider networks, and prescription drug coverage.
Coverage Gaps
Assuming Medicare covers everything leads to financial surprises. The 4 parts of Medicare don't cover dental care (in most cases), routine vision care, hearing aids, or long-term custodial care. Planning for these expenses separately protects your retirement savings.
Some beneficiaries also fail to coordinate Medicare with other coverage properly, resulting in claim denials or delayed payments. Always inform all your insurance companies about your coverage so they can determine the correct payment order.
Making the Right Choice for Your Situation
Every person's healthcare needs differ, making personalized guidance valuable when selecting among the 4 parts of Medicare. Consider your current health status, prescription medications, preferred doctors and hospitals, budget constraints, and future healthcare expectations.
Questions to Ask Yourself
- Do I want the freedom to see any Medicare provider, or am I comfortable with a network?
- Are my current doctors in Medicare Advantage networks available in my area?
- What prescription medications do I take regularly?
- Do I travel frequently or spend time in multiple states?
- Do I want predictable costs or am I comfortable with variable expenses?
- Would I benefit from extra services like dental, vision, or fitness programs?
Your answers guide you toward either Original Medicare with supplements or Medicare Advantage. Neither choice is universally better; the right option depends entirely on your circumstances.
For residents throughout the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, local factors matter too. Provider availability, plan offerings, and regional costs all influence which combination of the 4 parts of Medicare works best.
Understanding the 4 parts of Medicare empowers you to make informed decisions about your healthcare coverage as you approach or navigate retirement. Whether you're just becoming eligible or reviewing your current coverage, knowing how Parts A, B, C, and D work together helps you build a comprehensive healthcare plan. Moser Insurance Group Inc specializes in helping individuals and families in the Triad Area understand their Medicare options with clear, personalized guidance. We take time to explain the 4 parts of medicare, compare plans, and answer your questions without pressure. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to schedule a consultation and explore which Medicare coverage best fits your needs.
Recent Comments