

Understanding the financial commitment of permanent life insurance requires looking beyond simple monthly payments. Whole life policy cost encompasses premium amounts, cash value growth, and lifetime protection that extends far beyond what temporary coverage offers. For families in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, making informed decisions about permanent coverage means examining how these policies build value while protecting loved ones.
What Determines Whole Life Policy Cost
Multiple factors influence premium calculations for permanent life insurance. Unlike term policies that expire after a set period, whole life maintains consistent premiums throughout your lifetime.
Age and Premium Structure
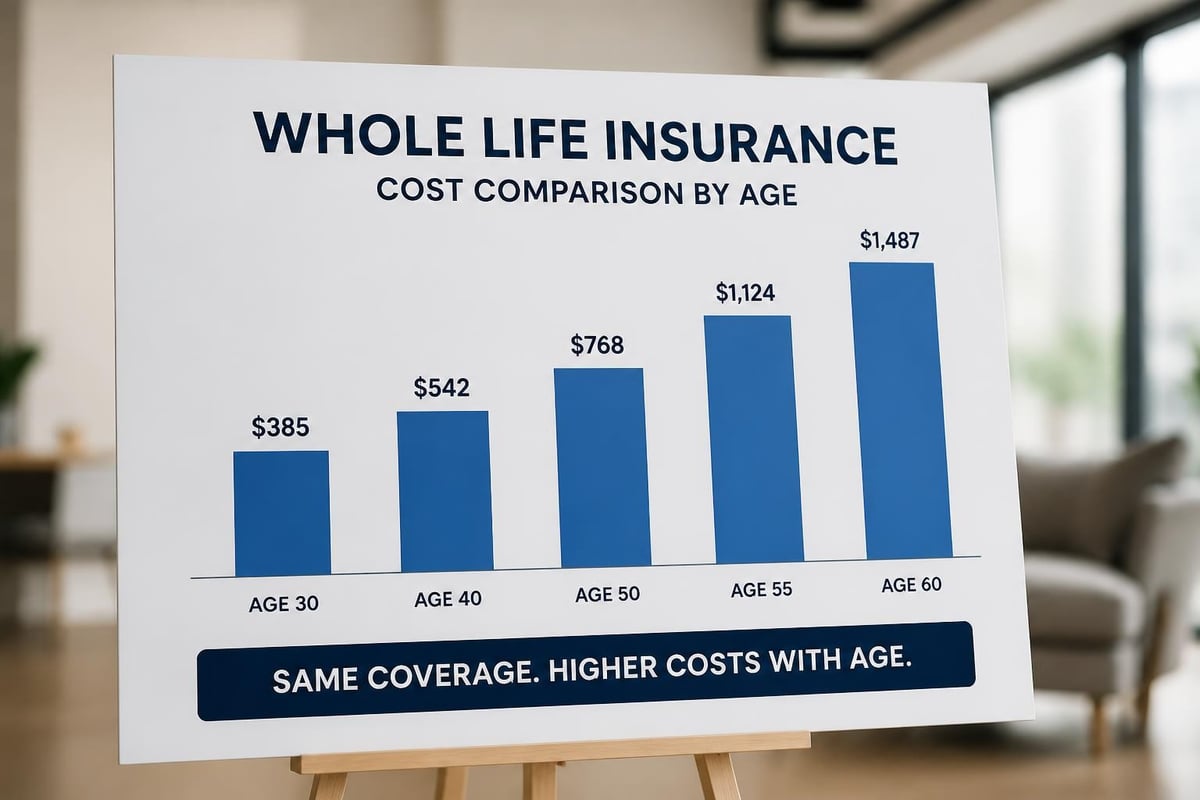
Your age at application significantly impacts whole life policy cost. Younger applicants receive substantially lower premiums because they represent lower mortality risk to insurance companies.
Premium differences by age for $250,000 coverage:
| Age | Healthy Male (Monthly) | Healthy Female (Monthly) |
|---|---|---|
| 30 | $280-$350 | $240-$310 |
| 40 | $420-$520 | $360-$450 |
| 50 | $650-$800 | $540-$680 |
| 60 | $1,100-$1,400 | $920-$1,180 |
These figures reflect standard health classifications in 2026. According to detailed whole life insurance rate analysis, applicants in their 30s pay approximately 40-50% less than those in their 50s for identical coverage amounts.
Health Classification Impact
Insurance companies assign risk classes based on comprehensive medical evaluations. These classifications directly determine whole life policy cost.
- Preferred Plus: Best health rating, lowest premiums (15-25% below standard)
- Preferred: Excellent health with minor considerations (10-15% below standard)
- Standard Plus: Good health, average premiums
- Standard: Acceptable health with some risk factors (baseline pricing)
- Substandard: Health concerns requiring rated premiums (25-200% above standard)
Medical underwriting examines prescription history, family health background, lifestyle habits, and current medical conditions. Tobacco use alone increases premiums by 100-250% compared to non-smoker rates.
Coverage Amount Considerations
The death benefit amount directly correlates with premium expenses. However, whole life policy cost doesn't increase proportionally with coverage.
Purchasing $500,000 coverage costs less than buying two separate $250,000 policies. Economies of scale reduce per-thousand-dollar costs as coverage amounts increase. Most carriers offer policies ranging from $25,000 to $5 million or more for qualified applicants.
Premium Payment Options and Long-Term Costs
Whole life insurance offers flexibility in how you structure payments, which significantly affects overall whole life policy cost throughout your lifetime.
Traditional Lifetime Payment Plans
Standard whole life policies require premium payments until death or age 100-121 (depending on policy structure). These plans feature:
- Lower annual premiums spread across more years
- Predictable budgeting with fixed payments
- Guaranteed cash value accumulation schedule
- No risk of coverage lapsing due to completed payment periods
For a healthy 45-year-old purchasing $300,000 coverage, lifetime payment plans typically cost $450-$580 monthly compared to accelerated options.
Limited Payment Periods
Many families prefer concentrating premium payments into shorter timeframes. Understanding limited payment structures reveals both advantages and tradeoffs.
Common limited payment options:
- 10-Pay Plans: Complete payments in ten years, significantly higher annual premiums
- 20-Pay Plans: Balance affordability with accelerated completion timeline
- Pay-to-65: Align final payment with retirement age, popular among working professionals
- Single Premium: One lump-sum payment, immediate full cash value access
Limited payment plans increase annual whole life policy cost by 40-150% compared to lifetime payment structures. However, they eliminate premium obligations during retirement years when income typically decreases.
Payment Frequency Options
Most carriers allow premium payment scheduling that fits household budgeting:
- Monthly automatic bank withdrawals
- Quarterly payments (slight discount versus monthly)
- Semi-annual payments (moderate discount)
- Annual payments (maximum discount, typically 3-5% savings)
Annual payment modes reduce whole life policy cost slightly through administrative savings passed to policyholders.
Cash Value Component and Actual Cost Analysis
The cash value feature distinguishes whole life from term insurance, creating an asset that offsets nominal whole life policy cost over time.
How Cash Value Accumulates
Each premium payment divides into three components: mortality charges (death benefit cost), administrative expenses, and cash value allocation. During initial policy years, mortality charges and expenses consume larger portions of premiums.
By years 10-15, cash value growth accelerates as:
- Mortality charges stabilize relative to premium amounts
- Administrative expense portions decrease
- Guaranteed interest compounds on accumulated cash value
- Potential dividend payments (from participating policies) accelerate growth
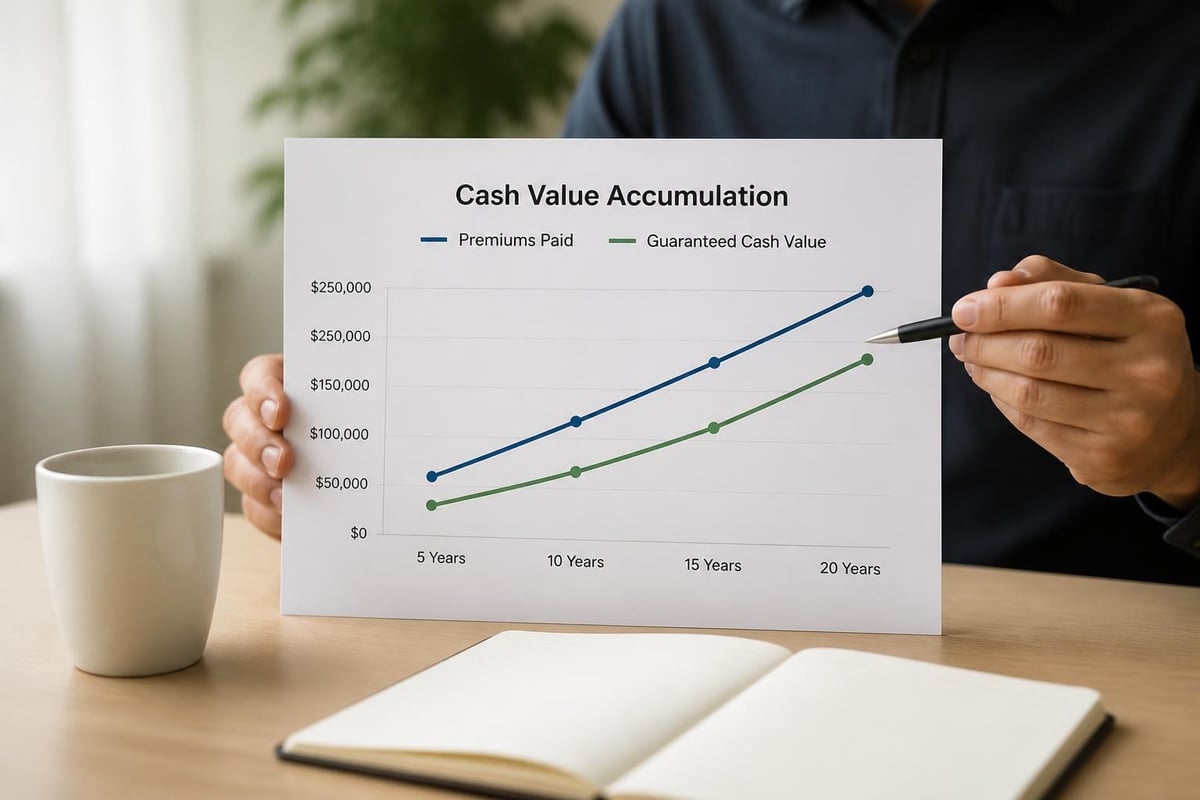
Sample cash value progression for $250,000 policy with $400 monthly premium:
| Year | Total Premiums Paid | Guaranteed Cash Value | Potential Cash Value (with dividends) |
|---|---|---|---|
| 5 | $24,000 | $8,500 | $9,200 |
| 10 | $48,000 | $28,000 | $32,500 |
| 15 | $72,000 | $52,000 | $62,000 |
| 20 | $96,000 | $80,000 | $98,000 |
These projections demonstrate how cash value eventually approaches or exceeds total premium payments, fundamentally changing whole life policy cost calculations.
Policy Loans and Withdrawals
Cash value accessibility provides financial flexibility without policy surrender. Policyholders can borrow against cash value at competitive interest rates (typically 4-8% in 2026).
Key advantages of policy loans:
- No credit check or approval process required
- Loan doesn't appear on credit reports
- Flexible repayment terms without mandatory schedules
- Death benefit remains in force (minus outstanding loan balance)
- Continued cash value growth on full policy value
This feature effectively reduces net whole life policy cost by providing emergency funds without policy termination. Many families use policy loans for home down payments, education expenses, or business opportunities.
Surrender Value Considerations
If you discontinue a whole life policy, the surrender value represents your cash value minus any surrender charges. Early policy years (typically 10-15 years) include surrender charges that decrease annually until elimination.
Understanding surrender schedules helps families evaluate actual whole life policy cost if circumstances change. Whole life insurance fundamentals explain how surrender values protect both policyholders and insurance company financial stability.
Comparing Whole Life Costs to Alternative Options
Many families evaluate whole life policy cost against other life insurance products before making decisions.
Whole Life vs Term Life Insurance
Term insurance provides substantially lower initial premiums but offers no cash value and expires after the term period. A healthy 40-year-old might pay $35-$50 monthly for $500,000 of 20-year term coverage versus $650-$850 monthly for equivalent whole life coverage.
However, this comparison overlooks several factors:
- Term insurance provides zero return if you outlive the policy
- Reapplying for new term coverage at age 60+ becomes prohibitively expensive or medically impossible
- Term policies lack the cash value component that offsets whole life policy cost
- Permanent coverage guarantees death benefit payment regardless of longevity
For those prioritizing affordable protection during working years with dependent children, term life insurance often makes practical sense. Families can explore different life insurance options to determine which approach aligns with their specific financial goals and timeline.
Whole Life vs Universal Life Insurance
Universal life offers flexible premiums and adjustable death benefits, contrasting with whole life's fixed structure. While universal life initially appears less expensive, several considerations affect long-term costs:
Whole Life Advantages:
- Guaranteed premium amounts never increase
- Guaranteed cash value growth regardless of market performance
- Simplified structure with predictable outcomes
- No risk of policy lapse due to insufficient cash value
Universal Life Considerations:
- Premium flexibility requires disciplined overfunding to maintain coverage
- Cash value growth depends on credited interest rates that fluctuate
- Policy expenses can increase, requiring higher payments in later years
- Underfunding risks policy lapse despite years of premium payments
Understanding these structural differences helps contextualize whole life policy cost within broader permanent insurance options.
Regional Cost Factors in North Carolina
Geographic location influences insurance costs through state regulations, local health statistics, and competitive market dynamics. Families throughout Greensboro, High Point, Winston Salem, and Kernersville benefit from North Carolina's competitive insurance marketplace.
State-Specific Regulatory Environment
North Carolina maintains robust insurance department oversight that protects consumers while fostering competitive pricing. State regulations require:
- Transparent policy illustration standards
- Guaranteed nonforfeiture values
- Standardized free-look periods (typically 10-30 days)
- Clear disclosure of all policy fees and charges
These protections ensure whole life policy cost reflects actual insurance value rather than excessive administrative markups.
Local Health and Longevity Statistics
North Carolina's demographic profile influences mortality tables used in premium calculations. The state's improving life expectancy trends (77.9 years statewide in 2026) support competitive whole life policy cost structures.
Residents in the Triad Area specifically benefit from:
- Access to quality healthcare facilities including major medical centers
- Lower cost of living compared to major metropolitan areas
- Strong community health initiatives reducing preventable disease rates
Maximizing Value from Whole Life Insurance
Strategic policy selection and management minimize effective whole life policy cost while maximizing lifetime benefits.
Optimal Coverage Amount Determination
Rather than arbitrarily selecting coverage amounts, calculate actual protection needs through comprehensive analysis:
- Outstanding debt obligations (mortgages, auto loans, personal debt)
- Income replacement requirements for dependent family members
- Education funding goals for children or grandchildren
- Final expenses and estate settlement costs
- Legacy objectives for charitable giving or wealth transfer
This methodical approach prevents over-insuring (wasting premium dollars) or under-insuring (leaving family financially vulnerable).
Dividend Options Selection
Participating whole life policies from mutual insurance companies pay annual dividends based on company performance. These dividends aren't guaranteed but have consistent payment histories spanning decades.
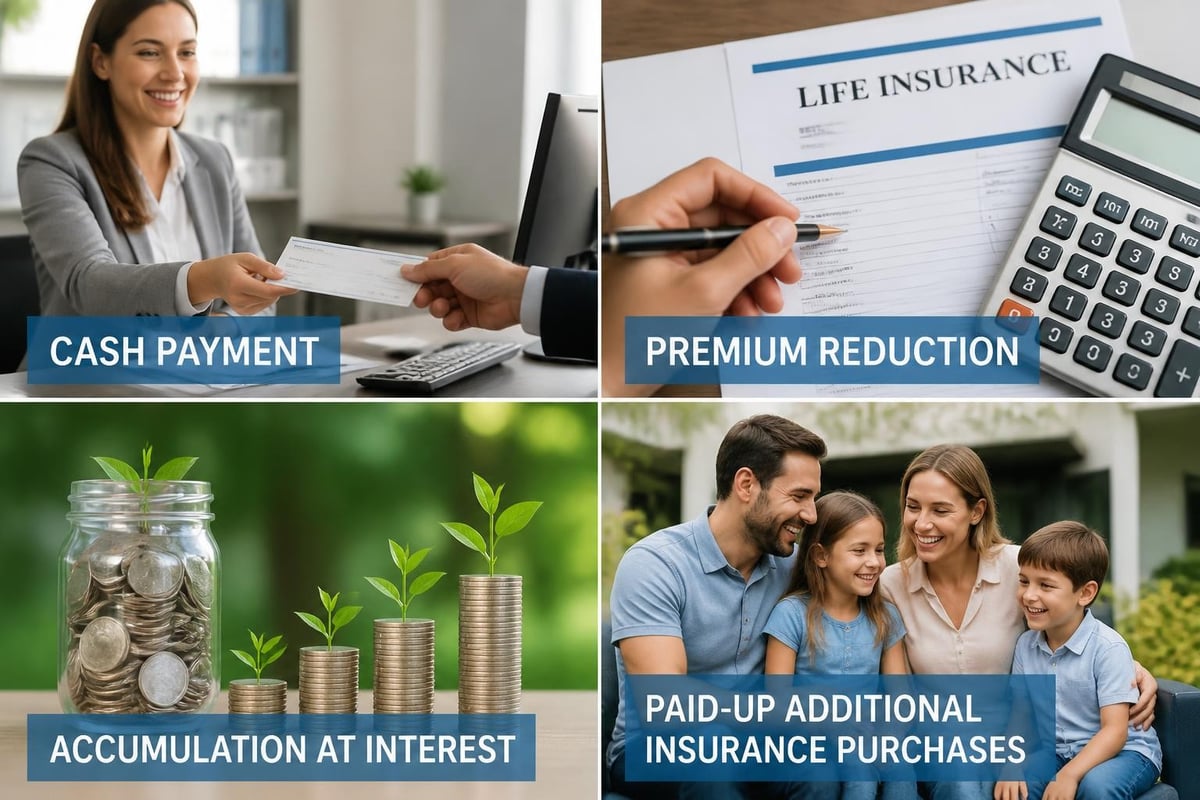
Four primary dividend usage options:
| Option | Description | Best For |
|---|---|---|
| Cash Payment | Receive dividend as taxable income | Immediate liquidity needs |
| Premium Reduction | Apply dividend toward premium payments | Reducing out-of-pocket costs |
| Accumulation | Leave dividend with carrier earning interest | Conservative growth preference |
| Paid-Up Additions | Purchase additional coverage without underwriting | Maximizing long-term death benefit and cash value |
Paid-up additions typically offer the highest long-term value, increasing both death benefit and cash value while reducing effective whole life policy cost per thousand dollars of coverage.
Riders That Enhance Value
Optional policy riders increase initial whole life policy cost but provide valuable benefits:
- Waiver of Premium: Continues coverage without payments if you become disabled (adds 5-10% to base premium)
- Accelerated Death Benefit: Advances portion of death benefit for terminal illness diagnosis (minimal or no cost)
- Guaranteed Insurability: Purchases additional coverage at future dates without medical underwriting (adds 8-15% to base premium)
- Accidental Death Benefit: Doubles death benefit for accidental death (adds 3-8% to base premium)
Carefully selected riders enhance protection without disproportionately increasing whole life policy cost.
Tax Advantages and Financial Planning Integration
Whole life insurance provides several tax benefits that improve its cost-effectiveness within comprehensive financial plans.
Tax-Free Death Benefit
Life insurance proceeds pass to beneficiaries completely tax-free under current federal law (IRC Section 101). This creates significant planning advantages compared to taxable investment accounts or retirement plans.
For a $500,000 whole life policy, beneficiaries receive the full amount regardless of estate size or beneficiary income level. Comparable taxable investment growth would require substantially larger accumulation to net identical after-tax proceeds.
Tax-Deferred Cash Value Growth
Cash value accumulates without annual taxation on growth. This differs fundamentally from:
- Taxable brokerage accounts generating annual tax obligations on dividends, interest, and capital gains
- Bank savings accounts taxing interest income annually
- Rental property income creating yearly tax liabilities
Tax deferral allows cash value to compound more rapidly, effectively reducing long-term whole life policy cost relative to after-tax returns from alternative investments.
Tax-Free Policy Loan Access
Borrowing against cash value creates no taxable event, unlike withdrawals from retirement accounts or investment sales. This provides tax-efficient access to accumulated wealth for major expenses.
Strategic policy loan usage during low-income retirement years avoids pushing taxpayers into higher brackets or triggering increased Medicare premiums (IRMAA adjustments). Research on whole life insurance as a retirement tool examines these advanced planning strategies.
Special Considerations for Different Life Stages
Whole life policy cost optimization varies based on your current life circumstances and financial priorities.
Young Adults and New Families
Individuals in their 20s and 30s receive maximum whole life policy cost advantages through:
- Lowest possible premium rates due to young age and typically excellent health
- Maximum compounding timeframe for cash value accumulation
- Guaranteed insurability regardless of future health changes
- Lock-in rates before inevitable health issues develop
A 28-year-old purchasing $300,000 coverage might pay $240 monthly, while the same person applying at age 48 could pay $650 monthly for identical coverage.
Mid-Career Professionals
Those in their 40s and 50s balance competing financial priorities. Whole life insurance serves multiple objectives:
Income protection for dependents while children remain financially dependent
Supplemental retirement savings through tax-advantaged cash value growth
Estate planning foundation for wealth transfer and liquidity needs
Business succession funding for entrepreneurs planning eventual transitions
Premium affordability remains reasonable while health generally permits standard classifications.
Pre-Retirees and Retirees
Applicants approaching or entering retirement face higher whole life policy cost but gain specific advantages:
- Final expense coverage ensuring burial costs don't burden survivors
- Estate liquidity providing cash for settlement expenses and taxes
- Legacy planning guaranteeing specific asset transfer to heirs or charities
- Pension maximization strategies using life insurance to replace survivor benefits
Limited payment plans concentrating premiums before retirement often appeal to this demographic.
Working with Knowledgeable Insurance Professionals
Navigating whole life policy cost complexities benefits significantly from expert guidance. Understanding policy mechanics, comparing carrier offerings, and optimizing coverage design requires specialized knowledge.
Professional insurance advisors provide:
- Objective analysis of multiple carrier proposals
- Customized coverage recommendations based on specific family situations
- Ongoing policy review and optimization as circumstances change
- Claims assistance ensuring beneficiaries receive full benefits efficiently
For families throughout the Triad Area, working with experienced local professionals ensures you understand all policy details before committing to long-term coverage. Whether you're located in Greensboro, Kernersville, High Point, or Winston Salem, accessible guidance makes the decision process clearer and more confident.
Current Economic Factors Affecting 2026 Costs
Economic conditions in 2026 influence both whole life policy cost and the value proposition of permanent coverage.
Interest Rate Environment
Current interest rates affect policy performance in several ways:
- Insurance companies invest premium reserves in bonds and fixed-income securities
- Higher prevailing rates improve carrier investment returns
- Improved returns translate to better dividend payments on participating policies
- Enhanced dividends reduce net whole life policy cost over time
The relationship between Federal Reserve policy and whole life insurance demonstrates how monetary policy impacts long-term insurance value.
Mortality Improvements
Advancing medical technology and improving health outcomes extend average life expectancy. While this benefits individuals personally, it influences insurance pricing.
Longer life expectancy means:
- Insurance companies collect premiums for extended periods
- Death benefits pay out at later ages on average
- Mortality costs decrease relative to historical assumptions
- Some carriers reduce whole life policy cost to reflect improving mortality
Competitive Market Dynamics
The 2026 life insurance market remains highly competitive, with over 800 carriers competing for customers. This competition benefits consumers through:
Innovative product designs offering enhanced features without proportional cost increases
Technology integration streamlining application processes and reducing administrative expenses
Underwriting improvements allowing more applicants to qualify for preferred rating classes
Transparent pricing models making whole life policy cost comparisons more straightforward
Making Your Whole Life Insurance Decision
Evaluating whether whole life insurance fits your financial strategy requires honest assessment of priorities, budget capacity, and long-term objectives.
Questions to Ask Yourself
Before committing to permanent coverage, consider:
- Do I need lifetime coverage or only protection during working years?
- Can I comfortably afford premiums for decades without financial strain?
- Do the tax advantages and cash value accumulation align with my financial plan?
- Would I benefit from forced savings discipline through mandatory premium payments?
- Does my estate require liquidity for taxes, debts, or equalization among heirs?
Honest answers guide appropriate coverage selection rather than following generic recommendations.
Getting Personalized Quotes
Whole life policy cost varies significantly between carriers for identical coverage. Obtaining multiple competitive quotes ensures optimal pricing.
When requesting proposals, provide:
- Accurate health information for realistic preliminary quotes
- Specific coverage amount and payment period preferences
- Current prescription medications and dosages
- Family health history including parents and siblings
- Tobacco usage history (including cessation dates if applicable)
Complete information generates accurate quotes avoiding surprises during formal underwriting.
Understanding Policy Illustrations
Insurance proposals include detailed policy illustrations projecting long-term performance. These documents show:
Guaranteed values: Minimum cash value and death benefit regardless of company performance
Current assumptions: Projected values based on current dividend scales (not guaranteed)
Premium requirements: Payment amounts, frequency, and duration
Surrender charges: Early termination penalties and when they expire
Review illustrations carefully, focusing on guaranteed values rather than optimistic projections. Conservative planning using guaranteed figures prevents future disappointment.
Understanding whole life policy cost requires examining premiums, cash value potential, tax advantages, and how permanent coverage fits your complete financial picture. The decision extends beyond simple monthly payment amounts to lifetime value creation and family protection. At Moser Insurance Group Inc, we help individuals and families throughout Greensboro, Kernersville, High Point, and Winston Salem understand their life insurance options with clear, pressure-free guidance. Whether you're comparing whole life to other coverage types or determining the right benefit amount for your situation, we provide personalized support so you can make confident decisions. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your specific needs and explore your options.
Recent Comments