
Getting a universal life insurance quote is the first step toward securing flexible, permanent coverage that adapts to your changing financial needs. Unlike traditional whole life policies, universal life insurance offers adjustable premiums and death benefits alongside a cash value component that can grow over time. Whether you're planning for retirement, building generational wealth, or protecting your family in the Triad Area, understanding what goes into a universal life insurance quote helps you make confident decisions without pressure. This guide walks you through the essential components, pricing factors, and practical considerations for obtaining and evaluating quotes in 2026.
What Makes a Universal Life Insurance Quote Different
A universal life insurance quote reflects the unique structure of these policies compared to term or whole life options. The quote breaks down multiple moving parts that work together to create flexible coverage.
Key components typically included in your quote:
- Death benefit amount – The tax-free payout your beneficiaries receive
- Premium payment flexibility – Options for how much and when you pay
- Cash value projection – Estimated growth based on current interest rates
- Cost of insurance – Internal policy charges that increase with age
- Surrender charges – Penalties for early policy cancellation
According to Britannica’s overview of universal life insurance, these policies gained popularity in the 1980s precisely because they unbundled insurance components, giving policyholders transparency and control.
Understanding Premium Flexibility in Quotes
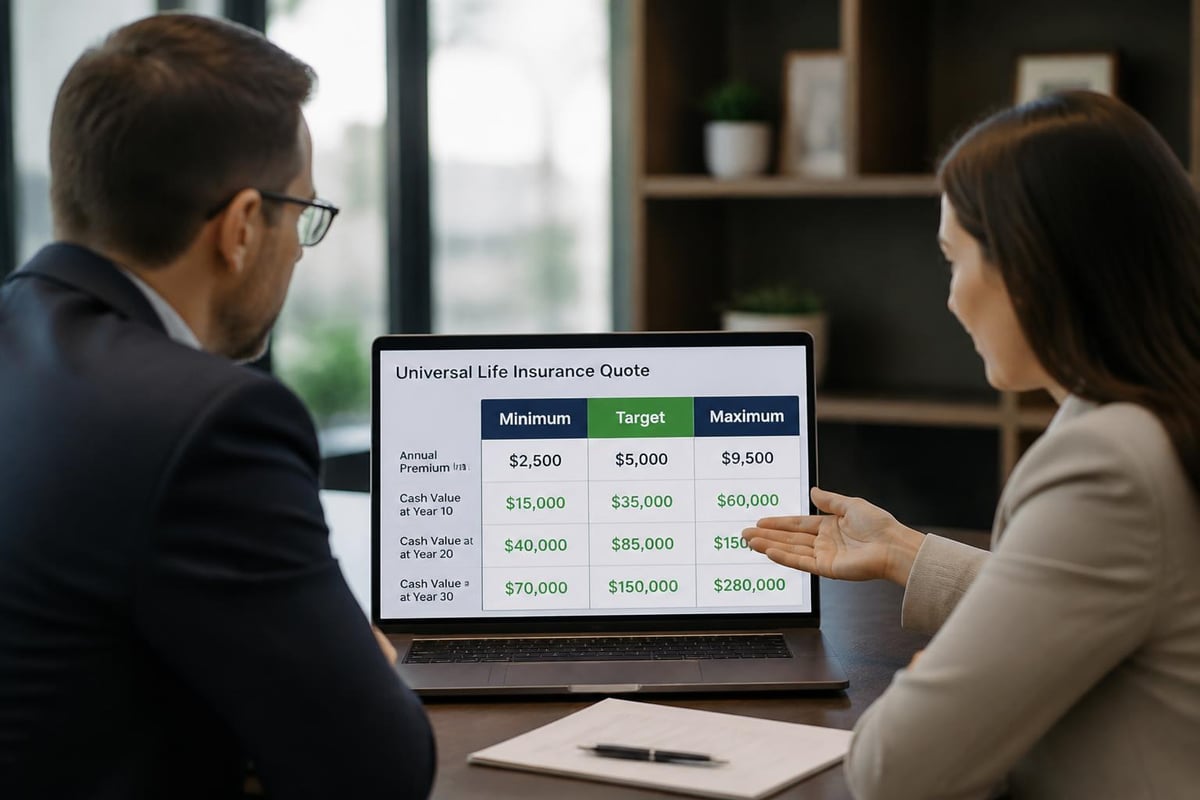
When you request a universal life insurance quote, you'll notice premium options differ significantly from term policies. You're not locked into a fixed monthly payment. Instead, quotes typically show a minimum premium required to keep coverage active and a target premium designed to maintain the policy long-term while building cash value.
This flexibility means you can:
- Pay more during high-earning years to accelerate cash value growth
- Reduce payments during financial hardships (as long as cash value covers costs)
- Skip payments entirely if sufficient cash value exists
- Increase or decrease death benefit amounts within limits
The premium projections in your quote from carriers serving Greensboro, Kernersville, High Point, and Winston Salem typically show three scenarios: minimum funding, target funding, and maximum funding options.
Factors That Influence Your Universal Life Insurance Quote
Multiple variables affect the numbers you'll see when requesting a universal life insurance quote. Understanding these factors helps you anticipate costs and compare options accurately.
| Factor | Impact on Quote | Typical Range |
|---|---|---|
| Age | Higher age = higher premiums | 25% increase per decade |
| Health status | Medical conditions raise costs | Standard to rated classes |
| Coverage amount | More coverage = higher base cost | $100K to $5M+ |
| Gender | Women generally pay less | 10-15% difference |
| Smoking status | Smokers pay significantly more | 100-300% increase |
Your health examination results dramatically affect pricing. State Farm explains that underwriting classifications range from preferred elite (best health, lowest rates) through standard and substandard categories.
How Cash Value Projections Affect Pricing
The cash value component distinguishes universal life from term coverage and significantly impacts quote structures. When you receive a universal life insurance quote, the illustration will project cash value accumulation based on current interest crediting rates.
Current interest crediting methods in 2026 include:
- Fixed rate accounts – Guaranteed minimum rate (typically 2-3%)
- Indexed accounts – Returns tied to market indexes with caps
- Variable accounts – Direct market investment with risk exposure
Nationwide’s analysis demonstrates how these crediting options create different long-term value scenarios. The quote should clearly distinguish between guaranteed values and non-guaranteed projections.
Cash value grows tax-deferred and can be accessed through policy loans or withdrawals. This feature makes universal life insurance attractive for retirement planning, though it adds complexity to quote comparisons.
Types of Universal Life Insurance Quotes to Consider
Not all universal life policies function identically. When you request quotes, you'll encounter several variations, each designed for different financial goals and risk tolerances.
Traditional Universal Life
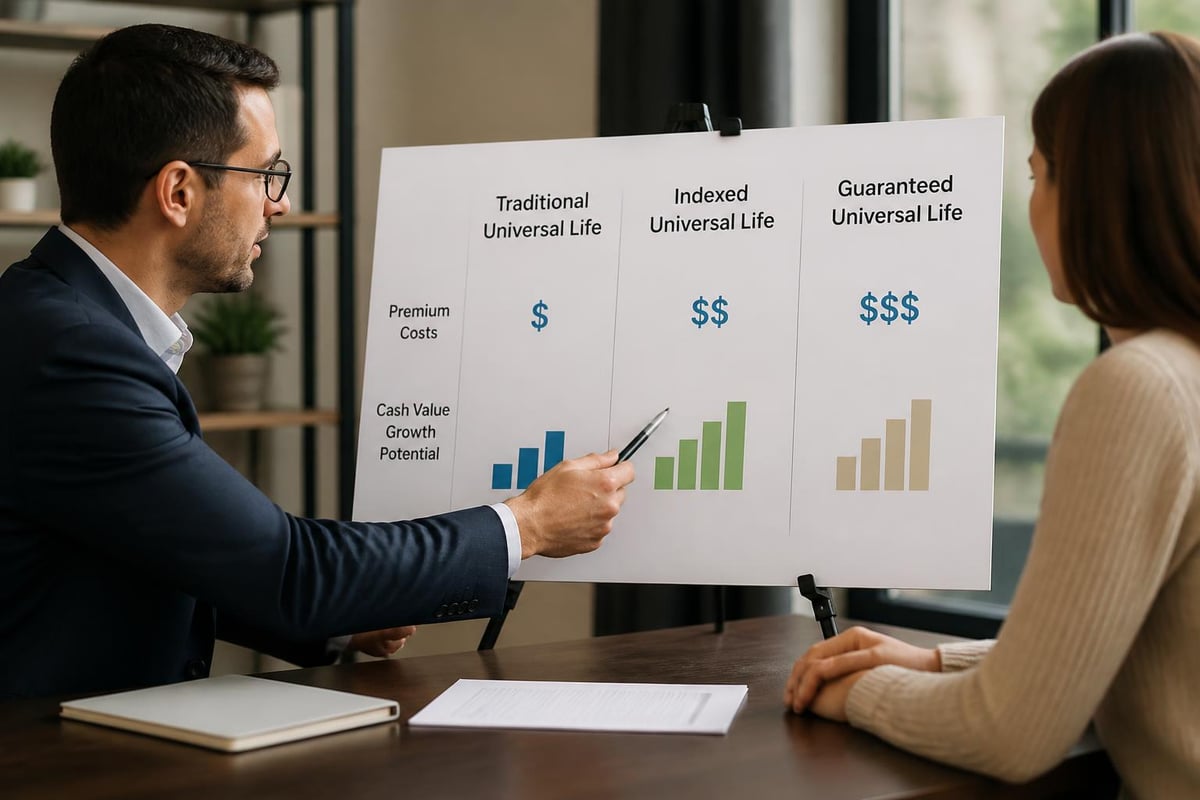
Traditional universal life insurance quotes show straightforward premium flexibility with interest-sensitive cash value growth. These policies credit interest based on the insurer's general account performance, with guaranteed minimum rates.
Best suited for individuals who want:
- Predictable, conservative growth
- Transparent policy mechanics
- Lower administrative complexity
- Guaranteed minimum accumulation
The cash value in traditional UL grows steadily but typically won't match equity market returns during strong economic periods.
Indexed Universal Life
Indexed universal life (IUL) insurance quotes reflect more sophisticated cash value crediting tied to market indexes like the S&P 500. Your cash value participates in index gains up to a cap (often 10-12%) while being protected from market losses through a floor (typically 0-1%).
This middle-ground approach appeals to those seeking growth potential without direct market exposure. However, IUL quotes require careful scrutiny of participation rates, caps, and fees that can significantly impact long-term performance.
Guaranteed Universal Life
Guaranteed universal life insurance quotes emphasize death benefit protection over cash value accumulation. These policies offer the lowest premiums for permanent coverage by minimizing or eliminating cash value growth potential.
Ideal scenarios for guaranteed UL:
- Estate planning needs requiring permanent coverage
- Business succession planning with fixed obligations
- Budget-conscious buyers prioritizing death benefit over savings
- Older applicants seeking affordable permanent protection
According to Western & Southern Financial Group, guaranteed UL provides certainty through contractual guarantees that coverage won't lapse if specified premiums are paid.
How to Request and Compare Universal Life Insurance Quotes
Obtaining accurate universal life insurance quotes requires preparation and understanding of what information insurers need. The process differs from simpler term life quotes because of the policy complexity.
Information You'll Need to Provide
Personal details for accurate quotes:
- Date of birth and gender
- Height and weight (BMI calculation)
- Tobacco use history (past 3-5 years)
- General health status and medications
- Family medical history
- Driving record and any hazardous activities
- Desired coverage amount and premium budget
Carriers may offer preliminary quotes based on limited information, but formal illustrations require comprehensive health and lifestyle data. For residents in the Triad Area, local agents can often provide multiple carrier quotes during a single consultation.
Reading the Policy Illustration
A universal life insurance quote comes as a detailed policy illustration, often 20-30 pages long. Understanding key sections prevents confusion and enables meaningful comparisons.
| Illustration Section | What to Look For | Why It Matters |
|---|---|---|
| Coverage page | Death benefit amounts and options | Confirms protection level |
| Premium schedule | Minimum vs. recommended payments | Shows flexibility and requirements |
| Cash value projection | Guaranteed and non-guaranteed columns | Realistic growth expectations |
| Policy charges | Cost of insurance and admin fees | Ongoing expense transparency |
| Loan provisions | Interest rates and repayment terms | Access to cash value details |
AAA Life Insurance emphasizes that the guaranteed column shows worst-case scenarios while non-guaranteed projections assume current rates continue indefinitely, which rarely happens.
Comparing Multiple Quotes Effectively
Never rely on a single universal life insurance quote. Obtaining 3-5 quotes from different carriers reveals pricing variations and product differences that can save thousands over your lifetime.
Essential comparison points:
- Projected cash value at ages 65, 75, and 85
- Total premiums paid under target funding scenario
- Internal rate of return on cash value
- Financial strength ratings of insurance companies
- Policy flexibility for premium adjustments
- Surrender charge schedules and durations
Working with an independent agent serving Greensboro, Kernersville, High Point, and Winston Salem provides access to multiple carriers without separate applications. This streamlined approach saves time while ensuring comprehensive market coverage.
Common Mistakes When Evaluating Universal Life Insurance Quotes
Even financially sophisticated individuals make errors when reviewing universal life insurance quotes. Avoiding these pitfalls leads to better long-term outcomes.
Focusing Only on Illustrated Returns
The most common mistake is accepting non-guaranteed projections as realistic expectations. A universal life insurance quote showing 6% average crediting looks attractive, but guaranteed columns tell the true story.
Reality checks for illustrations:
- Current interest rate environment (2026 rates around 4-5%)
- Historical insurance company crediting rates
- Guaranteed minimum rates in the contract
- Impact of fees and charges on net returns
Insurance regulations require illustrations to show performance at current rates, but Wikipedia’s explanation of universal life insurance notes that actual crediting fluctuates with economic conditions.
Underestimating Long-Term Costs
Universal life insurance quotes often show attractive early-year premiums, but the cost of insurance increases annually as you age. Failing to account for this escalation causes policies to lapse unexpectedly.
The internal cost structure means that while premiums stay level, the amount going toward actual insurance protection decreases over time as more premium dollars cover rising insurance costs. This dynamic requires either higher premium payments or strong cash value growth to sustain the policy.
Ignoring the Importance of Funding Strategy
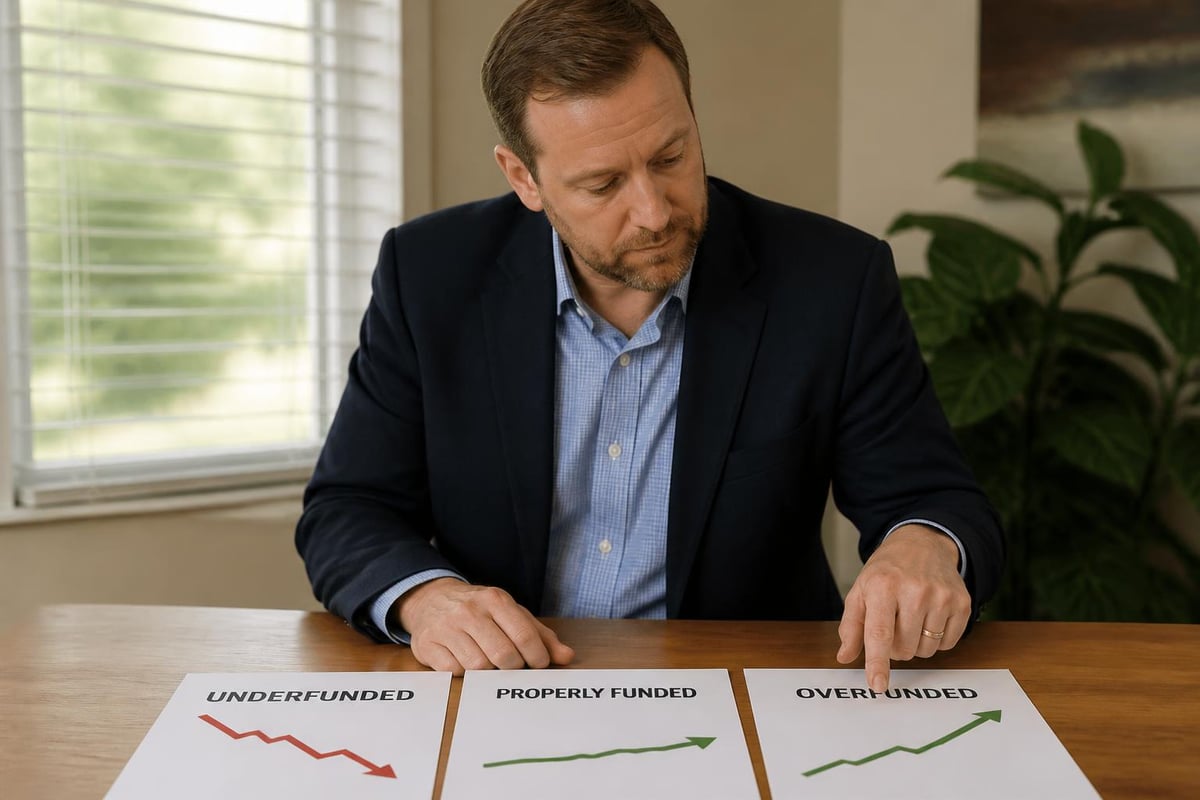
Your universal life insurance quote is only as good as your commitment to the funding strategy. Many policies fail because owners pay minimum premiums during early years, leaving insufficient cash value to sustain coverage when costs rise.
Tax Considerations in Universal Life Insurance Quotes
The tax advantages embedded in universal life policies add significant value not immediately apparent in basic quote numbers. Understanding these benefits helps you appreciate the true cost-effectiveness of coverage.
Tax-Deferred Cash Value Growth
Cash value in your universal life policy grows without annual taxation on interest, dividends, or capital gains. This tax deferral compounds over decades, creating substantial advantages over taxable investment accounts.
Tax comparison example (hypothetical):
- $500 monthly premium creating $200 cash value accumulation
- 5% annual growth over 30 years
- Tax-deferred account: $166,452
- Taxable account (25% bracket): $142,137
- Tax advantage: $24,315
Beyond life insurance considerations, proper tax planning across all financial areas maximizes wealth accumulation. Services like Taxt specialize in comprehensive tax strategies that complement insurance planning, helping business owners and families reduce overall tax burdens while building long-term security.
Tax-Free Death Benefits
The death benefit paid to beneficiaries arrives income-tax-free, regardless of policy size. A $1 million universal life insurance quote represents $1 million of tax-free wealth transfer to your family.
This contrasts sharply with retirement accounts and other assets subject to income taxation upon distribution. Advanced research on life insurance applications demonstrates how machine learning techniques are improving risk assessment and pricing accuracy, potentially leading to better quote accuracy in 2026.
Policy Loan Tax Treatment
Accessing cash value through policy loans provides tax-free income during retirement or emergencies. The loan itself isn't taxable income because you're borrowing against your own accumulated value.
However, unpaid loans reduce the death benefit and can cause policy lapses if they exceed cash value. Your universal life insurance quote should include loan provision details and projected loan capacity at various ages.
Working with Insurance Professionals for Accurate Quotes
While online quote tools provide preliminary estimates, working with experienced insurance professionals ensures you receive accurate universal life insurance quotes tailored to your specific situation.
Benefits of Independent Insurance Agents
Independent agents represent multiple carriers, providing objective comparisons that captive agents cannot offer. When seeking universal life insurance quotes in North Carolina, independent agencies can access dozens of insurers simultaneously.
Advantages of working with independent professionals:
- Access to more insurance carriers and product options
- Unbiased recommendations based on your needs
- Assistance with application and underwriting process
- Ongoing policy service and reviews
- Claims assistance when benefits are needed
Agents familiar with North Carolina health insurance markets understand regional considerations and carrier preferences that affect pricing and availability.
Questions to Ask Your Insurance Agent
Preparing thoughtful questions helps you evaluate both the universal life insurance quote and the agent providing it. Professional agents welcome detailed inquiries and provide clear, honest answers.
- How many carriers did you compare for this quote?
- What assumptions drive the cash value projections?
- How do these quotes compare to term life options?
- What happens if I need to reduce premiums temporarily?
- How financially stable is the recommended insurance company?
- What ongoing reviews do you provide after purchase?
- How are you compensated for this recommendation?
Transparency about compensation matters because commission structures can influence recommendations. Ethical agents disclose these details and prioritize your long-term interests.
Local Expertise in the Triad Area
Working with insurance professionals who understand the Greensboro, Kernersville, High Point, and Winston Salem markets provides distinct advantages. Local agents recognize regional economic conditions, understand community needs, and offer convenient face-to-face consultations.
You can reach qualified insurance professionals at 336-862-1763 or via email at moserinsurancegroup@gmail.com to discuss your universal life insurance quote needs and schedule a personalized consultation.
When Universal Life Insurance Makes Financial Sense
Not everyone needs universal life insurance, despite its flexibility and benefits. Understanding when these policies align with financial goals prevents purchasing coverage that doesn't serve your actual needs.
Ideal Candidates for Universal Life Coverage
Universal life insurance quotes make most sense for individuals who:
- Need permanent coverage extending beyond 20-30 years
- Want flexible premium payment options
- Seek tax-advantaged wealth accumulation
- Have maximized retirement account contributions
- Run businesses requiring key person or succession planning
- Face estate tax considerations requiring liquidity
For straightforward temporary protection needs, exploring options through resources like best term life insurance providers often delivers better value.
Alternative Coverage Options to Consider
Before committing to a universal life insurance quote, evaluate whether simpler or more specialized products better serve your goals.
| Coverage Type | Best For | Key Advantage |
|---|---|---|
| Term Life | Temporary needs, budget constraints | Lowest initial cost |
| Whole Life | Guaranteed values, simplicity | Predictable premiums and growth |
| Variable Universal Life | Market participation, risk tolerance | Investment control |
| Guaranteed Universal Life | Pure death benefit focus | Permanent coverage at lower cost |
Research on polynomial diffusion models demonstrates the mathematical complexity behind pricing various life insurance products, highlighting why professional guidance proves valuable when comparing options.
Integration with Comprehensive Financial Planning
A universal life insurance quote shouldn't be evaluated in isolation. The policy must fit within your broader financial plan, complementing retirement savings, emergency funds, and other insurance coverage.
Consider how the premium commitment affects other financial priorities. Money directed toward universal life insurance becomes unavailable for debt reduction, education funding, or investment accounts. The decision requires balancing competing priorities based on your unique circumstances.
For individuals approaching retirement age, coordinating life insurance with Medicare health plans and supplemental coverage creates comprehensive protection across health and financial security needs.
Maintaining and Reviewing Your Universal Life Policy
Obtaining a competitive universal life insurance quote is just the beginning. Ongoing policy management ensures coverage remains appropriate and performs as expected.
Annual Policy Reviews
Schedule annual reviews of your universal life insurance policy to track performance against original projections in your quote. These reviews identify developing issues before they become critical problems.
Annual review checklist:
- Compare actual cash value to illustrated projections
- Assess whether current premiums remain adequate
- Evaluate crediting rates versus original assumptions
- Review beneficiary designations for accuracy
- Consider adjusting death benefit based on changing needs
- Examine total policy charges and fees
Life circumstances change over decades. Marriage, children, business ownership, home purchases, and retirement all affect insurance needs. Your policy should evolve accordingly.
Adjusting Coverage as Needs Change
The flexibility promised in your original universal life insurance quote becomes valuable only if you actively use it. Don't hesitate to adjust premiums or coverage amounts when financial situations shift.
Common scenarios requiring adjustments include job loss, inheritance, business sale, divorce, or significant health changes. Contact your agent or visit moserinsurancegroup.com for guidance on modification options.
Avoiding Policy Lapses
Universal life insurance policies lapse when insufficient cash value exists to cover monthly charges and no premium payment arrives. Unlike term policies with clear expiration dates, UL lapses can occur unexpectedly if not monitored.
Warning signs of potential policy lapse:
- Declining cash value on annual statements
- Notices from insurance company requesting premium
- Crediting rates significantly below original projections
- Increased cost of insurance charges due to aging
- Outstanding policy loans approaching cash value limits
If you receive lapse warnings, contact your insurance professional immediately at 336-862-1763 to explore options for preserving coverage.
Understanding Insurance Company Financial Strength
The universal life insurance quote you receive is only as reliable as the company backing it. Insurance company financial stability determines whether projected benefits will be there when needed.
Rating Agency Assessments
Independent rating agencies evaluate insurance companies' financial strength and ability to meet policy obligations. Before accepting any universal life insurance quote, verify the carrier's ratings.
Major rating agencies and their top ratings:
- AM Best: A++ and A+
- Standard & Poor's: AAA and AA+
- Moody's: Aaa and Aa1
- Fitch: AAA and AA+
Target companies with ratings in the top two or three categories from multiple agencies. Financial strength matters more for permanent insurance than term coverage because relationships span decades rather than years.
Company History and Reputation
Beyond current ratings, research the insurance company's history of dividend payments, crediting rates, and customer service. Companies with consistent performance through multiple economic cycles demonstrate reliability.
Ask your agent about the carrier's track record during the 2008 financial crisis and the 2020 pandemic recession. How did they treat policyholders? Did they maintain crediting rates? Were claims paid promptly?
Understanding what drives a universal life insurance quote empowers you to make informed decisions about permanent coverage that adapts to your changing needs throughout life. The premium flexibility, cash value potential, and lifetime protection create powerful financial tools when properly structured and maintained. Whether you're protecting your family in Greensboro, planning for retirement in Kernersville, building business value in High Point, or creating generational wealth in Winston Salem, the right universal life policy provides security and flexibility. Moser Insurance Group Inc specializes in helping individuals and families understand their life insurance options with clear guidance and personalized support, ensuring you make confident decisions without pressure. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com to discuss your coverage needs and receive personalized universal life insurance quotes.
Recent Comments