

Choosing between healthcare coverage options can feel overwhelming, especially when you're approaching Medicare eligibility or helping a loved one navigate their choices. Understanding the fundamental differences between traditional Medicare vs Medicare Advantage becomes crucial for making an informed decision that aligns with your healthcare needs, budget, and lifestyle. Both options provide essential coverage, but they work in distinctly different ways that can significantly impact your out-of-pocket costs, provider access, and overall healthcare experience. This comprehensive guide will help you understand these differences so you can select the coverage that works best for your situation.
Understanding Traditional Medicare Structure
Traditional Medicare, also known as Original Medicare, consists of two distinct parts that work together to provide basic healthcare coverage. Part A covers hospital stays, skilled nursing facility care, hospice care, and some home health services. Part B handles medical services including doctor visits, outpatient care, preventive services, and durable medical equipment.
When you choose Traditional Medicare, you're working directly with the federal Medicare program. This means your benefits are standardized across the country, and you can see any doctor or visit any hospital that accepts Medicare assignment. The official Medicare comparison resource provides detailed information about these fundamental differences.
Cost Structure and Out-of-Pocket Expenses
Traditional Medicare operates on a fee-for-service model with specific cost-sharing requirements:
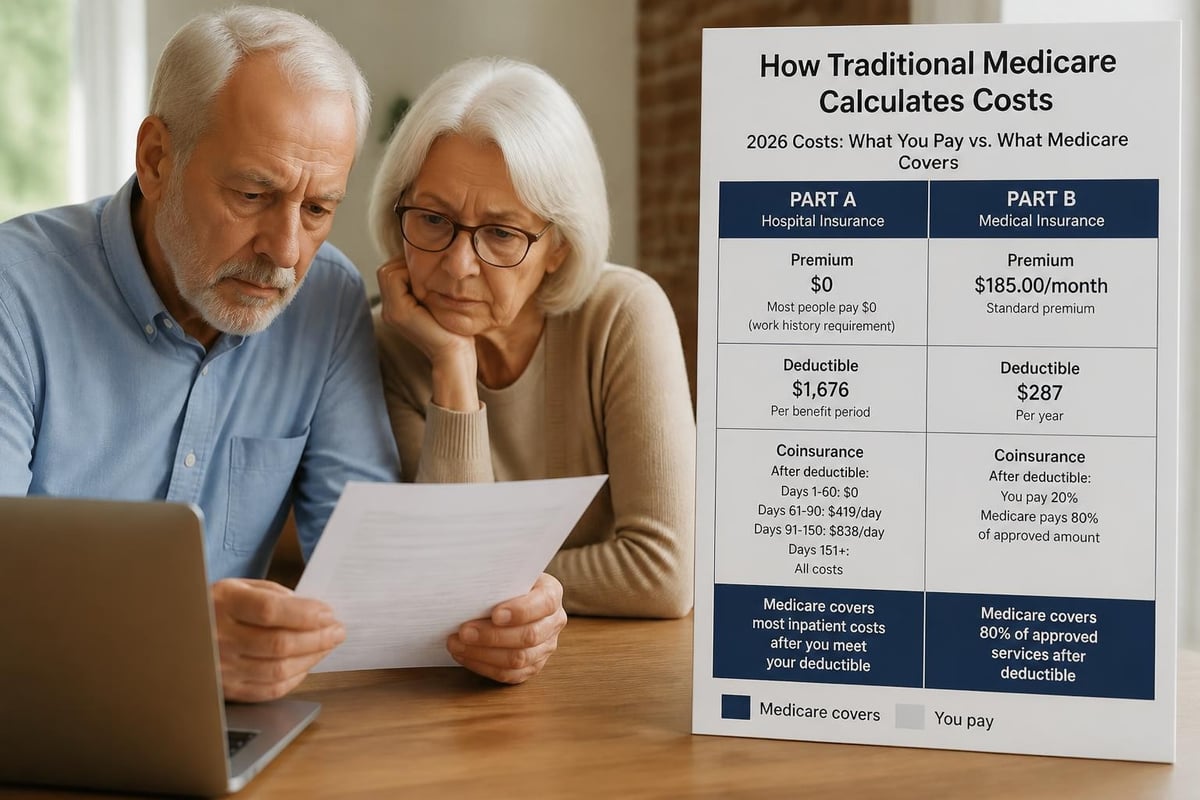
- Part A Premium: Most people pay $0 if they or their spouse paid Medicare taxes for at least 10 years
- Part B Premium: Standard amount of $185 per month in 2026 (varies based on income)
- Deductibles: Part A has a $1,676 deductible per benefit period; Part B has a $257 annual deductible
- Coinsurance: Typically 20% of Medicare-approved amounts for Part B services with no annual maximum
These costs can add up quickly without supplemental coverage. Many beneficiaries choose to add Medicare Supplement Plans to help cover the gaps in Traditional Medicare, reducing their out-of-pocket exposure for medical services.
Medicare Advantage Plans Explained
Medicare Advantage represents an alternative way to receive your Medicare benefits through private insurance companies approved by Medicare. These plans must cover everything Traditional Medicare covers, but they bundle Part A and Part B into a single plan, often including additional benefits that Original Medicare doesn't provide.
Private insurers offer Medicare Advantage plans, and they typically operate as managed care organizations. Most function as HMO (Health Maintenance Organization) or PPO (Preferred Provider Organization) plans, which means they use provider networks to deliver care. According to Healthline’s comprehensive analysis, these plans have grown significantly in popularity over the past decade.
Additional Benefits and Coverage
Medicare Advantage plans frequently include benefits beyond Traditional Medicare:
- Prescription drug coverage (Part D) integrated into the plan
- Dental, vision, and hearing services
- Fitness programs and gym memberships
- Over-the-counter medication allowances
- Transportation to medical appointments
- Telehealth services with expanded access
| Benefit Type | Traditional Medicare | Medicare Advantage |
|---|---|---|
| Hospital Care (Part A) | Covered | Covered |
| Medical Services (Part B) | Covered | Covered |
| Prescription Drugs | Requires separate Part D | Often included |
| Dental Coverage | Not covered | Usually included |
| Vision Coverage | Limited | Usually included |
| Out-of-Pocket Maximum | None | Annual cap required |
These additional benefits make Medicare Advantage attractive for individuals who want comprehensive coverage in a single plan. However, these extras come with specific network restrictions and utilization management requirements.
Provider Networks and Access Differences
One of the most significant distinctions in the traditional Medicare vs Medicare Advantage debate involves how you access healthcare providers. This difference can profoundly impact your healthcare experience and costs.
With Traditional Medicare, you have nationwide freedom to see any doctor, specialist, or hospital that accepts Medicare patients. You don't need referrals to see specialists, and you can seek care anywhere in the United States. This flexibility is particularly valuable if you travel frequently, spend time in multiple locations, or want unrestricted access to specialized medical centers.
Network Restrictions in Medicare Advantage
Medicare Advantage plans typically limit coverage to specific provider networks:
- HMO Plans: You must use network providers (except emergencies) and need referrals for specialists
- PPO Plans: You can see out-of-network providers but pay higher costs; referrals typically not required
- PFFS Plans: You can see any Medicare-approved provider who accepts the plan's payment terms
- SNP Plans: Special Needs Plans designed for people with specific diseases or characteristics
Before enrolling in Medicare Advantage, verify that your current doctors participate in the plan's network. Provider networks can change annually, which means your doctor might be in-network one year and out-of-network the next.
Cost Comparison and Financial Considerations
Analyzing the true cost difference between traditional Medicare vs Medicare Advantage requires looking beyond monthly premiums to understand total annual healthcare expenses. Your out-of-pocket costs depend heavily on your health status, medication needs, and healthcare utilization patterns.
Traditional Medicare participants typically pay:
- Part B premium ($185/month standard in 2026)
- Part D prescription drug plan premium (varies by plan)
- Medicare Supplement (Medigap) premium if desired (varies widely)
- Cost-sharing for services unless covered by Medigap
- No out-of-pocket maximum protection
Medicare Advantage enrollees face different expenses:
- Plan premium (ranges from $0 to over $200/month depending on benefits)
- Copays for doctor visits ($0-$50 typically)
- Copays for specialist visits ($40-$75 typically)
- Hospital copays (varies by plan)
- Annual out-of-pocket maximum ($8,850 maximum limit in 2026)
Calculating Your Total Healthcare Costs
To determine which option costs less for your situation, calculate potential annual expenses:
| Cost Category | Traditional Medicare + Supplements | Medicare Advantage |
|---|---|---|
| Monthly Premiums | $185 (Part B) + $150-300 (Medigap) + $35 (Part D) | $0-200 (varies by plan) |
| Doctor Visit Copays | Covered by Medigap or 20% coinsurance | $0-50 per visit |
| Specialist Copays | Covered by Medigap or 20% coinsurance | $40-75 per visit |
| Annual Maximum | Unlimited exposure without Medigap | Capped at $8,850 |
| Prescription Costs | Part D plan rules apply | Integrated Part D coverage |
Medical News Today’s comparison guide emphasizes that neither option is universally cheaper-your individual circumstances determine which provides better value.
Prescription Drug Coverage Considerations
Prescription drug coverage represents another crucial difference in the traditional Medicare vs Medicare Advantage equation. Traditional Medicare doesn't include prescription drug coverage in Parts A or B, so beneficiaries must enroll in a standalone Part D plan if they want medication coverage.
Medicare Advantage plans typically integrate prescription drug coverage directly into the plan design. This integration simplifies administration-one card, one premium, one plan to manage. However, formularies (covered medication lists) vary significantly between plans, and your medications might have different coverage tiers or restrictions.
Evaluating Prescription Coverage
When comparing drug coverage, examine these factors:
- Formulary Coverage: Does the plan cover all your current medications?
- Tier Placement: What tier are your drugs on, and what does that mean for costs?
- Utilization Management: Are there prior authorizations, step therapy, or quantity limits?
- Pharmacy Networks: Can you use your preferred pharmacy?
- Coverage Gap: How does the plan handle the "donut hole" coverage gap?
If you take multiple medications or specialty drugs, carefully review the specific coverage details before choosing between Traditional Medicare with Part D versus Medicare Advantage with integrated drug coverage.
Enrollment Periods and Switching Between Plans
Understanding when you can enroll or switch between traditional Medicare vs Medicare Advantage plans prevents gaps in coverage and potential penalties. Medicare has specific enrollment windows that govern when you can make changes.
Your Initial Enrollment Period runs seven months, including the three months before your 65th birthday month, your birthday month, and three months after. During this window, you can choose Traditional Medicare or Medicare Advantage without penalties.
Annual Enrollment Opportunities
After initial enrollment, you have several opportunities to change coverage:
- Annual Enrollment Period (October 15 – December 7): Switch between Traditional Medicare and Medicare Advantage, change Medicare Advantage plans, or modify Part D coverage
- Medicare Advantage Open Enrollment (January 1 – March 31): Switch from Medicare Advantage to Traditional Medicare or change to a different Medicare Advantage plan
- Special Enrollment Periods: Available due to qualifying life events like moving, losing coverage, or entering a nursing home
The American Lung Association provides valuable insights for people with chronic conditions when considering coverage changes.
Health Status and Future Healthcare Needs
Your current health status and anticipated future needs should heavily influence your decision between traditional Medicare vs Medicare Advantage. These plans serve different populations effectively based on healthcare utilization patterns and medical requirements.
Traditional Medicare often works best for individuals who:
- Have complex medical conditions requiring specialist care
- Travel frequently or spend time in multiple states
- Want maximum flexibility in provider choice
- Prefer separation between medical and prescription coverage
- Have established relationships with specific doctors or medical centers
Medicare Advantage may be more suitable for people who:
- Are generally healthy with predictable healthcare needs
- Prefer coordinated care through a primary care physician
- Want additional benefits like dental and vision
- Live in areas with robust Medicare Advantage networks
- Appreciate having an annual out-of-pocket maximum for budget predictability
Geographic Considerations and Rural Access
Where you live significantly impacts your Medicare options, particularly for Medicare Advantage plans. Urban areas like Greensboro, Kernersville, High Point, and Winston Salem in the Triad Area typically have numerous Medicare Advantage plans available with extensive provider networks. Rural areas may have limited plan options and smaller networks.
Traditional Medicare provides consistent coverage regardless of location. Whether you're receiving care in a major metropolitan hospital or a rural clinic, your benefits remain the same as long as the provider accepts Medicare. This geographic consistency makes Traditional Medicare particularly valuable for people who split time between locations or have family scattered across different regions.
Plan Availability Varies by County
Medicare Advantage plan availability depends on your county of residence. Some counties have dozens of plan choices, while others have few or none. Before committing to Medicare Advantage, verify that adequate plan options exist in your area and that your preferred providers participate in available networks.
If you're considering moving or spending extended time elsewhere, research Medicare Advantage options in both locations. You might need to switch back to Traditional Medicare if you relocate to an area where your current plan doesn't operate or lacks adequate network providers.
Making Your Decision: Key Factors to Evaluate
Choosing between traditional Medicare vs Medicare Advantage requires careful evaluation of multiple personal factors. No single answer works for everyone-your optimal choice depends on your unique circumstances, priorities, and healthcare expectations.
Use this decision framework to guide your analysis:
Financial Assessment
- Calculate total potential annual costs under each option
- Consider whether predictable monthly costs or maximum flexibility matters more
- Evaluate your prescription drug expenses and coverage needs
- Account for supplemental coverage costs with Traditional Medicare
Healthcare Priorities
- Identify your must-have providers and verify network participation
- Determine how often you see specialists and whether referrals would be problematic
- Assess whether additional benefits like dental and vision provide value
- Consider your comfort level with managed care versus fee-for-service
Lifestyle Factors
- Evaluate how often you travel and where you might need care
- Consider whether you split time between residences
- Assess your willingness to navigate network restrictions
- Determine whether plan stability or ability to switch matters more
NerdWallet’s comprehensive guide offers additional perspectives on these decision factors. Many people also find it helpful to take Kiplinger’s interactive quiz to identify which approach aligns with their priorities.
Common Misconceptions and Myths
Several misconceptions about traditional Medicare vs Medicare Advantage persist, leading to confusion and potentially poor decisions. Understanding the truth behind these myths helps ensure you base your choice on accurate information.
Myth: Medicare Advantage costs less than Traditional Medicare
Reality: Total costs depend on your healthcare utilization-neither option is universally cheaper
Myth: You can only change plans during your initial enrollment
Reality: Annual enrollment periods allow changes each year, plus special enrollment periods exist for qualifying events
Myth: Traditional Medicare provides no out-of-pocket protection
Reality: While Traditional Medicare has no built-in maximum, Medicare Supplement plans can provide comprehensive protection
Myth: Medicare Advantage plans always include prescription coverage
Reality: While most do, some Medicare Advantage plans don't include Part D drug coverage
Myth: You must choose between Traditional Medicare and Medicare Advantage permanently
Reality: You can switch between these options during enrollment periods based on changing needs
Recent survey data from Kiplinger reveals that understanding these facts significantly impacts satisfaction with Medicare coverage choices. Clear, accurate information empowers better decisions.
Impact of Supplement Insurance on Traditional Medicare
When evaluating traditional Medicare vs Medicare Advantage, you must factor in Medicare Supplement insurance (Medigap) for a fair comparison. Traditional Medicare alone leaves beneficiaries exposed to significant cost-sharing, but Medigap plans fill these gaps.
Medicare Supplement plans standardized into lettered plans (A, B, D, G, K, L, M, N) provide varying levels of coverage for deductibles, coinsurance, and other out-of-pocket costs. Plan G has become the most popular option since Plan F became unavailable to new Medicare beneficiaries in 2020.
Adding Medigap changes the Traditional Medicare value proposition considerably:
- Predictable costs: Fixed premium with minimal out-of-pocket expenses
- No networks: Use any Medicare-accepting provider nationwide
- No referrals: Direct access to specialists without authorization
- Guaranteed renewable: Cannot be canceled as long as premiums are paid
- Standardized benefits: Same coverage regardless of which insurer you choose
The combination of Traditional Medicare plus Medigap typically costs more in monthly premiums than Medicare Advantage but provides superior flexibility and potentially lower costs if you have significant healthcare needs. For comprehensive guidance on these options, residents in the Triad Area can contact Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com.
Special Situations and Unique Considerations
Certain circumstances require additional analysis when choosing between traditional Medicare vs Medicare Advantage. These special situations may make one option clearly preferable over the other.
Chronic Health Conditions
People with multiple chronic conditions often prefer Traditional Medicare for unrestricted specialist access. Managing conditions like diabetes, heart disease, or respiratory issues frequently requires seeing multiple specialists, which can be cumbersome in Medicare Advantage networks requiring referrals.
End-Stage Renal Disease (ESRD)
Individuals with ESRD now have access to Medicare Advantage plans, which wasn't previously permitted. However, dialysis patients should carefully evaluate network adequacy and ensure their dialysis center participates.
Employer or Union Coverage
If you have retiree health coverage from an employer or union, coordinate with benefits administrators before choosing Medicare options. Some retiree plans work better with Traditional Medicare, while others integrate with Medicare Advantage.
Veterans Benefits
Veterans with VA healthcare benefits can use VA facilities regardless of whether they choose Traditional Medicare or Medicare Advantage. However, VA benefits don't count toward Medicare Advantage out-of-pocket maximums.
Nursing Home Residents
People in nursing homes may have different needs regarding coverage. Traditional Medicare typically provides more flexibility for accessing different facilities and providers as care needs change.
Future Trends and Policy Developments
The landscape of traditional Medicare vs Medicare Advantage continues evolving as policies change and the healthcare system adapts. Staying informed about trends helps you anticipate how your coverage might be affected in coming years.
Medicare Advantage enrollment has grown substantially, with nearly half of all Medicare beneficiaries now enrolled in these plans. This growth reflects both the appeal of additional benefits and aggressive marketing by private insurers. Medicare policy resources provide ongoing updates about program changes.
Emerging Developments to Watch
Several trends are shaping the future of Medicare coverage:
- Expanded telehealth: Both Traditional Medicare and Medicare Advantage are increasing virtual care access
- Value-based care initiatives: Medicare Advantage plans increasingly use quality metrics and care coordination
- Supplemental benefit expansion: Medicare Advantage plans can now offer broader non-medical benefits like home modifications
- Provider participation changes: Network adequacy requirements continue evolving, particularly in rural areas
- Cost-sharing adjustments: Annual changes to premiums, deductibles, and coinsurance affect both options
Understanding these trends helps you make forward-looking decisions rather than basing choices solely on current circumstances. Healthcare needs change over time, and knowing how coverage options may evolve provides valuable perspective.
Getting Personalized Guidance
While this guide provides comprehensive information about traditional Medicare vs Medicare Advantage, your specific situation requires personalized analysis. Working with knowledgeable professionals who understand Medicare options ensures you receive guidance tailored to your healthcare needs, financial situation, and personal preferences.
Consider these factors when seeking Medicare advice:
- Unbiased recommendations: Work with advisors who represent multiple carriers and plan types
- Local expertise: Choose someone familiar with provider networks and plan availability in Greensboro, Kernersville, High Point, Winston Salem, and throughout the Triad Area
- Comprehensive review: Ensure your advisor examines your complete situation, including prescription needs and healthcare utilization
- Ongoing support: Select an advisor who provides service beyond initial enrollment for questions and annual reviews
Making confident decisions about Medicare coverage requires understanding complex rules, comparing numerous options, and projecting future needs. Education and personalized support make this process manageable rather than overwhelming. You can also explore additional insurance planning considerations by visiting moserinsurancegroup.com for information about coordinating Medicare with other coverage types.
Choosing between Traditional Medicare and Medicare Advantage represents one of the most important healthcare decisions you'll make, impacting your access to care, out-of-pocket costs, and overall healthcare experience for years to come. At Moser Insurance Group Inc, we provide clear guidance and personalized support to help individuals and families in Greensboro, Kernersville, High Point, Winston Salem, and throughout the Triad Area understand their Medicare options without pressure. Whether you need help comparing plans, understanding your coverage, or making changes during enrollment periods, our team is ready to assist. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to schedule a consultation and make confident Medicare decisions based on your unique needs.
Recent Comments