

Understanding term life insurance prices can feel overwhelming when you're trying to protect your family's financial future. The cost of coverage varies significantly based on multiple factors, and knowing what influences your premium helps you make informed decisions. Whether you're in Greensboro, Kernersville, High Point, Winston Salem, or anywhere in the Triad Area, getting clarity on pricing ensures you select the right policy without overpaying. This comprehensive guide breaks down everything that affects term life insurance prices in 2026 and helps you understand what to expect when shopping for coverage.
What Determines Term Life Insurance Prices
Multiple variables influence how insurers calculate your premium. Insurance companies assess risk differently, but certain factors remain consistent across the industry.
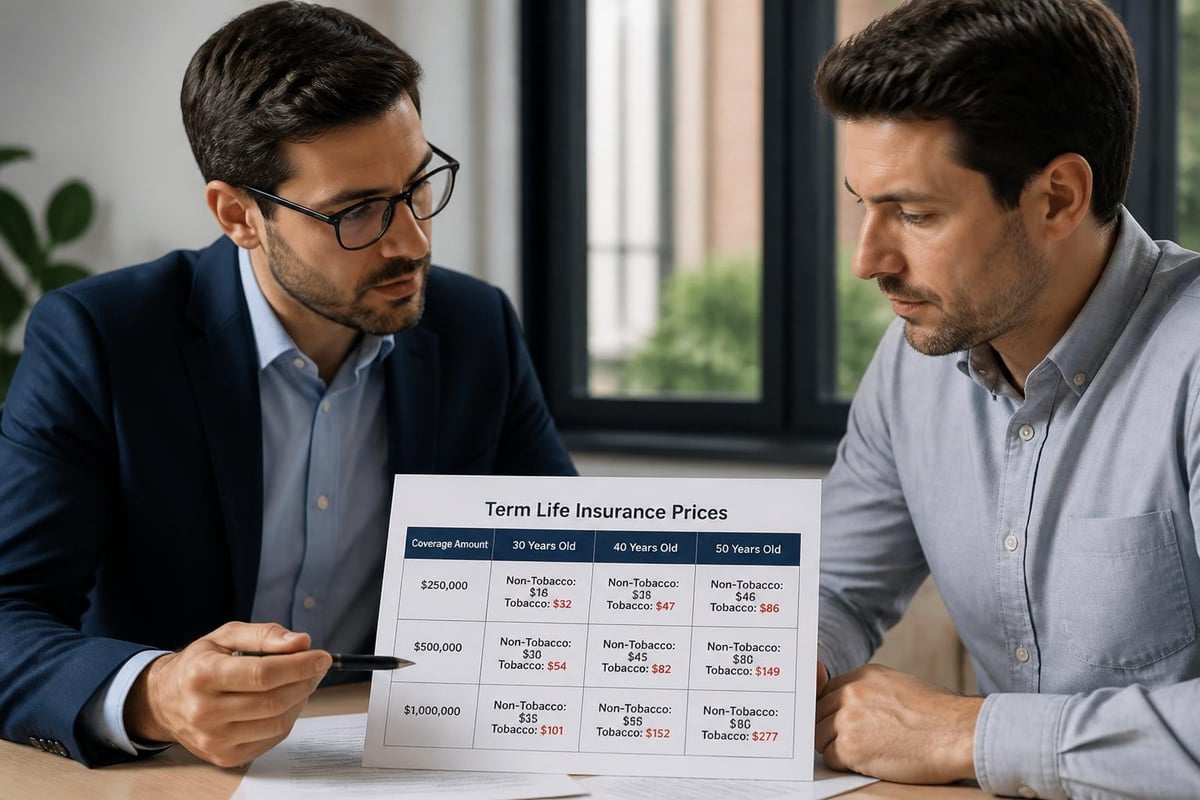
Age stands as the most significant pricing factor. Younger applicants consistently receive lower rates because they statistically present less mortality risk. A healthy 30-year-old might pay $20-30 monthly for $500,000 in coverage, while a 50-year-old could pay $100-150 for the same policy.
Health status directly impacts your premium calculation. Insurers evaluate your medical history, current conditions, and family health background. Various personal risk factors including blood pressure, cholesterol levels, and previous diagnoses all contribute to your final rate.
Medical Underwriting Components
- Complete medical history review
- Prescription medication analysis
- Family health background assessment
- Current chronic condition evaluation
- Recent hospitalization records
Lifestyle choices significantly affect term life insurance prices. Tobacco use typically doubles or triples premiums compared to non-smoker rates. Dangerous hobbies like skydiving, rock climbing, or racing can increase costs or require special riders.
Gender plays a role in pricing because women statistically live longer than men. Female applicants generally receive 10-30% lower premiums for identical coverage amounts and term lengths.
Average Term Life Insurance Costs by Age
Term life insurance prices increase predictably as you age. Understanding these patterns helps you budget appropriately and recognize fair market rates.
| Age | $250,000 (20-Year) | $500,000 (20-Year) | $1,000,000 (20-Year) |
|---|---|---|---|
| 30 | $15-20/month | $20-30/month | $35-50/month |
| 40 | $25-35/month | $40-60/month | $75-110/month |
| 50 | $65-90/month | $120-170/month | $230-320/month |
| 60 | $180-250/month | $350-480/month | $680-940/month |
These figures represent healthy non-smokers with preferred risk classifications. Average life insurance rates vary based on individual circumstances, but this table provides baseline expectations for 2026.
The cost difference between age groups illustrates why purchasing coverage earlier saves money over time. Locking in rates during your 30s or 40s preserves affordability throughout the entire term.
Coverage Amount Impact on Pricing
The death benefit you select directly correlates with your monthly premium. Higher coverage amounts mean greater insurer risk and consequently higher prices.
Common coverage tiers include:
- $100,000 – $250,000: Entry-level protection
- $250,000 – $500,000: Standard family coverage
- $500,000 – $1,000,000: Comprehensive protection
- $1,000,000+: High-net-worth planning
Most insurers offer volume discounts at certain thresholds. Purchasing $500,000 in coverage doesn't cost exactly double what $250,000 costs. The marginal cost per $1,000 of coverage typically decreases as you increase your total benefit.
Financial advisors commonly recommend coverage equal to 10-12 times your annual income. This calculation ensures your beneficiaries can replace lost income, pay off debts, and maintain their standard of living. If you're exploring options beyond term coverage, comprehensive life insurance solutions can address diverse family protection needs.
Calculating Your Coverage Needs
- Add annual income replacement needs (typically 5-10 years)
- Include outstanding mortgage balance
- Add other debts (car loans, credit cards, student loans)
- Calculate future education expenses for children
- Add final expense costs ($10,000-15,000)
- Subtract existing assets and life insurance
Policy Term Length and Price Variations
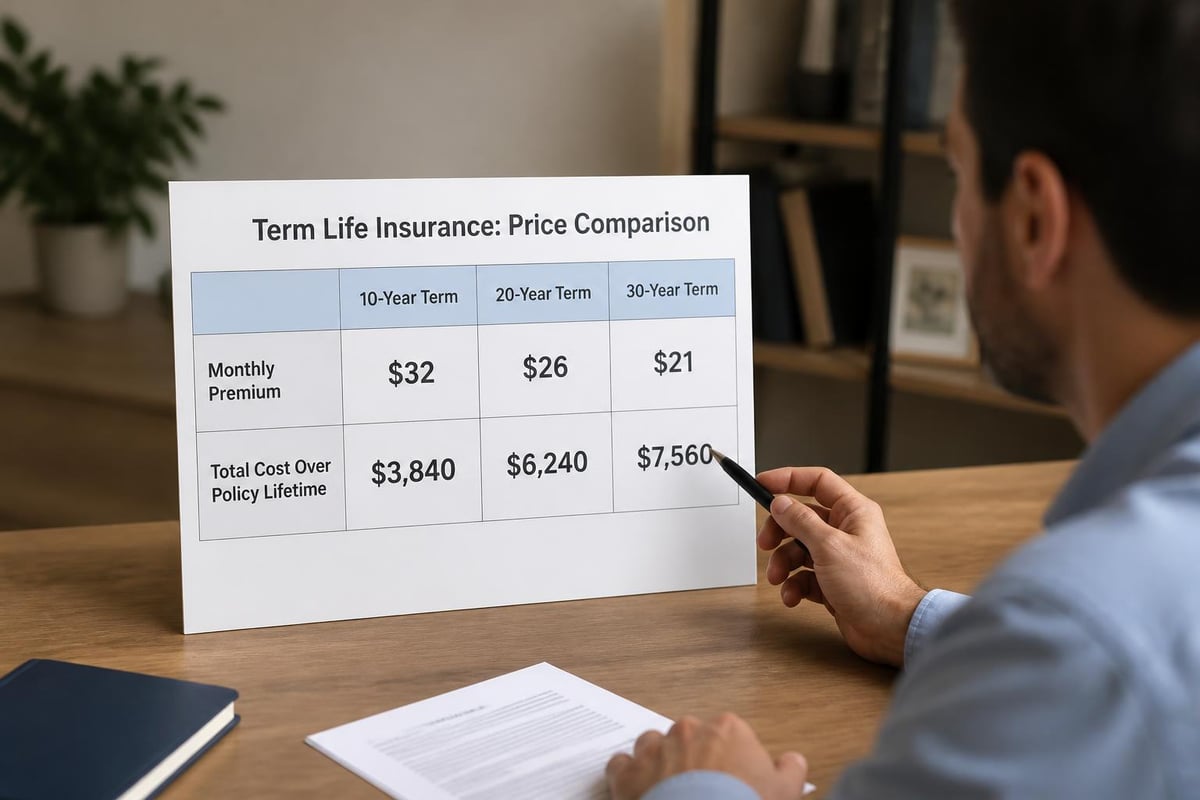
The duration of your coverage term substantially affects term life insurance prices. Longer terms mean extended risk periods for insurers, resulting in higher premiums.
Standard term options:
- 10-year terms: Lowest premiums, ideal for temporary needs
- 20-year terms: Most popular, balances cost and protection duration
- 30-year terms: Higher cost, provides coverage through peak earning years
A 40-year-old purchasing $500,000 in coverage might pay $45/month for 10 years, $60/month for 20 years, or $85/month for 30 years. The extended commitment increases total cost but maintains level premiums throughout.
Sample term life insurance rates demonstrate how term length affects pricing across different demographics. Selecting the appropriate term requires evaluating when your dependents will achieve financial independence.
Health Classifications and Premium Tiers
Insurance companies categorize applicants into risk classes that determine final pricing. Understanding these classifications helps you anticipate your probable rate category.
| Risk Class | Health Profile | Price Impact |
|---|---|---|
| Preferred Plus | Excellent health, no tobacco, ideal measurements | Lowest rates (baseline) |
| Preferred | Very good health, minor issues | 10-20% higher |
| Standard Plus | Good health, controlled conditions | 25-40% higher |
| Standard | Average health, some risk factors | 50-75% higher |
| Substandard | Significant health issues | 100-300%+ higher |
Medical underwriting examines specific metrics including:
- Blood pressure readings (target: 120/80 or lower)
- Cholesterol levels (total below 200 mg/dL)
- Body Mass Index (BMI between 18.5-24.9)
- Blood glucose levels (fasting under 100 mg/dL)
- Liver and kidney function tests
Even if you have health conditions, you can still obtain coverage. Factors that affect life insurance costs include how well managed your conditions are and your treatment compliance.
Geographic Location and Pricing Differences
Where you live influences term life insurance prices, though less dramatically than other factors. State regulations, mortality statistics, and cost-of-living variations create regional price differences.
North Carolina residents, including those in the Triad Area, typically enjoy competitive rates compared to national averages. The state's relatively lower cost of living and favorable insurance regulations contribute to reasonable premiums.
Regional considerations affecting prices:
- State insurance department regulations
- Local mortality and morbidity statistics
- Regional healthcare costs
- State-specific taxation on insurance products
- Competition among carriers in the area
Residents of Greensboro, Kernersville, High Point, and Winston Salem benefit from access to numerous carriers offering competitive rates. Working with local professionals who understand regional market conditions helps you secure optimal pricing.
Tobacco Use and Premium Surcharges
Tobacco use represents one of the most significant term life insurance prices factors. Smokers pay substantially more because tobacco-related health risks dramatically increase mortality probability.
Tobacco user rates typically:
- Cost 2-3 times more than non-smoker rates
- Apply to cigarette, cigar, pipe, and chewing tobacco users
- Include vaping and e-cigarette use at most carriers
- Remain elevated for several years after quitting
Most insurers require 12-36 months of tobacco-free status before reclassifying you as a non-smoker. Some companies offer accelerated reconsideration after 12 months with verification.
If you quit smoking after purchasing a policy, contact your insurer about re-rating. The premium reduction often justifies the additional underwriting process. Nicotine testing through blood or urine samples confirms your non-smoker status.
Occupation and Hobby Risk Assessments
Your profession and recreational activities influence term life insurance prices when they involve elevated risk levels. Insurers evaluate whether your daily work or hobbies increase accident or death probability.
High-Risk Occupations
- Commercial pilots and aviation professionals
- Construction workers and roofers
- Law enforcement and firefighters
- Offshore oil rig workers
- Logging and forestry workers
- Commercial fishermen
High-risk workers don't automatically face denials, but premiums increase to reflect elevated danger. Some insurers specialize in covering specific professions, offering better rates than general market carriers.
Adventurous Hobby Considerations
Dangerous recreational activities trigger additional underwriting scrutiny:
- Skydiving and BASE jumping
- Rock climbing and mountaineering
- Scuba diving beyond recreational depths
- Auto or motorcycle racing
- Private aviation piloting
Occasional participation versus regular engagement matters. Annual vacation scuba diving affects pricing differently than weekly deep-sea diving. Insurers may add flat extra charges ($2-5 per $1,000 of coverage) or percentage-based surcharges.
Driving Record Impact on Premiums
Your motor vehicle record influences term life insurance prices because driving behavior indicates overall risk management. Multiple violations or DUI convictions suggest higher mortality risk.
Driving infractions that affect rates:
- DUI/DWI convictions within 5-7 years
- Multiple speeding tickets (3+ in 3 years)
- Reckless driving citations
- License suspensions or revocations
- At-fault accidents with injuries
A single minor speeding ticket rarely impacts pricing. However, patterns of risky driving behavior trigger premium increases or temporary coverage postponements. Serious violations like DUI can double premiums or require waiting periods before approval.
Maintaining a clean driving record for several years can qualify you for reconsideration at standard rates. Insurance companies typically review records from the past 5-7 years during underwriting.
How Medical Conditions Affect Pricing
Pre-existing health conditions don't automatically disqualify you from coverage, but they do affect term life insurance prices. Health considerations play a major role in premium calculations across all carriers.
Well-Managed Conditions
- Controlled hypertension with medication
- Type 2 diabetes with good A1C levels
- Treated depression or anxiety disorders
- Asthma without hospitalizations
- Previous cancer with years in remission
Documentation proving condition management through medication compliance, regular checkups, and stable test results improves your risk classification. Providing comprehensive medical records helps underwriters see the full picture.
Conditions Requiring Special Consideration
Certain diagnoses trigger more intensive underwriting:
- Recent heart attack or stroke (typically 2-5 year waiting period)
- Active cancer treatment or recent diagnosis
- Severe mental health conditions
- Autoimmune disorders with complications
- Uncontrolled chronic conditions
Even with serious health issues, coverage options exist. Some insurers specialize in higher-risk applicants, offering guaranteed issue or simplified underwriting products. These policies cost more but provide necessary protection when traditional underwriting isn't possible.
Policy Features and Rider Costs
Additional policy features and riders customize your coverage but increase term life insurance prices. Understanding optional enhancements helps you balance comprehensive protection with budget constraints.
| Rider Type | Function | Typical Cost |
|---|---|---|
| Accelerated Death Benefit | Access death benefit if terminally ill | Often included free |
| Waiver of Premium | Continues coverage if disabled | 5-10% of base premium |
| Child Term Rider | Covers all children in household | $50-100/year |
| Accidental Death Benefit | Doubles payout for accidental death | 10-15% of base premium |
| Return of Premium | Refunds premiums if you outlive term | 30-100% higher premium |
Conversion privileges allow you to convert term coverage to permanent insurance without additional underwriting. This valuable feature typically costs nothing extra but provides future flexibility if your needs change.
Consider which riders provide genuine value for your situation. Return of premium riders significantly increase costs and may not offer the best value compared to investing the difference separately.
Comparing Quotes and Shopping Strategies
Getting multiple quotes remains essential for finding competitive term life insurance prices. Rate variations between carriers for identical coverage can reach 30-50% even for similar applicants.
Effective Quote Comparison Steps
- Request quotes from at least 3-5 carriers
- Ensure identical coverage amounts and term lengths
- Verify what's included in quoted premiums
- Check financial strength ratings (A- or better)
- Review customer service reputation and claim payment history
Independent agents access multiple carriers simultaneously, streamlining the comparison process. They identify which insurers prefer your specific risk profile, improving your approval odds at preferred rates.
Timing matters when shopping for coverage. Birthdays trigger age-bracket increases, making coverage more expensive. Applying before your next birthday can lock in lower rates. For those exploring term life insurance options, working with knowledgeable professionals ensures you understand all available choices.
Understanding Level Premium Structures
Term life insurance typically features level premiums that remain constant throughout the entire term. This predictability helps with long-term budgeting and financial planning.
Level premium advantages:
- Fixed monthly or annual costs
- Protection against inflation and aging
- Simplified budget planning
- No surprise increases during term
Some policies offer annual renewable term structures where premiums increase each year. These products cost less initially but become prohibitively expensive as you age. Level premium term policies provide superior long-term value despite higher starting costs.
When your term expires, renewal rates jump dramatically because you're now significantly older. Planning your coverage duration carefully prevents facing renewal at ages when term life insurance prices become unaffordable.
Application Process and Rate Locking
Understanding the application timeline helps you secure favorable term life insurance prices before rate increases. The process typically takes 4-8 weeks from application to policy delivery.
Standard Application Timeline
- Initial application (Day 1-3): Complete application and schedule medical exam
- Medical examination (Day 5-10): Paramedical professional collects measurements, blood, and urine
- Underwriting review (Day 15-35): Insurer reviews medical records and test results
- Rate offer (Day 30-40): Company presents final classification and premium
- Policy delivery (Day 40-60): Coverage begins after accepting offer and paying first premium
Most carriers allow rate locking for 60-90 days from application. This protection ensures quoted rates remain valid even if you have a birthday during underwriting. However, health changes during this period can affect your final classification.
Accelerated or simplified underwriting options expedite this timeline, sometimes providing approval within 24-48 hours. These programs suit healthy applicants seeking smaller coverage amounts, though pricing may be slightly higher than traditional underwriting.
Women's Term Life Insurance Pricing
Female applicants consistently receive lower term life insurance prices than similarly situated male applicants. Actuarial data shows women live approximately 5-7 years longer than men on average.
Gender-based price differences:
- Women pay 20-30% less for identical coverage
- Mortality advantage persists across all age groups
- Gap widens slightly with age
- Health status remains most important factor regardless of gender
A 40-year-old woman purchasing $500,000 in 20-year coverage might pay $55/month, while a 40-year-old man with identical health characteristics could pay $75/month. These differences reflect statistical longevity patterns rather than discrimination.
Some states prohibit gender-based pricing for certain insurance types, but life insurance remains exempt because gender represents a scientifically valid mortality predictor.
Renewal Options and Guaranteed Convertibility
What happens when your term ends significantly impacts long-term financial planning. Understanding renewal and conversion options prevents coverage gaps at critical times.
End-of-term options:
- Let policy expire (no further obligations)
- Renew at attained age rates (extremely expensive)
- Convert to permanent insurance (no medical exam required)
- Purchase new term policy (requires new underwriting)
Guaranteed conversion rights let you transition to whole life or universal life coverage without health questions. This feature proves invaluable if you develop serious health conditions during your term but still need permanent coverage.
Conversion deadlines vary by carrier, typically allowing conversion anytime during the term or within the final 5 years. Exercise this option before the deadline expires to preserve your insurability rights.
Working with Insurance Professionals
Navigating term life insurance prices becomes simpler with professional guidance. Independent agents provide unbiased recommendations because they represent multiple carriers rather than a single company.
Professional guidance benefits:
- Access to wholesale rates not available direct
- Expertise matching your profile to preferred carriers
- Application preparation reducing underwriting delays
- Advocacy during underwriting questions or complications
- Ongoing service for beneficiary changes and questions
Insurance professionals familiar with the Triad Area understand regional considerations affecting coverage decisions. Whether you're in Greensboro, Kernersville, High Point, or Winston Salem, local expertise ensures you receive personalized recommendations.
For personalized assistance understanding how different factors affect your specific situation, you can reach out at 336-862-1763 or via email at moserinsurancegroup@gmail.com. Professional guidance clarifies complex pricing structures and helps you avoid overpaying.
Policy Illustrations and Premium Projections
Insurance companies provide policy illustrations showing projected costs and benefits over time. Reading these documents carefully prevents misunderstandings about what you're purchasing.
Key Illustration Components
- Guaranteed premium amounts
- Death benefit payouts
- Policy duration and expiration date
- Conversion options and deadlines
- Rider costs broken out separately
Illustrations for term policies are straightforward compared to permanent insurance. Verify that premiums remain level throughout the stated term and understand what happens at term expiration.
Ask questions about any aspect you don't fully understand. Reputable agents welcome inquiries and provide clear explanations. Never purchase coverage based on pressure or urgency tactics-legitimate offers remain available after thorough consideration.
Medical Exam Preparation Tips
The paramedical examination significantly impacts your health classification and final term life insurance prices. Strategic preparation optimizes your test results and potentially improves your rate class.
Exam preparation recommendations:
- Schedule morning appointments when possible
- Fast 8-12 hours before blood work (water allowed)
- Avoid alcohol for 24-48 hours prior
- Skip caffeine on exam day
- Get adequate sleep the night before
- Drink plenty of water to aid blood draw
- Avoid strenuous exercise 24 hours before
These steps help ensure accurate readings that reflect your normal health status. Unusual stress or poor preparation can temporarily elevate blood pressure or blood sugar, potentially affecting your classification.
Bring a list of current medications, dosages, and prescribing physicians. Complete medication disclosure prevents delays when underwriters request additional information from your doctors.
Understanding Guaranteed Issue Alternatives
When traditional underwriting isn't feasible due to serious health conditions, guaranteed issue term life insurance provides coverage without medical questions. However, this convenience comes with significantly higher term life insurance prices.
| Feature | Traditional Term | Guaranteed Issue |
|---|---|---|
| Medical Exam | Required | None |
| Health Questions | Extensive | None or minimal |
| Coverage Amounts | Up to $5M+ | Typically $25K-50K max |
| Pricing | Based on health | Significantly higher |
| Graded Benefits | Full from day one | Often 2-3 year waiting period |
Guaranteed issue products suit individuals with terminal diagnoses, recent major health events, or multiple declined applications. The graded death benefit means natural death during the first 2-3 years returns only premiums paid plus interest.
These products serve specific purposes but shouldn't be your first choice if you qualify for traditionally underwritten coverage. The price premium often reaches 200-400% compared to standard policies.
Understanding term life insurance prices empowers you to make confident coverage decisions that protect your family without overpaying. The factors influencing your premium-from age and health to coverage amount and term length-interact in ways that create unique pricing for every applicant. Whether you're in Greensboro, Kernersville, High Point, Winston Salem, or anywhere in the Triad Area, Moser Insurance Group Inc provides clear guidance and personalized support to help you navigate your options. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com to discuss your family's protection needs without pressure.
Recent Comments