
Navigating the healthcare landscape in 2026 requires understanding that traditional health insurance doesn't always cover everything. Medical bills can accumulate quickly, even with comprehensive primary coverage. That's where supplemental insurance plans for individuals become valuable financial tools. These specialized policies work alongside your existing health coverage to pay for expenses that fall through the cracks, offering an extra layer of protection when unexpected health issues arise. Whether you're dealing with high deductibles, significant copayments, or services your primary insurance doesn't fully cover, supplemental plans can provide the financial breathing room families need during medical challenges.
Understanding How Supplemental Coverage Works
Supplemental insurance plans for individuals function differently from traditional health insurance. Rather than replacing your primary coverage, they complement it by addressing specific gaps.
Traditional health insurance pays doctors and hospitals directly based on negotiated rates. Supplemental plans typically pay you directly in cash, giving you flexibility to use the money wherever you need it most.
This fundamental difference changes how you approach medical expenses:
- You receive predetermined cash benefits based on specific medical events
- Funds can cover deductibles, copays, transportation, or household bills
- Benefits are paid regardless of what your primary insurance covers
- No network restrictions limit where you seek care
The financial assistance these plans provide often makes the difference between manageable medical bills and financial hardship. When you're hospitalized or diagnosed with a serious condition, supplemental insurance can cover various out-of-pocket costs that your primary plan leaves behind.
Common Types of Supplemental Policies
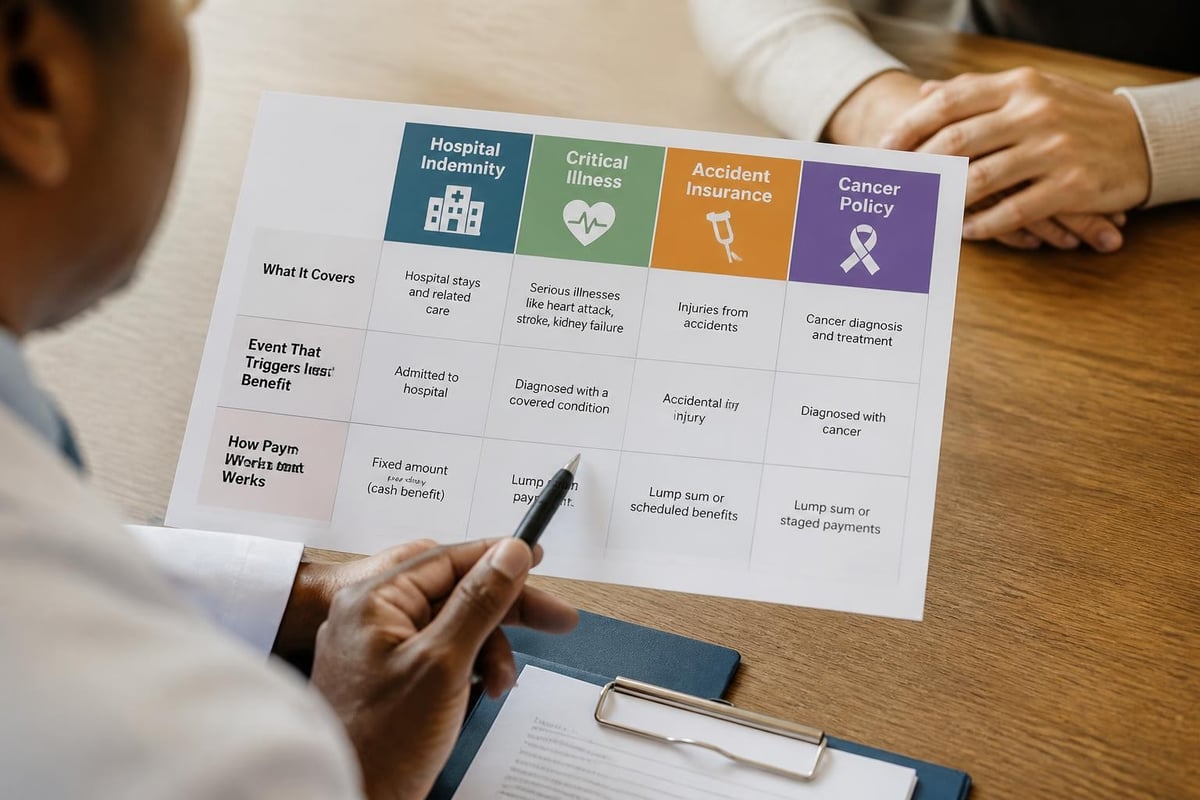
The supplemental insurance market offers several distinct policy types, each designed for specific scenarios:
| Policy Type | What It Covers | Best For |
|---|---|---|
| Hospital Indemnity | Daily cash for hospital stays, ICU visits, admissions | High-deductible health plans |
| Critical Illness | Lump sum upon diagnosis of covered conditions | Cancer, heart attack, stroke protection |
| Accident Insurance | Injuries from accidents, ER visits, fractures | Active individuals, families with children |
| Cancer Insurance | Specific to cancer diagnosis and treatment | Family history of cancer |
| Gap Insurance | Fills specific coverage gaps | Those with limited primary coverage |
Each policy serves a different purpose, and many individuals choose to combine multiple types based on their health risks and financial situation.
Why Individuals Need Supplemental Protection
Healthcare costs continue rising throughout the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem. Even people with solid employer-sponsored insurance or marketplace plans face significant out-of-pocket expenses.
The reality of modern healthcare spending:
Americans with health insurance still pay substantial amounts from their own pockets. Deductibles have climbed steadily over the past decade. A typical family health plan now requires several thousand dollars in out-of-pocket spending before insurance covers most expenses.
Beyond deductibles, consider these additional costs:
- Copayments for specialist visits ($40-$75 per visit)
- Coinsurance percentages (typically 20% of allowed amounts)
- Prescription drug costs not fully covered
- Services outside your network
- Medical equipment and supplies
When serious illness strikes, these expenses compound quickly. A cancer diagnosis might require months of treatment with frequent specialist appointments, imaging studies, and medications. Even with excellent primary coverage, the financial burden can become overwhelming.
The Hidden Costs of Medical Events
Medical bills represent only part of the financial impact when health problems occur. Supplemental insurance plans for individuals address the broader economic consequences of illness or injury.
Non-medical expenses that affect families:
- Lost income from missed work during treatment or recovery
- Transportation costs for frequent medical appointments
- Childcare expenses when parents attend lengthy treatments
- Household help needed during recovery periods
- Lodging near treatment facilities for specialized care
- Meal expenses during hospital stays or treatment days
These supplemental costs rarely appear in insurance calculations, yet they create real financial strain. The cash benefits from supplemental policies provide flexible funds to address whatever needs arise, without restriction or prior approval.
Medicare Beneficiaries and Supplemental Needs
For those enrolled in Original Medicare, supplemental coverage takes on special importance. Medicare Part A and Part B leave significant gaps that beneficiaries must cover themselves.
Medicare Supplement plans (Medigap) represent one solution, helping cover deductibles, copays, and coinsurance that Original Medicare doesn't pay. These standardized plans provide predictable coverage for Medicare's out-of-pocket costs.
However, Medicare beneficiaries might also benefit from other supplemental insurance plans for individuals:
- Hospital indemnity plans provide cash for extended hospital stays
- Cancer insurance supplements Medicare's cancer treatment coverage
- Critical illness policies offer lump sums for serious diagnoses
The combination of Medicare, a Medigap plan, and additional supplemental coverage creates comprehensive protection against medical expenses. Understanding the rules for making coverage changes helps beneficiaries make informed decisions about their supplemental protection.
Evaluating Your Need for Supplemental Coverage
Determining whether supplemental insurance plans for individuals make sense requires honest assessment of your financial situation and health risks.
Financial Risk Assessment
Start by examining your current health coverage and financial reserves:
Calculate your maximum out-of-pocket exposure:
- Annual deductible amount
- Out-of-pocket maximum
- Average copays and coinsurance for your typical healthcare use
- Prescription drug costs
Evaluate your emergency savings:
- Could you pay your full deductible today without hardship?
- Do you have funds to cover your out-of-pocket maximum?
- Would a month without income create financial crisis?
If your emergency fund falls short of your potential medical expenses, supplemental coverage deserves serious consideration. The monthly premium represents predictable, manageable costs that prevent catastrophic financial surprises.
Health History and Risk Factors
Your personal and family health history influences which supplemental plans offer the most value:
- Family history of cancer, heart disease, or stroke suggests critical illness coverage
- Active lifestyle or physically demanding work makes accident insurance practical
- Chronic conditions requiring hospitalization points toward hospital indemnity plans
- High-deductible health plans benefit most from gap coverage
Major carriers like Anthem and Aetna offer various supplemental options tailored to different risk profiles and budget constraints.
Selecting the Right Supplemental Plan
Shopping for supplemental insurance plans for individuals requires understanding policy details and comparing coverage features systematically.
Key Features to Compare
When evaluating different policies, focus on these essential elements:
Benefit amounts and triggers:
- How much does the policy pay per occurrence?
- What specific medical events activate benefits?
- Are there waiting periods before coverage begins?
- Do benefits increase or decrease over time?
- What exclusions or limitations apply?
Premium structure:
- Fixed monthly cost or age-based increases?
- Guaranteed renewal provisions
- Rate stability history of the insurer
- Available discounts for multiple policies
Claim process:
- How quickly does the company pay claims?
- What documentation is required?
- Can you file claims online or by phone?
- Does the insurer have a reputation for fair claims handling?
These factors directly impact the value you receive from your supplemental coverage. Comprehensive reviews of supplemental plans can help you understand how different insurers structure their policies.
Budget Considerations
Supplemental insurance adds to your monthly expenses, so affordability matters. However, the cost should be weighed against potential financial exposure.
Monthly premium vs. potential benefits:
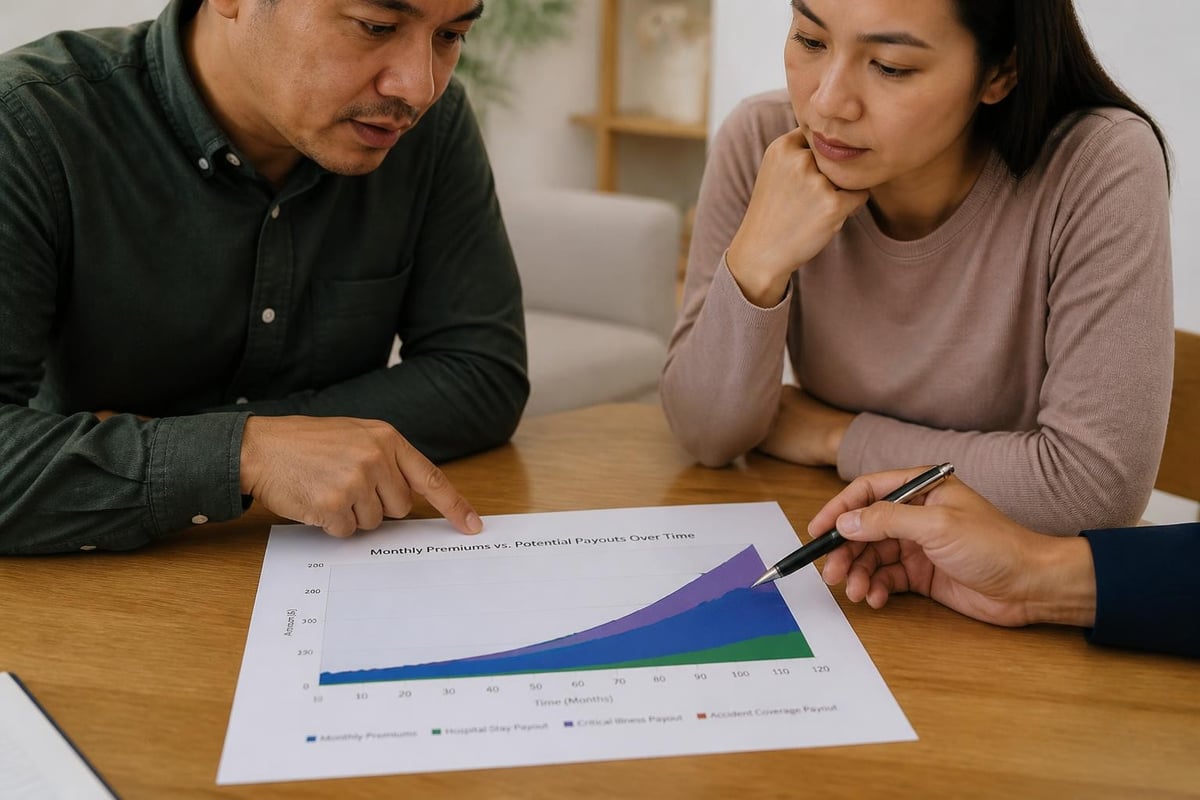
A hospital indemnity plan might cost $30-$50 monthly but pay $200-$500 daily during hospitalization. A five-day hospital stay could generate $1,000-$2,500 in benefits, far exceeding annual premiums.
Critical illness policies often cost $50-$150 monthly depending on age and coverage amount. A $20,000 benefit upon cancer diagnosis provides substantial financial relief during treatment, covering income loss and extra expenses primary insurance doesn't address.
Calculate the break-even point for each policy type you consider. How many benefit events would justify the premium cost? For most supplemental plans, even a single qualifying event provides strong return on premium investment.
Common Misconceptions About Supplemental Coverage
Several myths persist about supplemental insurance plans for individuals, sometimes preventing people from obtaining valuable protection.
"I have good health insurance, so I don't need supplemental coverage."
Even excellent health insurance leaves gaps. High deductibles, copayments, and services not covered by primary plans create out-of-pocket expenses. Supplemental plans address these specific gaps.
"Supplemental insurance is too expensive."
Premium costs vary widely based on coverage type, benefit amounts, and your age. Many supplemental plans cost less than people spend on coffee or streaming services monthly. The question isn't whether you can afford supplemental coverage, but whether you can afford to go without it when medical expenses arise.
"The claims process is too complicated."
Modern supplemental insurers have streamlined claims processing significantly. Many companies offer mobile apps for claim submission, requiring only basic documentation like hospital discharge papers or diagnosis confirmation.
"These plans don't pay much anyway."
Benefit amounts depend on the policy you choose. Hospital indemnity plans can pay thousands of dollars for a single hospitalization. Critical illness policies often provide $10,000-$50,000 lump sum payments. Accident policies cover emergency room visits, imaging studies, and follow-up care.
Working With Insurance Professionals
Navigating supplemental insurance options becomes easier with professional guidance. Independent insurance agents offer several advantages over trying to research and compare policies alone.
Benefits of professional assistance:
- Access to multiple carriers and policy options
- Expertise in matching coverage to your specific needs
- Help understanding policy language and exclusions
- Assistance with claims when medical events occur
- Ongoing service as your needs change over time
In the Triad Area, including communities throughout Greensboro, Kernersville, High Point, and Winston Salem, working with a knowledgeable local agent ensures you understand how different supplemental plans work together with your existing coverage.
Questions to Ask Your Agent
When discussing supplemental insurance plans for individuals with an insurance professional, ask these important questions:
- Which policy types best address my specific coverage gaps?
- How do these plans coordinate with my current health insurance?
- What exclusions or limitations should I be aware of?
- How stable are the premiums, and what rate increases should I expect?
- Which carriers have the best claims payment records?
- Can I adjust coverage amounts as my needs change?
- Are there policy combinations that provide better value than single plans?
Honest answers to these questions help you make informed decisions without pressure or confusion. Education should drive your insurance choices, not sales tactics.
Coordination with Existing Coverage
Understanding how supplemental insurance plans for individuals work alongside your primary health coverage prevents confusion and maximizes benefits.
How Policies Work Together
Your primary health insurance processes claims first, determining what they'll pay based on your plan's terms. After primary insurance pays, you submit documentation to your supplemental carrier.
The typical coordination sequence:
- Medical service occurs (hospitalization, diagnosis, accident)
- Provider bills your primary health insurance
- Primary insurance processes the claim and pays their portion
- You receive explanation of benefits showing what you owe
- You file a claim with your supplemental carrier
- Supplemental policy pays benefits directly to you based on the qualifying event
This coordination means you receive benefits from supplemental plans regardless of what your primary insurance pays. The supplemental policy isn't paying the medical bill directly; it's compensating you for the financial impact of the medical event.
Disclosure and Premium Considerations
Most supplemental policies don't require medical underwriting if purchased during specific enrollment periods or through employer groups. Individual policies purchased outside these windows might require health questions or medical exams.
Pre-existing condition limitations vary by policy type and state regulations. Some supplemental plans include waiting periods before they'll pay benefits for conditions you had when purchasing coverage. Understanding these limitations before purchase prevents disappointment when filing claims.
Specialized Supplemental Options
Beyond the common types of supplemental insurance, several specialized options serve specific populations or needs.
Dental and vision insurance:
While technically supplemental to medical coverage, dental and vision policies address expenses that standard health insurance rarely covers. These plans typically pay for routine care and help with major procedures.
Final expense insurance:
Though primarily a life insurance product, final expense policies supplement other coverage by ensuring funeral and burial costs don't burden surviving family members. Small death benefits provide specific financial protection for end-of-life expenses.
Long-term care insurance:
This specialized supplemental coverage pays for extended care needs that Medicare and traditional health insurance don't cover. Nursing home stays, assisted living, and in-home care services can cost thousands monthly, making long-term care insurance valuable for retirement planning.
Each specialized option addresses distinct financial risks. Combining multiple supplemental policies creates comprehensive protection across various health and life scenarios.
Making Your Decision
Choosing appropriate supplemental insurance plans for individuals requires balancing coverage needs, budget constraints, and personal risk tolerance.
Decision Framework
Follow this systematic approach:
Step 1: Identify your coverage gaps
Review your current health insurance carefully. What deductibles, copays, and out-of-pocket maximums apply? Which services have limited coverage or high cost-sharing?
Step 2: Assess your financial vulnerability
Calculate how medical expenses would impact your finances. Could you handle your maximum out-of-pocket costs? Would hospitalization create income loss?
Step 3: Prioritize your needs
Based on your health risks, family history, and financial situation, rank which types of supplemental coverage matter most.
Step 4: Compare specific policies
Request quotes for your top priority coverage types. Compare benefits, premiums, exclusions, and carrier reputation.
Step 5: Verify credentials
Ensure any insurer you consider has strong financial ratings and positive claims payment history. Your state insurance department can provide complaint records.
Step 6: Make an informed choice
Select coverage that provides meaningful financial protection at a sustainable premium cost. Remember that some coverage is better than none, and you can add policies as your budget allows.
When to Review Your Coverage
Supplemental insurance plans for individuals should be reviewed regularly, not just purchased and forgotten.
Annual review triggers:
- Changes to your primary health insurance coverage
- New diagnoses or health conditions
- Family additions or changes
- Income increases or decreases
- Approaching Medicare eligibility
- Retirement transitions
These life events often create new coverage needs or eliminate others. Adjusting your supplemental insurance accordingly ensures you maintain appropriate protection without paying for coverage you no longer need.
Getting Started With Supplemental Coverage
The process of obtaining supplemental insurance plans for individuals is straightforward when you work with experienced professionals who understand your needs.
Begin by gathering information about your current health coverage, including policy documents, recent explanation of benefits statements, and records of out-of-pocket medical expenses from the past year. This documentation helps identify specific gaps that supplemental coverage should address.
Contact insurance professionals in your area to discuss your situation. Prepare questions about policy types, benefit amounts, premium costs, and how different plans work together. The conversation should be educational, helping you understand options without pressure to purchase immediately.
Request written quotes for coverage you're considering. Compare the quotes side-by-side, focusing on benefit triggers, payment amounts, exclusions, and premium costs. Don't rush the decision. Take time to review materials, ask follow-up questions, and ensure you fully understand what you're purchasing.
Once you've selected appropriate coverage, complete the application process. Depending on the policy type and how you're purchasing it, you might need to answer health questions or undergo medical underwriting. Be honest and thorough in your responses to prevent coverage issues later.
After your policy activates, keep all documents in a safe, accessible location. Make sure family members know where to find your insurance information if they need to file claims on your behalf during a medical emergency.
For residents throughout the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, you can explore healthcare insurance options that work together to provide comprehensive financial protection. Understanding how different coverage types coordinate helps you build a complete insurance strategy.
Supplemental insurance plans for individuals fill critical gaps that primary health coverage leaves behind, offering financial protection when medical expenses threaten your budget and peace of mind. Whether you need help with Medicare coverage decisions, understanding how different supplemental policies work together, or finding the right combination of coverage for your situation, Moser Insurance Group Inc provides clear, pressure-free guidance tailored to your needs. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your supplemental insurance options and make confident decisions about protecting your financial health.
Recent Comments