
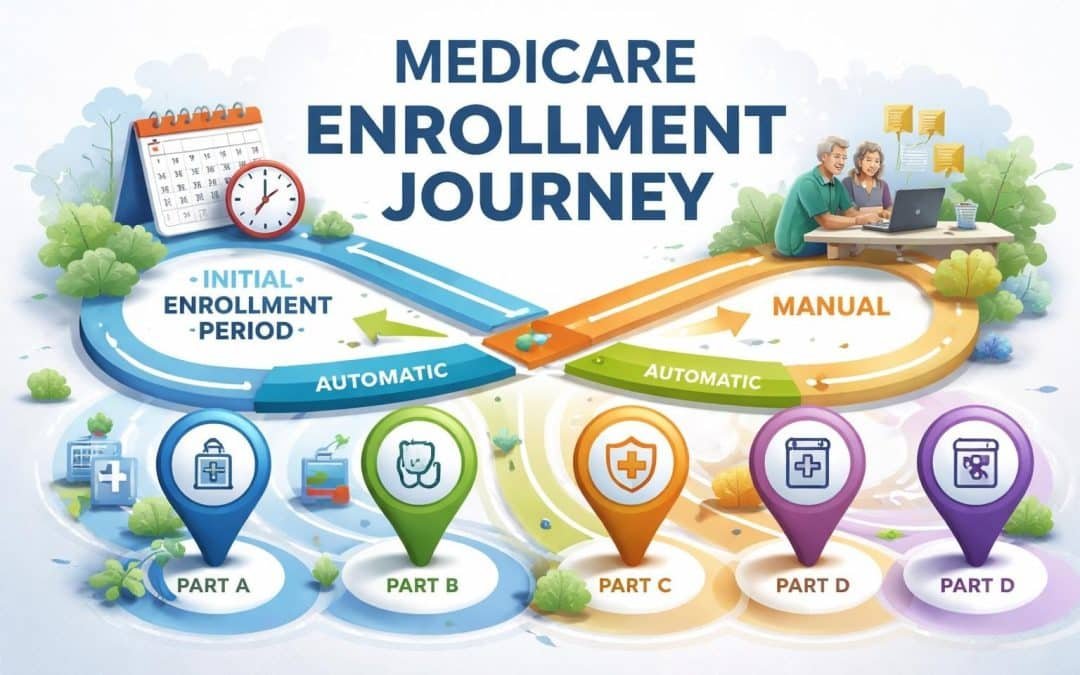
Navigating the Medicare enrollment process can feel overwhelming, especially if you're approaching your 65th birthday or transitioning from employer coverage. Understanding when and how to register for Medicare is essential to ensure continuous healthcare coverage and avoid unnecessary penalties that could increase your monthly premiums for years to come. Whether you live in Greensboro, Winston Salem, High Point, Kernersville, or anywhere across the Triad Area, the enrollment process remains consistent, but the choices you make can significantly impact your healthcare costs and coverage quality.
Understanding Medicare Eligibility Requirements
Before you can register for Medicare, you need to determine if you meet the eligibility criteria. Most Americans become eligible at age 65, but certain circumstances allow for earlier enrollment.
Standard eligibility requirements include:
- Being 65 years or older and a U.S. citizen or legal resident who has lived in the United States for at least five consecutive years
- Receiving Social Security Disability Insurance (SSDI) for 24 months, regardless of age
- Having been diagnosed with End-Stage Renal Disease (ESRD) or Amyotrophic Lateral Sclerosis (ALS)
Your work history or your spouse's work history typically determines eligibility for premium-free Part A coverage. Most people who paid Medicare taxes for at least 10 years (40 quarters) qualify for Medicare Part A without paying a monthly premium. Understanding when you qualify based on your age helps you plan your enrollment timeline effectively.
Verifying Your Eligibility Status
Contact the Social Security Administration at least three months before your 65th birthday to confirm your eligibility status. You can check your eligibility online through your my Social Security account or by calling 1-800-772-1213.
If you're already receiving Social Security benefits, you'll automatically be enrolled in Parts A and B, and you'll receive your Medicare card in the mail approximately three months before your 65th birthday. For those continuing to work past 65 with employer coverage, you may want to delay Part B enrollment to avoid paying premiums while covered elsewhere.
Critical Medicare Enrollment Periods
Timing is everything when you register for Medicare. Missing your enrollment window can result in coverage gaps and permanent late enrollment penalties.
| Enrollment Period | Timeline | Who It Applies To | Penalty Risk |
|---|---|---|---|
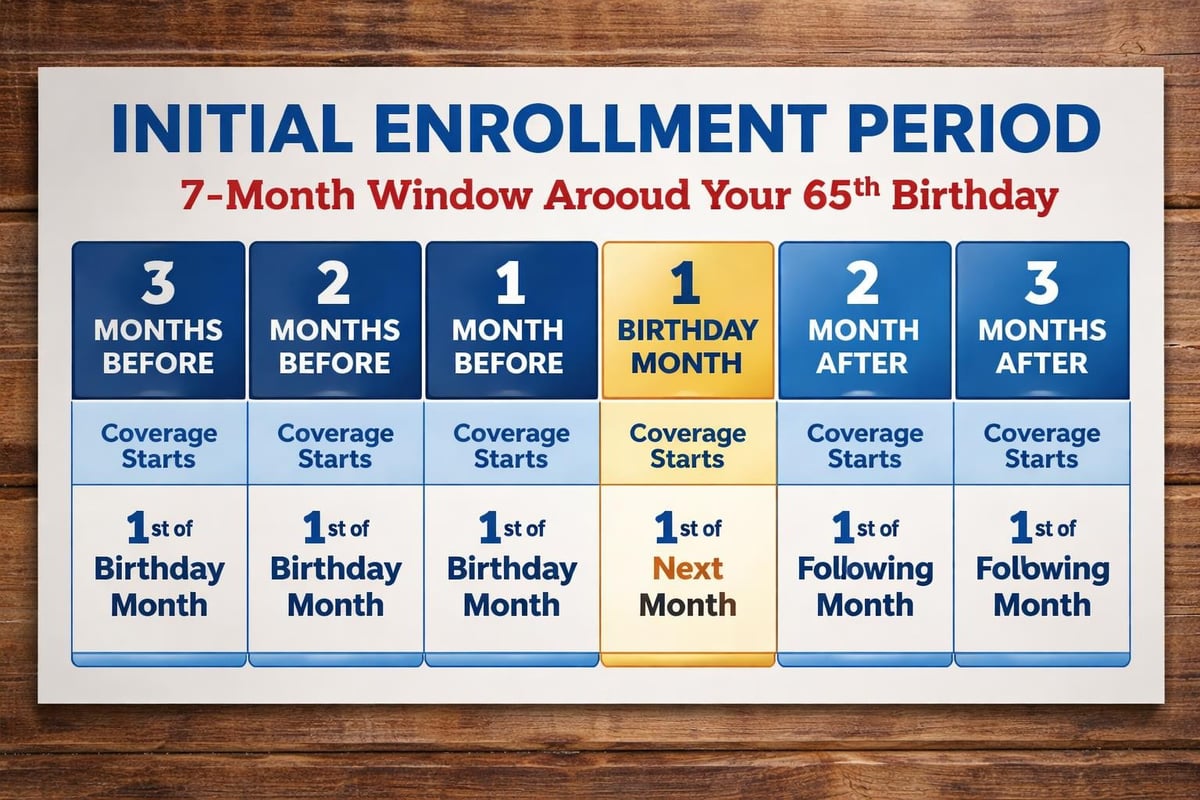
| Initial Enrollment Period (IEP) | 7 months (3 months before 65th birthday month, birthday month, 3 months after) | First-time enrollees turning 65 | Yes, if missed |
| General Enrollment Period (GEP) | January 1 – March 31 annually | Those who missed IEP | Yes, permanent penalties apply |
| Special Enrollment Period (SEP) | 8 months after employment or coverage ends | Those with employer coverage | No, if qualified |
| Annual Enrollment Period (AEP) | October 15 – December 7 annually | All Medicare beneficiaries | No (for plan changes) |
The Initial Enrollment Period represents your first opportunity to register for Medicare and typically offers the most flexibility without penalties. Getting started with Medicare basics through the official Medicare website provides comprehensive information about these enrollment windows.
Avoiding Late Enrollment Penalties
Late enrollment penalties can permanently increase your Medicare costs. If you don't sign up for Part B when first eligible and don't have creditable coverage, you'll pay a 10% penalty for each 12-month period you delayed enrollment. This penalty continues for as long as you have Medicare Part B.
Part D prescription drug coverage carries similar penalties. The monthly penalty equals 1% of the national base beneficiary premium multiplied by the number of months you went without creditable prescription coverage. Residents throughout the Triad Area should mark these enrollment dates carefully to maintain continuous coverage.
Step-by-Step Process to Register for Medicare
The registration process varies depending on your current situation and whether you're receiving Social Security benefits.
For Those Already Receiving Social Security
If you're already collecting Social Security retirement benefits, you'll automatically be enrolled in Medicare Parts A and B. You don't need to take any action to register for Medicare in this scenario.
What happens automatically:
- You'll receive your Medicare card by mail approximately three months before turning 65
- Your Part A and Part B coverage begins the first day of your birthday month
- If your birthday falls on the first day of the month, coverage starts the first day of the preceding month
You can decline Part B coverage if you have employer coverage by following the instructions included with your Medicare materials. Keep documentation of your decision in case you need to prove continuous creditable coverage later.
For Those Not Receiving Social Security
If you're not receiving Social Security benefits when you turn 65, you need to actively register for Medicare through one of three methods.
Online enrollment through the Social Security website offers the most convenient option. Visit ssa.gov and complete the Medicare application, which typically takes 10-15 minutes. You can save your application and return to it if needed.
Phone enrollment by calling Social Security at 1-800-772-1213 (TTY 1-800-325-0778) allows you to speak with a representative who can guide you through the process. Wait times vary, so call early in the morning or later in the week for shorter holds.
In-person enrollment at your local Social Security office provides face-to-face assistance. Schedule an appointment in advance to reduce wait times. For residents in Greensboro, Winston Salem, High Point, or Kernersville, locate your nearest office through the Social Security office locator.
Choosing Your Medicare Coverage Options
When you register for Medicare, you'll need to decide between Original Medicare with supplemental coverage or a Medicare Advantage plan. This decision significantly impacts your healthcare costs and provider access.
Original Medicare (Parts A and B)
Original Medicare provides comprehensive hospital and medical coverage but leaves some gaps that beneficiaries typically fill with supplemental insurance.
Part A (Hospital Insurance) covers:
- Inpatient hospital stays
- Skilled nursing facility care
- Hospice care
- Some home health services
Part B (Medical Insurance) covers:
- Doctor visits and outpatient care
- Preventive services
- Durable medical equipment
- Some home health services
Most people pay no premium for Part A if they or their spouse paid Medicare taxes for at least 10 years. Part B requires a monthly premium, which was $185 in 2026 for most beneficiaries. Higher-income earners pay Income-Related Monthly Adjustment Amounts (IRMAA) based on their tax returns from two years prior.
Medicare Advantage (Part C)
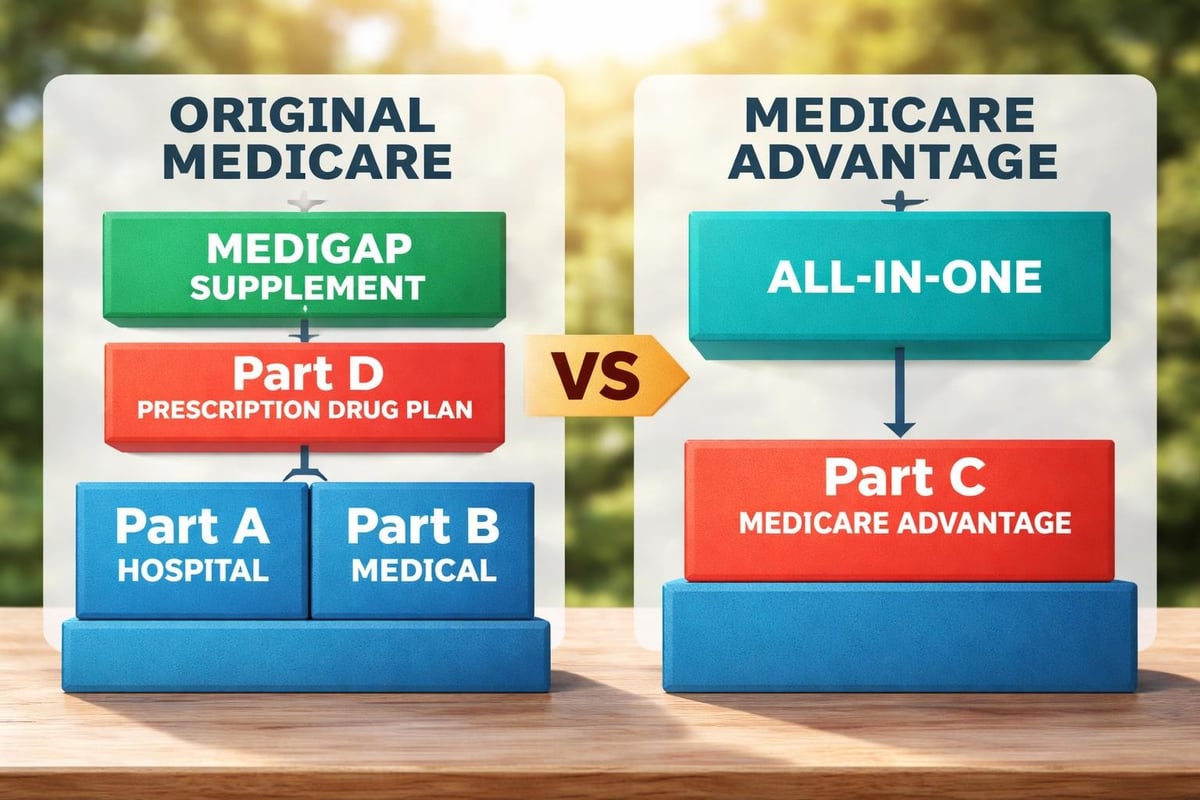
Medicare Advantage plans offer an alternative way to receive Medicare benefits through private insurance companies approved by Medicare. These plans include all Part A and Part B coverage and typically add prescription drug coverage (Part D) and extra benefits.
| Feature | Original Medicare + Supplements | Medicare Advantage |
|---|---|---|
| Provider Network | Any doctor accepting Medicare | Usually network-restricted (HMO/PPO) |
| Out-of-Pocket Maximum | No cap (unless you have Medigap) | Annual maximum limit |
| Additional Benefits | Requires separate policies | Often includes dental, vision, hearing |
| Prescription Coverage | Requires separate Part D plan | Usually included |
| Travel Coverage | Nationwide | Limited outside service area |
Understanding Medicare Advantage options in Greensboro helps local residents compare specific plans available in their area. Similarly, those in Winston Salem or High Point can explore region-specific plan options.
Registering for Prescription Drug Coverage
Part D prescription drug coverage is optional but recommended for most Medicare beneficiaries. If you don't enroll in a Part D plan when first eligible and don't have creditable prescription coverage, you may face late enrollment penalties.
Evaluating Part D Plans
Compare Part D plans based on several factors:
- Formulary coverage: Does the plan cover your specific medications?
- Pharmacy network: Are your preferred pharmacies in-network?
- Premium costs: What's the monthly premium?
- Deductible and copays: What are your out-of-pocket costs per prescription?
- Coverage gap: How does the plan handle the donut hole?
The Medicare Plan Finder tool on medicare.gov allows you to enter your prescriptions and compare actual costs across available plans in your area. This comparison tool proves invaluable during the enrollment process.
Supplementing Original Medicare with Medigap
If you choose Original Medicare when you register for Medicare, consider adding a Medigap (Medicare Supplement) policy to cover out-of-pocket costs that Parts A and B don't pay.
Medigap policies are sold by private insurance companies and follow standardized plans labeled with letters (Plan A, Plan B, Plan G, Plan N, etc.). Plan benefits are identical regardless of which insurance company sells them, but premiums vary by company and location.
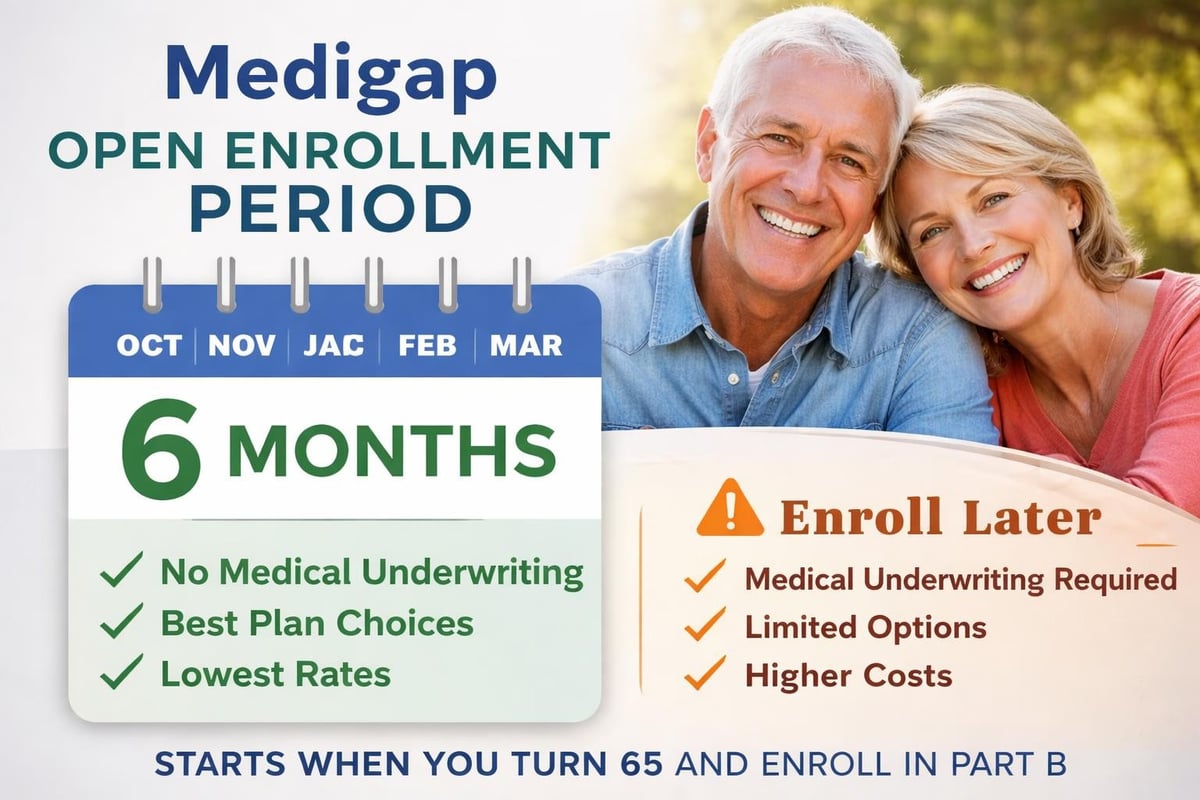
The best time to buy Medigap is during your Medigap Open Enrollment Period, which lasts six months starting the first day of the month you're both 65 or older and enrolled in Part B. During this period, you have guaranteed issue rights, meaning insurance companies cannot deny you coverage or charge higher premiums due to health conditions.
Understanding Medicare Supplement options in the Triad Area helps ensure you select appropriate supplemental coverage for your needs. Residents in specific communities can explore Kernersville Medicare supplements or Winston Salem Medicare supplements for localized assistance.
Special Situations When You Register for Medicare
Certain circumstances require special consideration during the Medicare enrollment process.
Continuing to Work Past 65
If you or your spouse continue working past 65 with employer group health coverage, you may delay Medicare enrollment without penalty. However, the employer must have 20 or more employees for the coverage to be considered creditable.
Key considerations for working seniors:
- Coordinate with your employer's benefits department to understand how Medicare works with your group plan
- Determine whether your employer requires Medicare as primary insurance
- Keep documentation of your employer coverage dates for future enrollment
- Understand your Special Enrollment Period rights when coverage ends
When your employer coverage ends, you have an 8-month Special Enrollment Period to enroll in Medicare Parts A and B without penalties. This period begins the month after employment ends or coverage ends, whichever comes first.
COBRA and Medicare
COBRA continuation coverage is not considered creditable coverage for Medicare purposes. If you're eligible for Medicare and elect COBRA instead of enrolling in Medicare during your Initial Enrollment Period, you may face late enrollment penalties when you eventually register for Medicare.
Retiree Coverage
Some employers offer retiree health benefits. Verify whether this coverage is creditable (meaning it's as good as Medicare coverage) by requesting a Certificate of Creditable Coverage from your benefits administrator. This documentation protects you from late enrollment penalties.
Getting Help When You Register for Medicare
The Medicare enrollment process involves multiple decisions with long-term financial implications. Professional guidance can help you navigate these choices confidently.
Local insurance professionals in Greensboro, Winston Salem, High Point, and Kernersville understand regional plan options and can provide personalized recommendations based on your healthcare needs, budget, and preferred providers. They offer unbiased education about your choices without pressure to select any particular option.
For turning 65 Medicare help in Greensboro, local experts can walk you through the entire registration process step by step. Similar resources exist for those turning 65 in Winston Salem or High Point.
Resources for Medicare Registration
Official government resources:
- Medicare.gov: Comprehensive information, plan comparisons, and enrollment tools
- Social Security Administration: Handles Parts A and B enrollment
- 1-800-MEDICARE (1-800-633-4227): 24/7 helpline for Medicare questions
Local assistance:
- State Health Insurance Assistance Program (SHIP): Free, unbiased Medicare counseling
- Local insurance agents: Personalized plan recommendations and enrollment assistance
- Medicare seminars: Educational events explaining enrollment and coverage options
Required Documents for Medicare Registration
Gather necessary documentation before you register for Medicare to streamline the enrollment process.
Essential documents include:
- Social Security number (yours and your spouse's if applicable)
- Birth certificate or proof of birth
- Proof of U.S. citizenship or legal residency
- Employment information if you're still working or recently retired
- Current health insurance information including policy numbers and group numbers
If you're enrolling based on disability or ESRD, additional medical documentation may be required. Contact Social Security in advance to confirm specific requirements for your situation.
After You Register for Medicare
Once you complete the enrollment process, Medicare sends your red, white, and blue Medicare card within 30 days. This card shows your Medicare number (now randomized instead of your Social Security number), coverage start dates, and which parts of Medicare you have.
Important next steps:
- Review your card carefully: Verify all information is correct, especially your coverage start dates
- Make copies: Keep photocopies of your card and store the original in a safe place
- Share with providers: Notify your doctors and pharmacies about your Medicare coverage
- Coordinate other coverage: If you have other insurance, determine coordination of benefits
Your Medicare number remains the same unless you specifically request a new card due to loss, theft, or damage. Never share your Medicare number in response to unsolicited calls or emails, as Medicare scams targeting seniors are increasingly common.
Managing Your Medicare Coverage
After enrollment, you can make changes to your coverage during specific periods. The Annual Enrollment Period (October 15 through December 7) allows you to switch between Original Medicare and Medicare Advantage, add or drop prescription drug coverage, or change your Medicare Advantage or Part D plan.
The Medicare Advantage Open Enrollment Period (January 1 through March 31) provides a second opportunity for those already in Medicare Advantage plans to switch to a different Medicare Advantage plan or return to Original Medicare.
Understanding Medicare Costs After Registration
Medicare involves several types of costs that vary based on your coverage choices and income level.
Standard Medicare costs in 2026:
- Part A: $0 premium for most people; $285 or $518 monthly premium for those who don't qualify for premium-free Part A
- Part B: $185 standard monthly premium (higher for those with income above $106,000 for individuals or $212,000 for couples)
- Part A deductible: $1,676 per benefit period
- Part B deductible: $257 annually
Part B premiums are typically deducted directly from Social Security benefits. If you're not receiving Social Security, Medicare bills you quarterly.
Medicare Advantage and Part D premiums vary by plan and location. Some Medicare Advantage plans have $0 monthly premiums beyond the Part B premium, while others charge additional monthly amounts. Part D premiums in 2026 average around $46 monthly but range significantly based on coverage levels.
Successfully navigating Medicare enrollment requires understanding your eligibility, choosing the right enrollment period, selecting appropriate coverage options, and gathering necessary documentation. Whether you're approaching your 65th birthday or transitioning from employer coverage, taking these steps methodically ensures you maintain continuous healthcare coverage without unnecessary penalties. Moser Insurance Group Inc specializes in helping individuals and families throughout Greensboro, Winston Salem, High Point, Kernersville, and the entire Triad Area understand their Medicare options through clear, personalized guidance. For assistance with your Medicare enrollment decisions, contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to schedule a no-pressure consultation.
Recent Comments