
Navigating plan enrollment can feel overwhelming, especially when you're dealing with Medicare, health insurance, or supplemental coverage options. Every year, millions of Americans face critical decisions about their healthcare coverage, and the choices they make during enrollment periods can significantly impact their financial security and access to care. Understanding the process, knowing your options, and avoiding common pitfalls are essential steps toward selecting the right plan for your needs and budget. Whether you're approaching Medicare eligibility for the first time or reassessing your current coverage, the plan enrollment process requires careful attention to detail and a clear understanding of your healthcare priorities.
Understanding the Plan Enrollment Window
Plan enrollment operates on strict timelines that vary depending on the type of coverage you're seeking. Missing these windows can result in delayed coverage, financial penalties, or limited plan options. For Medicare beneficiaries, the Annual Enrollment Period runs from October 15 through December 7 each year, allowing you to switch between Original Medicare and Medicare Advantage or change your prescription drug coverage. According to data from the Centers for Medicare & Medicaid Services, understanding these enrollment patterns helps beneficiaries make more informed decisions.
Initial Enrollment Period (IEP) is your first opportunity to sign up for Medicare, beginning three months before your 65th birthday month and extending three months after. This seven-month window is crucial because late enrollment can trigger lifetime penalties.
The Special Enrollment Period applies to qualifying life events such as:
- Moving outside your plan's service area
- Losing employer-sponsored coverage
- Qualifying for Medicaid or Extra Help
- Moving into a nursing home
- Certain chronic condition diagnoses
For those in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, understanding local plan availability becomes particularly important during these enrollment windows.
Types of Plans Available During Enrollment
Plan enrollment gives you access to various coverage options, each with distinct benefits, costs, and provider networks. Making an informed choice requires understanding how each plan type works and which aligns best with your healthcare needs.
Medicare Coverage Options
Medicare Advantage Plans bundle hospital, medical, and often prescription drug coverage into a single plan offered by private insurers. These plans frequently include additional benefits like dental, vision, and hearing coverage that Original Medicare doesn't provide.
Medicare Supplement Plans work alongside Original Medicare to cover out-of-pocket costs like deductibles, copayments, and coinsurance. These standardized plans offer predictable costs and nationwide coverage without network restrictions.
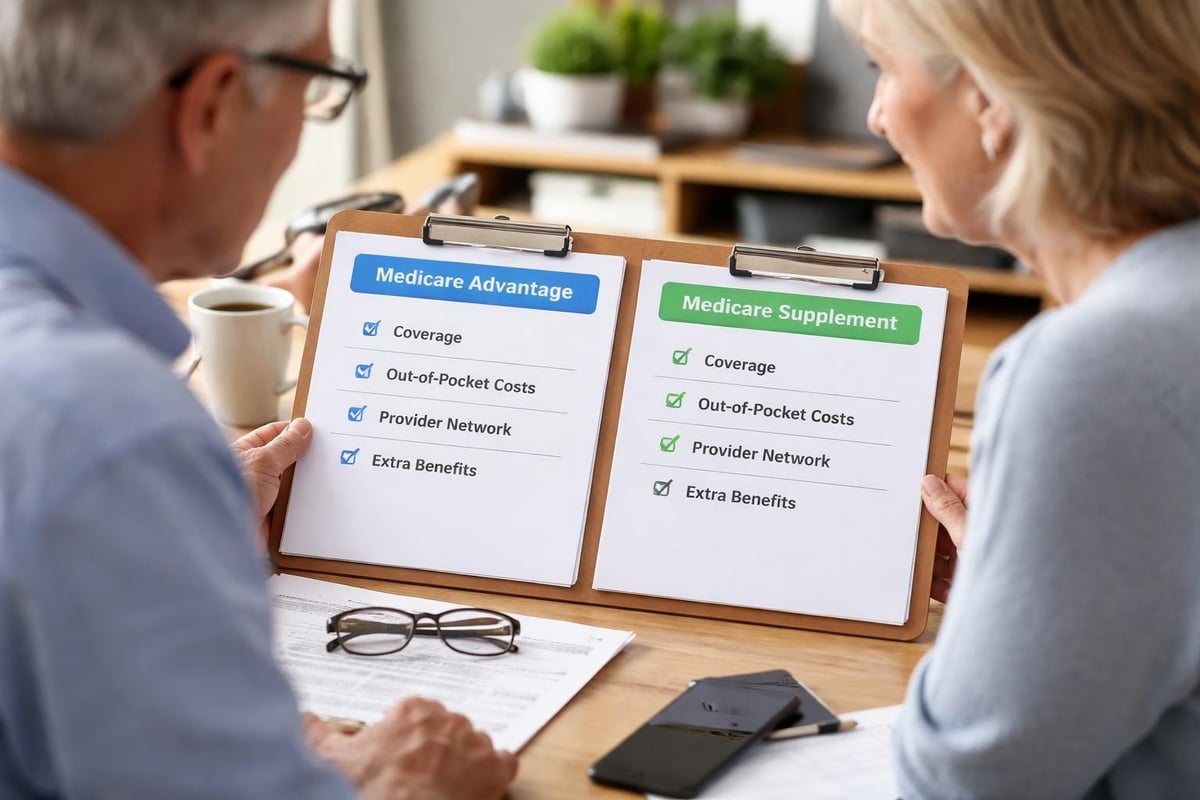
| Plan Type | Network Restrictions | Prescription Coverage | Additional Benefits | Best For |
|---|---|---|---|---|
| Medicare Advantage | Yes (HMO/PPO) | Often included | Dental, vision, hearing | Budget-conscious enrollees |
| Medicare Supplement | No restrictions | Separate Part D needed | Limited | Frequent travelers, specialist users |
| Original Medicare | No restrictions | Separate Part D needed | None | Maximum provider choice |
Health Insurance Marketplace Plans
ACA Marketplace plans operate on their own enrollment calendar, with Open Enrollment typically running from November 1 through January 15. Research published in PubMed on plan selection behaviors shows that understanding plan tiers and subsidy eligibility significantly impacts enrollment decisions.
Available metal tiers include:
- Bronze: Lowest premiums, highest out-of-pocket costs (60% actuarial value)
- Silver: Moderate premiums and costs (70% actuarial value)
- Gold: Higher premiums, lower costs when you need care (80% actuarial value)
- Platinum: Highest premiums, lowest out-of-pocket expenses (90% actuarial value)
Preparing for Successful Plan Enrollment
Preparation is the foundation of making sound enrollment decisions. Without proper documentation and research, you risk selecting a plan that doesn't meet your needs or missing out on available subsidies and benefits.
Gather Essential Documentation
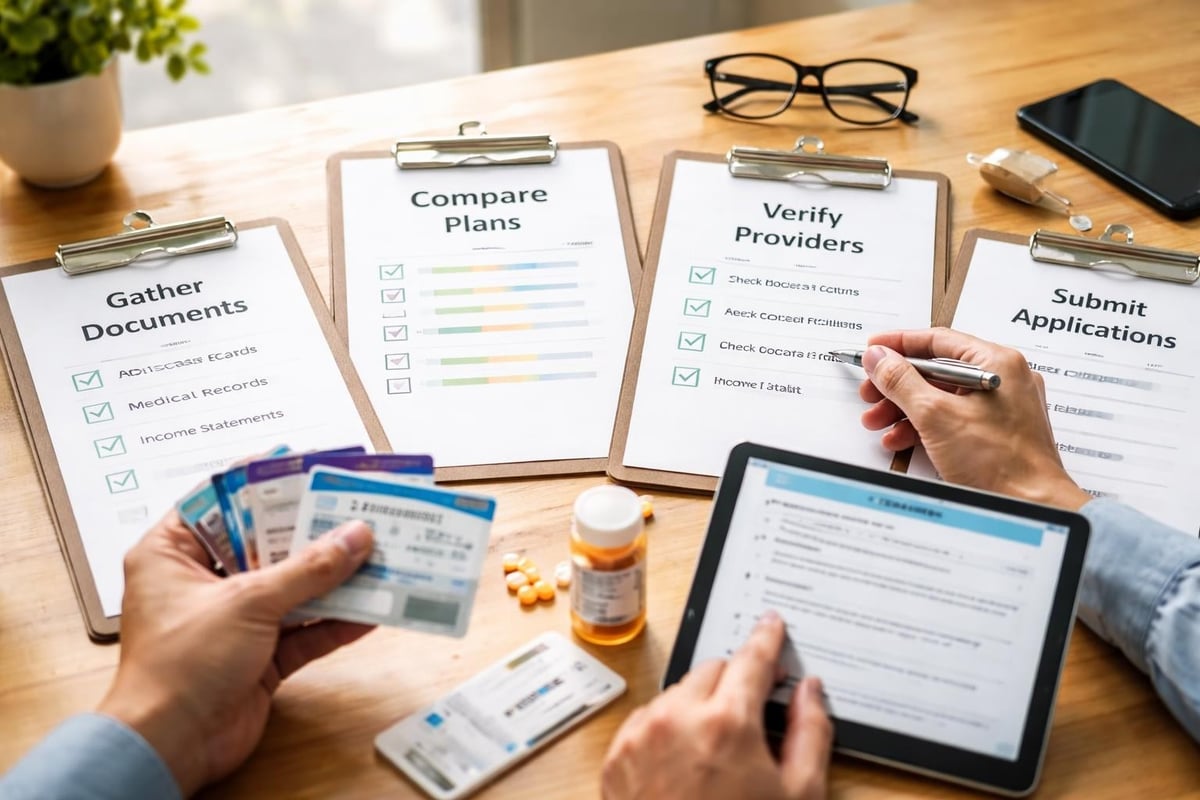
Before beginning your plan enrollment, collect the following documents:
- Social Security card and Medicare card (if applicable)
- Current prescription medications list with dosages
- Preferred doctors and specialists with contact information
- Previous year's healthcare spending records
- Income documentation for subsidy qualification
- Current insurance policy details
Assess Your Healthcare Needs
Honest evaluation of your health status and anticipated medical needs helps identify the most appropriate coverage. Consider your regular prescription medications, planned procedures, chronic conditions requiring ongoing management, and your preferred doctors and hospitals.
For personalized guidance through this assessment process in the Triad Area, contact Moser Insurance Group at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your specific situation.
Navigating the Plan Enrollment Process Step by Step
The actual enrollment process varies by plan type and provider, but following a systematic approach ensures you don't overlook critical details. Research from MedPAC on beneficiary information sources reveals that beneficiaries using multiple information sources make more confident enrollment choices.
Step One: Compare Plans
Use official comparison tools to evaluate your options. The Medicare Plan Finder at Medicare.gov allows side-by-side comparison of costs, coverage, and quality ratings. For Marketplace plans, Healthcare.gov provides similar functionality with real-time subsidy calculations.
Step Two: Check Provider Networks
Verify that your current doctors, specialists, and preferred hospitals participate in the plan's network. This step prevents unexpected out-of-network charges and ensures care continuity. Call providers directly rather than relying solely on online directories, which may contain outdated information.
Step Three: Review Prescription Coverage
Enter all your medications into the plan's drug formulary tool. Pay attention to tier placement, prior authorization requirements, and whether preferred pharmacies offer lower copays. Drug coverage can significantly impact your total annual costs.
Step Four: Calculate Total Costs
Look beyond monthly premiums to estimate your true annual expenses:
- Monthly premium × 12 months
- Annual deductible
- Expected copays and coinsurance
- Maximum out-of-pocket limit
- Prescription drug costs
Step Five: Complete Your Application
Submit your enrollment application through the official channel: Medicare.gov for Medicare plans, Healthcare.gov for Marketplace plans, or directly through the insurance carrier. Keep confirmation numbers and copies of all submitted documents.
Common Plan Enrollment Mistakes to Avoid
Even well-intentioned beneficiaries make errors during plan enrollment that can cost thousands of dollars or limit their access to care. Understanding these pitfalls helps you navigate the process more successfully.
Focusing Only on Premium Costs
The lowest-premium plan frequently carries higher deductibles, copays, and coinsurance that result in greater total costs when you need care. A comprehensive cost analysis accounting for your expected utilization provides a more accurate comparison.
Ignoring Star Ratings and Quality Measures
Medicare assigns Star Ratings from one to five based on quality and performance. Five-star Medicare Advantage plans offer superior customer service, health outcomes, and member satisfaction. These ratings reflect real-world plan performance and should factor into your decision.
Missing Enrollment Deadlines
Late enrollment in Medicare Part B triggers a 10% penalty for each 12-month period you delayed enrollment, lasting as long as you have Medicare coverage. Part D late enrollment penalties also accumulate monthly and compound over time.
Not Reviewing Coverage Annually
Your health needs, financial situation, and available plans change each year. Annual plan enrollment review ensures your coverage remains aligned with your current circumstances. Plans can modify their formularies, provider networks, and cost-sharing structures without switching plan names.
Special Considerations for Different Populations
Plan enrollment requirements and optimal strategies vary based on your specific situation. Tailoring your approach to your circumstances improves outcomes and reduces frustration.
Dual-Eligible Beneficiaries
If you qualify for both Medicare and Medicaid, you automatically receive Extra Help with prescription drug costs. Special Needs Plans (SNPs) designed for dual-eligible individuals often provide coordinated benefits and $0 premiums. Your State Health Insurance Assistance Program offers free counseling specifically for dual-eligible enrollment.
Working Past Age 65
Employer-sponsored coverage may serve as your primary insurance if you or your spouse actively works for an employer with 20+ employees. You can delay Medicare enrollment without penalties through a Special Enrollment Period when employer coverage ends. However, coordination between employer coverage and Medicare requires careful planning to avoid gaps.
Veterans with VA Benefits
VA healthcare benefits don't constitute creditable prescription drug coverage under Medicare rules. Veterans should consider enrolling in Medicare Part D during their Initial Enrollment Period to avoid late enrollment penalties, even if they primarily use VA services.
Leveraging Technology During Plan Enrollment
Digital tools have transformed the plan enrollment experience, making comparison shopping and application submission more accessible. However, technology also introduces new complexities that require digital literacy.
CMS monthly enrollment data shows that online enrollment has grown substantially, yet many beneficiaries still prefer personal assistance for complex decisions.
Online Comparison Tools
Official government websites provide unbiased plan comparison functionality. These tools allow you to:
- Filter plans by premium range and coverage type
- Enter your prescriptions for accurate cost estimates
- Check doctor and hospital network participation
- Review quality ratings and member satisfaction scores
- Save favorite plans for later review
Virtual Consultations
Many insurance professionals now offer video consultations, making personalized guidance accessible regardless of your location in Greensboro, Kernersville, High Point, Winston Salem, or the broader Triad Area. Visit moserinsurancegroup.com to schedule a consultation that fits your schedule.
Mobile Applications
Insurance carriers increasingly offer mobile apps for enrollment, claim submission, and coverage management. These apps provide on-the-go access to your plan information and often include telehealth services as an integrated benefit.
Understanding Plan Enrollment Documentation and Confirmation
Proper documentation throughout the plan enrollment process protects your interests and provides proof of coverage. According to CMS enrollment operations guidance, data accuracy directly impacts payment processing and premium calculations.
Required Forms and Paperwork
Standard enrollment forms request:
- Personal identification information
- Medicare or Social Security numbers
- Current coverage details
- Beneficiary attestations
- Premium payment method authorization
Electronic vs. Paper Enrollment
Electronic enrollment offers immediate confirmation and faster processing, typically activating coverage within days. Paper applications require 2-3 weeks for processing and carry higher error rates due to illegible handwriting or incomplete sections.
Confirming Your Enrollment
You should receive written confirmation within 10 business days of application submission. This confirmation includes:
- Effective coverage date
- Plan name and identification number
- Monthly premium amount
- Member services contact information
- Your member ID number
If you don't receive confirmation within two weeks, contact the plan directly or your enrollment counselor. Delayed confirmation may indicate application errors requiring correction before coverage begins.
The Role of Professional Guidance in Plan Enrollment
While self-directed enrollment works for some beneficiaries, professional assistance often reveals options and strategies that save money and improve coverage quality. Independent insurance professionals serve as your advocate throughout the enrollment process without charging fees for consultation.
What Insurance Professionals Provide
Licensed insurance agents specializing in Medicare and health insurance offer:
- Unbiased comparison of all available plans in your area
- Personalized recommendations based on your specific health needs
- Assistance with application completion and submission
- Ongoing support for claims issues and coverage questions
- Annual reviews to ensure continued plan appropriateness
Finding Qualified Help
Look for agents who hold active licenses in your state, represent multiple insurance carriers, and specialize in Medicare or health insurance rather than all insurance types. Professional credentials like AHIP certification demonstrate ongoing education and industry expertise.
Moser Insurance Group serves Greensboro, Kernersville, High Point, and Winston Salem with personalized plan enrollment support. Reach out at 336-862-1763 or moserinsurancegroup@gmail.com for guidance tailored to your situation.
Plan Enrollment and Life Insurance Considerations
While focusing on health coverage during plan enrollment, many people overlook complementary protection through life insurance policies. Life insurance provides financial security for your family regardless of health insurance coverage, paying tax-free benefits to beneficiaries when you pass away.
Coordinating health and life insurance enrollment ensures comprehensive protection. Some enrollment periods coincide, allowing you to address multiple coverage needs simultaneously and potentially qualify for multi-policy discounts with certain carriers.
Financial Assistance and Subsidy Programs
Understanding available financial assistance programs significantly impacts plan enrollment decisions and affordability. Multiple federal and state programs reduce premiums and out-of-pocket costs for eligible individuals.
Premium Tax Credits and Cost-Sharing Reductions
Marketplace enrollees earning 100-400% of the federal poverty level qualify for premium tax credits that lower monthly costs. Those earning under 250% of poverty level receive additional cost-sharing reductions lowering deductibles and copayments.
| Income as % of FPL | Maximum Premium as % of Income | Cost-Sharing Reduction |
|---|---|---|
| 100-150% | 0-2% | 94% actuarial value |
| 150-200% | 2-4% | 87% actuarial value |
| 200-250% | 4-6% | 73% actuarial value |
| 250-400% | 6-8.5% | None |
Medicare Savings Programs
State-administered Medicare Savings Programs pay Medicare premiums and sometimes deductibles for low-income beneficiaries. Four programs offer varying assistance levels based on income and assets, with Qualified Medicare Beneficiary (QMB) providing the most comprehensive help.
Extra Help with Prescription Costs
Medicare's Low-Income Subsidy program reduces Part D premiums, deductibles, and copayments. Automatic qualification occurs if you receive Medicaid or SSI, while others must apply through Social Security.
Post-Enrollment Actions and Next Steps
Plan enrollment doesn't end when you submit your application. Several important actions ensure smooth coverage activation and optimal plan utilization.
Verify Your Coverage Start Date
Most plan enrollment changes effective January 1 require application by December 7 of the previous year. Mid-year Special Enrollment Periods typically activate coverage the first of the month following approval.
Receive and Review Your Welcome Packet
Your new plan sends a comprehensive welcome packet containing your member ID card, Evidence of Coverage document, provider directory, and formulary. Review these materials carefully to understand your benefits and locate in-network providers.
Schedule Preventive Care
Many plans cover annual wellness visits, screenings, and vaccinations at no cost when you use in-network providers. Schedule these appointments early in your coverage year to maximize benefits and establish care relationships.
Set Up Online Account Access
Create your online member portal login to access digital ID cards, review claims, find providers, and communicate with member services. Digital access streamlines coverage management and reduces paper clutter.
Understand Your Appeal Rights
All health plans must provide clear processes for appealing coverage denials and disputing claims. Familiarize yourself with these procedures before you need them to ensure timely resolution if issues arise.
Making informed plan enrollment decisions requires understanding your options, comparing coverage carefully, and recognizing how different plans align with your unique healthcare needs and budget. Whether you're navigating Medicare for the first time or reassessing your current coverage in the Triad Area, professional guidance can help you avoid costly mistakes and find the right protection. Moser Insurance Group specializes in helping individuals and families in Greensboro, Kernersville, High Point, and Winston Salem understand their Medicare and health insurance options without pressure or confusion. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group to get personalized support for your plan enrollment decisions.
Recent Comments