

The insurance landscape has evolved significantly over recent years, making it easier than ever to secure coverage without undergoing traditional medical examinations. No physical life insurance has become increasingly popular among individuals who need quick coverage, have health concerns that might complicate traditional underwriting, or simply prefer to skip the time-consuming exam process. This type of coverage uses alternative underwriting methods that evaluate your health history through medical records, prescription databases, and detailed health questionnaires rather than requiring blood work, urine samples, or physical measurements.
Understanding No Physical Life Insurance Products
No physical life insurance refers to life insurance policies that approve coverage without requiring applicants to undergo a medical exam. These policies have gained tremendous momentum across the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, as more people seek convenient insurance solutions.
Traditional life insurance typically requires a paramedical exam where a technician visits your home or office to collect blood samples, urine samples, measure your height and weight, check your blood pressure, and review your medical history. This process can take several weeks from application to approval.
No exam policies streamline this process by:
- Eliminating the waiting period for exam scheduling
- Removing the anxiety associated with medical testing
- Accelerating approval times from weeks to days or even hours
- Providing coverage options for individuals with health conditions
Two Primary Types of No Exam Coverage
The no physical life insurance market includes two distinct categories: simplified issue and guaranteed issue policies. Understanding the differences between these options helps you select the right coverage for your specific situation.
Simplified issue policies require you to answer detailed health questions on your application. Insurers review your responses along with data from prescription databases and medical information bureaus. Progressive explains that simplified issue policies offer moderate coverage amounts with reasonable premiums for relatively healthy applicants.
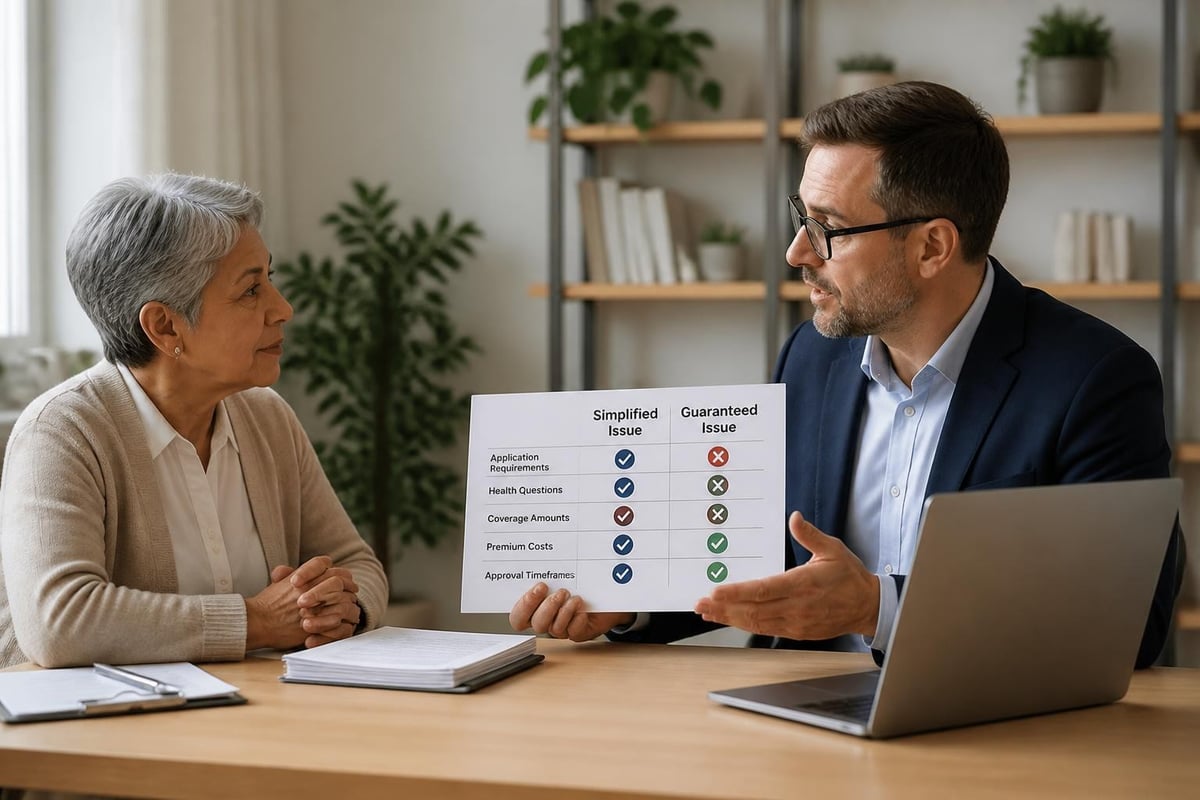
Guaranteed issue policies accept virtually all applicants regardless of health status. These policies typically have lower coverage limits and higher premiums but provide valuable protection for individuals who might otherwise be uninsurable.
| Policy Type | Health Questions | Coverage Limits | Approval Speed | Best For |
|---|---|---|---|---|
| Simplified Issue | Yes (detailed) | $50,000-$500,000+ | 24-48 hours | Healthy to moderate health concerns |
| Guaranteed Issue | Minimal to none | $5,000-$25,000 | Immediate | Serious health conditions |
| Accelerated Underwriting | Yes (brief) | $100,000-$1,000,000+ | Hours to days | Healthy applicants seeking large coverage |
The Accelerated Underwriting Revolution
Advanced technology has enabled major insurers to offer accelerated underwriting for no physical life insurance policies. This approach combines artificial intelligence, predictive analytics, and comprehensive data sources to assess risk without traditional medical exams.
Accelerated underwriting evaluates multiple data points including prescription history, motor vehicle records, criminal background, credit-based insurance scores, and publicly available health information. Guardian Life’s no medical exam options demonstrate how insurers leverage technology to provide substantial coverage amounts while maintaining competitive pricing.
Who Benefits Most From No Exam Policies
Several groups find particular value in no physical life insurance products. Busy professionals who travel frequently or work irregular hours appreciate the convenience of avoiding exam scheduling. Parents seeking coverage to protect their children's financial security often prefer the speed of no exam approval.
People with minor health conditions like controlled high blood pressure or elevated cholesterol may qualify for better rates through simplified issue policies than they might expect. Seniors seeking final expense coverage or smaller policies find guaranteed issue options particularly valuable.
Common scenarios where no exam coverage makes sense:
- Need for immediate coverage due to upcoming travel or surgery
- Mild pre-existing conditions that don't significantly impact longevity
- Replacing lapsed coverage quickly without delays
- Supplementing existing coverage with additional protection
- Estate planning situations requiring fast implementation
Cost Considerations and Premium Factors
No physical life insurance typically costs more than fully underwritten policies with medical exams. This premium difference reflects the increased risk insurers assume without comprehensive health data. MoneyGeek’s analysis of no-exam life insurance costs shows that premiums can range from 15% to 40% higher than traditional policies.
However, the actual cost difference depends on several variables. Your age, coverage amount, term length, and overall health profile significantly impact pricing. Younger, healthier applicants often find minimal premium differences, while older applicants or those with health concerns see more substantial variations.
Comparing Premium Structures
A 35-year-old non-smoker seeking $250,000 of 20-year term coverage might pay approximately $25-$30 monthly for a simplified issue policy compared to $20-$25 for a traditional exam-required policy. The $5-$10 monthly difference represents the convenience premium.
A 55-year-old with controlled diabetes seeking $100,000 of coverage might actually save money with simplified issue policies if traditional underwriting would classify them in higher risk categories. Fidelity Life’s no-exam options illustrate how certain applicants benefit financially from simplified underwriting.
Application Process and Approval Timeline
Applying for no physical life insurance differs substantially from traditional policies. The streamlined process begins with an online or phone application where you provide personal information, coverage preferences, and health history details.
The typical application steps include:
- Complete initial application with basic personal and coverage information
- Answer detailed health questionnaire about current conditions and history
- Authorize access to prescription records and medical databases
- Review and sign policy documents electronically
- Receive approval decision within hours to days
Gerber Life outlines the application process for their no-exam policies, demonstrating how modern insurance technology has simplified coverage acquisition.
Understanding the Underwriting Process
Even without a physical exam, insurers conduct thorough risk assessment for no physical life insurance. Underwriters review your application responses for consistency and accuracy. They access the Medical Information Bureau (MIB) database, which contains information from previous insurance applications.
Prescription check services reveal medications you've been prescribed, indicating diagnosed conditions. Some insurers also review driving records, criminal background checks, and financial information to build comprehensive risk profiles. At Moser Insurance Group Inc, we help clients understand what underwriters look for and how to present their health information accurately. You can reach us at 336-862-1763 or moserinsurancegroup@gmail.com for personalized guidance.
Coverage Limits and Policy Features
No physical life insurance policies come with various coverage limits depending on the type of policy and your individual circumstances. Simplified issue policies typically offer coverage ranging from $50,000 to $500,000, with some carriers providing up to $1,000,000 for highly qualified applicants.
Guaranteed issue policies generally cap coverage between $5,000 and $25,000. These smaller amounts serve specific purposes like final expense coverage, small debt protection, or leaving a modest inheritance.
Term vs Permanent No Exam Options
Both term and permanent life insurance are available without medical exams. Term life insurance provides coverage for specific periods-typically 10, 20, or 30 years-with level premiums throughout the term. No exam term policies work well for temporary needs like mortgage protection or income replacement during working years.
Permanent policies including whole life and universal life offer lifetime coverage with cash value accumulation. No exam permanent policies cost significantly more but provide benefits that extend beyond death benefit protection. Insure Instant Quote explains no exam term options and how they compare to permanent alternatives.
| Coverage Feature | No Exam Term | No Exam Whole Life | No Exam Universal Life |
|---|---|---|---|
| Coverage Duration | 10-30 years | Lifetime | Lifetime |
| Premium Structure | Level for term | Level for life | Flexible |
| Cash Value | None | Yes, guaranteed | Yes, variable |
| Typical Coverage | $50K-$500K | $25K-$250K | $50K-$300K |
Health Conditions and Eligibility
No physical life insurance provides options for individuals across various health spectrums. While simplified issue policies require good to moderate health, they accommodate many common conditions when properly managed.
Conditions that typically qualify for simplified issue coverage include controlled hypertension, treated high cholesterol, well-managed diabetes, past cancer survivors (depending on type and years cancer-free), and mild heart conditions with proper treatment.
Guaranteed issue policies accept virtually anyone, including those with:
- Advanced diabetes with complications
- Recent heart attacks or strokes
- Active cancer treatment
- Severe COPD or respiratory conditions
- Multiple serious health conditions
Pre-Existing Condition Considerations
Most guaranteed issue policies include waiting periods-typically two to three years-before full death benefits apply. During this period, if death results from natural causes, the policy returns premiums paid plus interest rather than the full death benefit. Accidental death usually triggers full benefits immediately.
Simplified issue policies generally don't include waiting periods but may exclude coverage for pre-existing conditions diagnosed before application or during specified look-back periods. Mozdex provides detailed information about how different health conditions affect eligibility and pricing for no exam policies.
Choosing the Right No Exam Policy
Selecting appropriate no physical life insurance requires evaluating your specific needs, health status, and financial objectives. Consider how much coverage you need based on debts, income replacement requirements, final expenses, and legacy goals.
Assess your health honestly. If you're relatively healthy, simplified issue or accelerated underwriting provides better value than guaranteed issue. If you have significant health challenges, guaranteed issue may be your best or only option.
Questions to Ask Before Applying
Understanding policy details prevents surprises after approval. Ask about coverage effective dates-some policies begin immediately while others have waiting periods. Clarify premium payment schedules and whether rates can increase over time.
Determine if the policy offers conversion options, allowing you to convert term coverage to permanent insurance without medical underwriting. Inquire about riders such as accelerated death benefits for terminal illness or waiver of premium for disability.
Critical policy comparison factors:
- Total coverage amount relative to your needs
- Monthly or annual premium costs
- Policy duration and renewal options
- Waiting periods before full benefits apply
- Exclusions or limitations on coverage
- Financial strength ratings of the insurance company
Working With Insurance Professionals
Navigating no physical life insurance options becomes simpler with expert guidance. Independent insurance agents access multiple carriers, comparing policies to find the best match for your situation. They understand underwriting guidelines across different companies and can direct you toward insurers most likely to approve your application at favorable rates.
Professional agents also help you complete applications accurately, avoiding common mistakes that delay approval or result in denial. They explain policy features in plain language, ensuring you understand what you're purchasing.
Residents throughout the Triad Area including Greensboro, Kernersville, High Point, and Winston Salem benefit from local expertise that understands regional insurance markets and carrier availability. At moserinsurancegroup.com, we specialize in helping clients find the right coverage without pressure or confusion.
Online vs Agent-Assisted Applications
While many no physical life insurance policies are available online, working with an agent often produces better outcomes. Agents help you determine appropriate coverage amounts based on comprehensive needs analysis rather than guesswork.
They identify potential underwriting issues before application, positioning your case favorably. Legacy Life Group discusses how professional guidance improves the application experience and results.
Common Misconceptions About No Exam Coverage
Several myths surround no physical life insurance that prevent people from exploring these valuable options. One common misconception suggests that all no exam policies cost significantly more than traditional coverage. While guaranteed issue policies do carry higher premiums, simplified issue and accelerated underwriting often provide competitive rates for healthy applicants.
Another myth claims that no exam policies offer inadequate coverage amounts. In reality, many carriers offer substantial coverage through simplified issue-often $500,000 or more-sufficient for most family protection needs.
Debunking additional misconceptions:
- Myth: Only people with serious health problems need no exam policies
- Reality: Healthy individuals choose these policies for convenience and speed
- Myth: No exam policies always have waiting periods
- Reality: Only guaranteed issue policies typically include waiting periods; simplified issue coverage is immediate
- Myth: You can't get term insurance without an exam
- Reality: Multiple carriers offer term policies through simplified issue and accelerated underwriting
The Future of No Physical Life Insurance
Technology continues transforming the insurance industry, expanding no physical life insurance availability and improving underwriting accuracy. Artificial intelligence and machine learning enable insurers to assess risk more precisely using non-invasive data sources.
Wearable health technology and electronic health records will likely play larger roles in future underwriting processes. Some insurers already offer wellness programs that monitor health metrics through connected devices, potentially reducing premiums for healthy behaviors.
Blockchain technology may streamline the application and claims process further, reducing fraud while protecting applicant privacy. These innovations will likely increase coverage limits available through no exam policies while maintaining competitive pricing.
Industry Trends Shaping 2026 and Beyond
The percentage of life insurance sold without medical exams has grown substantially. Industry data shows accelerated underwriting now accounts for significant portions of term life sales among major carriers. This trend continues as younger consumers demand digital-first experiences and instant gratification.
Insurers increasingly target specific demographic segments with tailored no exam products. Policies designed specifically for seniors, parents, business owners, or gig economy workers reflect growing market segmentation and personalization.
No physical life insurance has revolutionized how Americans protect their families, offering fast, convenient coverage options that fit modern lifestyles without sacrificing adequate protection. Whether you need coverage quickly, prefer avoiding medical exams, or have health conditions complicating traditional underwriting, these policies provide valuable solutions worth exploring. Moser Insurance Group Inc helps individuals and families throughout the Triad Area understand their life insurance options with clear, personalized guidance. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss which no exam life insurance option works best for your unique situation.
Recent Comments