

When protecting your family's financial future, finding the right coverage at an affordable price becomes a top priority. Mutual of Omaha term life insurance offers straightforward protection that many families in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, rely on for peace of mind. This guide examines everything you need to know about their term life insurance products, from coverage options and pricing to application processes and policy features.
Understanding Mutual of Omaha's Term Life Insurance Options
Mutual of Omaha has been providing life insurance since 1909, building a reputation for financial stability and customer service. Their term life insurance products are designed to offer affordable protection for specific time periods, making them accessible to families who need substantial coverage without the higher costs associated with permanent policies.
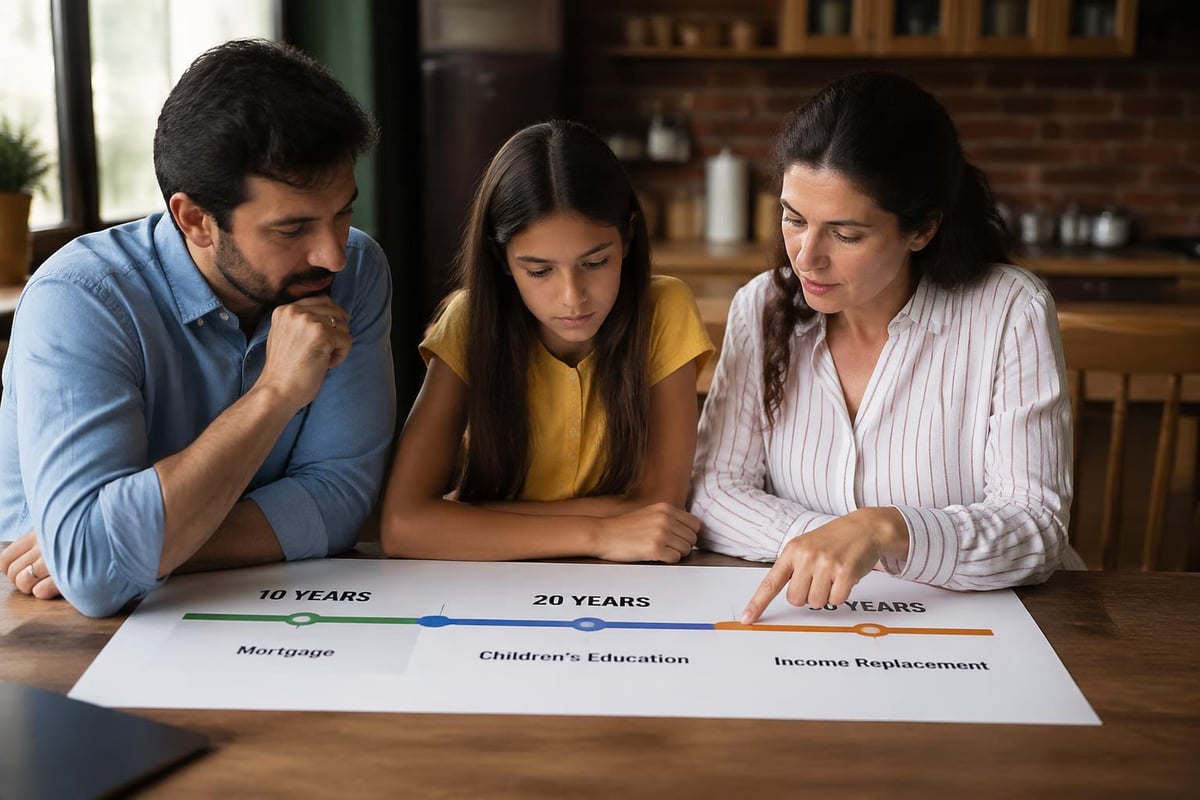
Mutual of Omaha’s term life insurance offerings include multiple term lengths to match different life stages and financial obligations. You can choose coverage periods of 10, 15, 20, or 30 years, allowing you to align your protection with major financial responsibilities like mortgage payments, children's education costs, or income replacement needs.
Coverage Amounts and Flexibility
The company offers death benefit amounts ranging from as low as $25,000 to $5 million, depending on your age, health status, and financial needs. This wide range ensures that both modest protection seekers and those requiring substantial coverage can find appropriate options.
Key coverage features include:
- Level premium payments that remain fixed throughout the term
- Guaranteed death benefit amounts that won't decrease
- Conversion privileges that allow you to switch to permanent coverage
- Renewable options at term end (though at higher rates)
- Accelerated death benefit riders for terminal illness
The flexibility in coverage amounts makes mutual of omaha term life insurance particularly valuable for families navigating different financial stages. Young parents might select $500,000 for 30 years to cover child-raising expenses, while someone nearing retirement might choose $100,000 for 10 years to cover final expenses and outstanding debts.
Application Process and Underwriting Requirements
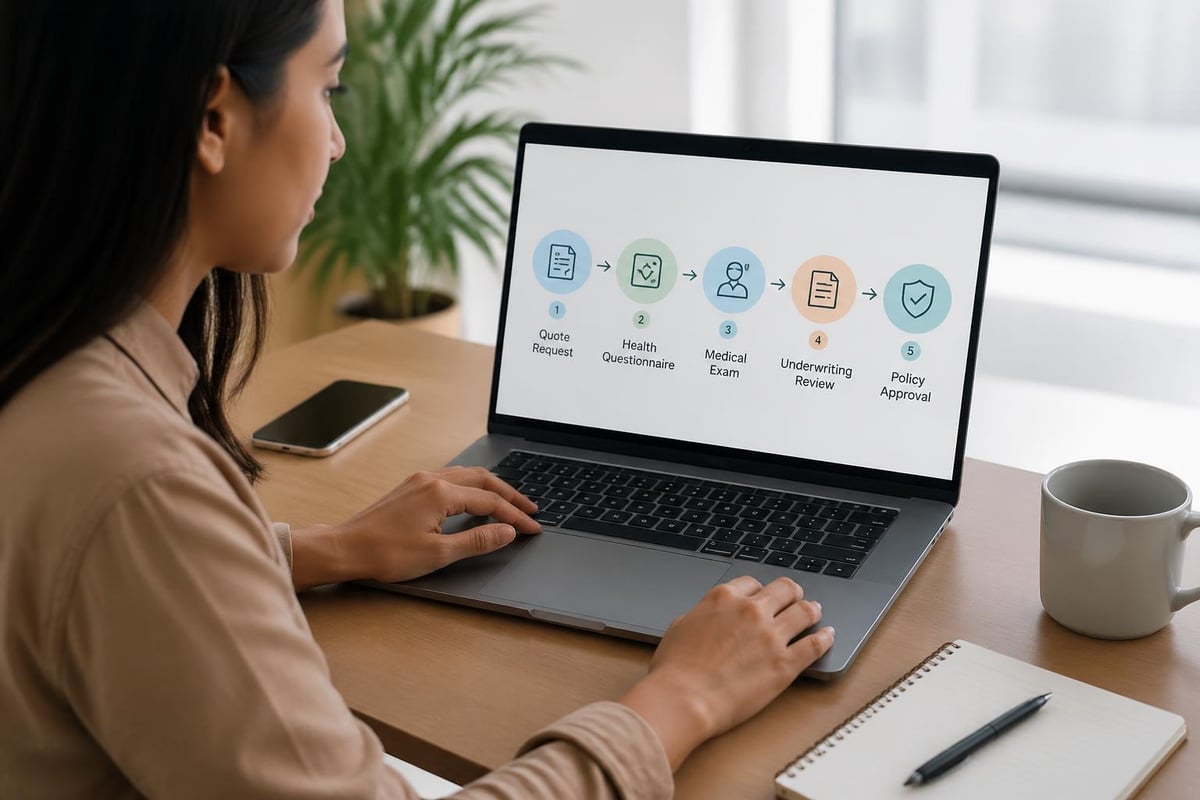
One of the most critical aspects of obtaining mutual of omaha term life insurance involves understanding their underwriting process. The company uses medical underwriting to determine eligibility and premium rates, which means your health status directly impacts both whether you're approved and how much you'll pay.
The standard application process typically involves several steps that most applicants can complete within a few weeks. First, you'll complete a detailed health questionnaire covering your medical history, current health conditions, medications, lifestyle habits, and family health history.
Medical Examinations and Health Classifications
For most coverage amounts above $250,000, Mutual of Omaha requires a paramedical exam. A licensed professional visits your home or office to collect blood and urine samples, measure height and weight, check blood pressure, and review your health questionnaire. The entire exam typically takes 20-30 minutes and is scheduled at your convenience.
| Health Class | Characteristics | Premium Impact |
|---|---|---|
| Preferred Plus | Excellent health, no tobacco, optimal weight | Lowest rates |
| Preferred | Very good health, minor issues only | Low rates |
| Standard Plus | Good health, some manageable conditions | Moderate rates |
| Standard | Average health, controlled chronic conditions | Higher rates |
| Table Rated | Significant health concerns | Substantially higher rates |
The underwriting team reviews all collected information to assign a health classification. According to comprehensive reviews by NerdWallet, Mutual of Omaha generally offers competitive rates for preferred and standard health classes, though pricing can vary significantly based on individual circumstances.
Comparing Costs and Rate Structures
Understanding the cost structure of mutual of omaha term life insurance helps you budget appropriately and compare it against other carriers. Premium rates depend on multiple factors including age, gender, health status, coverage amount, term length, and tobacco use.
Primary factors affecting your rates:
- Age at application: Younger applicants receive substantially lower rates
- Health classification: Better health equals lower premiums
- Tobacco use: Smokers typically pay 2-3x more than non-smokers
- Coverage amount: Higher death benefits increase monthly costs
- Term length: Longer terms generally cost more per month
- Gender: Women typically receive slightly lower rates due to longer life expectancy
For context, a healthy 35-year-old non-smoking male in North Carolina might pay approximately $30-40 monthly for $500,000 of 20-year term coverage, while a 50-year-old with similar characteristics might pay $90-120 for the same coverage. These estimates vary based on specific health details and the exact underwriting classification assigned.
Premium Payment Options and Discounts
Mutual of Omaha offers flexible payment schedules including monthly, quarterly, semi-annual, and annual premium payments. Choosing less frequent payment schedules often results in modest savings, as annual payments typically avoid monthly processing fees.
The company occasionally provides discounts for specific circumstances, such as preferred payment methods (automatic bank draft), multiple policy purchases, or affinity group memberships. Always ask about available discounts when requesting quotes, as these can reduce your overall costs.
Policy Features and Rider Options
Beyond basic death benefit protection, mutual of omaha term life insurance includes several standard features and optional riders that enhance coverage value. Understanding these additions helps you customize policies to match specific family needs and financial goals.
The conversion privilege stands out as one of the most valuable standard features. This allows you to convert your term policy to permanent coverage (whole or universal life) without additional medical underwriting, typically up to age 70 or before the term ends. This feature becomes particularly important if your health deteriorates during the term and you want to maintain coverage beyond the original period.
Available Rider Enhancements
Optional riders provide additional protection or flexibility for specific situations. While each rider increases your premium slightly, the enhanced coverage often justifies the additional cost for families with particular concerns.
- Accelerated Death Benefit Rider: Provides access to a portion of your death benefit if diagnosed with terminal illness (typically with less than 12 months to live)
- Waiver of Premium Rider: Continues coverage without premium payments if you become totally disabled
- Child Term Rider: Adds coverage for all children in your household under one affordable rider
- Accidental Death Benefit Rider: Pays an additional benefit if death results from an accident
The accelerated death benefit rider deserves special attention because it addresses financial needs during terminal illness when medical expenses, lost income, and end-of-life costs create significant burdens. This rider typically doesn't add substantial cost but provides meaningful financial relief during difficult times.
Financial Strength and Company Reputation
When purchasing life insurance, the carrier's financial stability matters as much as policy features and pricing. Your beneficiaries depend on the company's ability to pay claims decades into the future, making financial strength ratings a critical consideration.
Mutual of Omaha maintains strong financial ratings from major rating agencies that evaluate insurance companies' ability to meet long-term obligations. As of 2026, the company holds an A+ (Superior) rating from A.M. Best, indicating excellent financial strength and operating performance. This rating reflects the company's claims-paying ability and overall financial health.
Customer Service and Claims Experience
Beyond financial metrics, customer experience with claims processing and service matters significantly. According to detailed reviews, Mutual of Omaha generally receives positive marks for claims handling, though experiences vary by individual circumstances and policy complexity.
The company offers multiple customer service channels including phone support (available weekdays and Saturdays), online account management, mobile app access, and in-person agent consultations. Policyholders can view coverage details, make premium payments, update beneficiaries, and request policy changes through digital platforms.
Special Considerations for Different Age Groups
Mutual of omaha term life insurance serves customers across various life stages, but certain age groups face unique considerations when evaluating coverage options. Understanding these distinctions helps you choose appropriate coverage amounts and term lengths.
Young Families and First-Time Buyers
Individuals in their 20s and 30s typically receive the most favorable rates due to excellent health and low mortality risk. This age group should prioritize higher coverage amounts (5-10x annual income) with longer terms (20-30 years) to protect growing families through critical financial periods.
For residents in Greensboro, Kernersville, High Point, and Winston Salem raising young children, a 30-year term often aligns perfectly with financial responsibilities like mortgage payments and education funding. The affordable premiums at younger ages make substantial coverage amounts accessible, providing maximum protection when family financial vulnerability peaks.
Mid-Career Professionals (40s and 50s)
Applicants in their 40s and 50s face higher premiums but still access reasonable rates if health remains good. This group often needs to balance coverage needs against increasing costs, making 15-20 year terms popular choices that extend protection through children's college years and peak earning periods.
Research on term life insurance for different ages suggests that individuals over 50 should carefully evaluate whether term or permanent coverage better serves their goals, as conversion options become increasingly valuable.
Seniors and Pre-Retirees
Those over 60 face significantly higher term life insurance premiums and may encounter coverage limitations. Term life insurance for seniors remains available but often proves less cost-effective than permanent options or guaranteed issue products designed specifically for older applicants.
For seniors in the Triad Area, exploring alternatives like whole life insurance might provide better value when term premiums reach levels that make coverage cost-prohibitive relative to death benefits.
Comparing Term versus Permanent Life Insurance
While this guide focuses on mutual of omaha term life insurance, understanding how term coverage compares to permanent options helps you make informed decisions aligned with your financial goals and family circumstances.
Term Life Insurance Advantages:
- Significantly lower premiums for same coverage amount
- Straightforward coverage without complex cash value components
- Flexibility to choose term lengths matching specific obligations
- Ideal for temporary needs like mortgage protection or income replacement
Permanent Life Insurance Advantages:
- Lifetime coverage that doesn't expire
- Cash value accumulation that grows tax-deferred
- Level premiums that never increase
- Estate planning and wealth transfer benefits
The comparison between permanent and term coverage reveals that most families benefit from term insurance during working years when financial protection needs peak but budgets remain tight. Permanent insurance serves different purposes, primarily estate planning, lifetime coverage guarantees, and forced savings through cash value growth.
For families in Winston Salem, High Point, and throughout the Triad Area, exploring the best term life insurance options helps you understand how different carriers and products compare in your specific situation.
Application Tips and Approval Strategies
Maximizing your chances of approval at the best possible rates requires understanding what underwriters evaluate and how to present your health profile most favorably. Several strategies can improve your application outcomes and potentially save thousands over your policy's lifetime.
Timing Your Application Strategically
Apply when your health status is optimal. If you're currently managing a minor health issue, working with your doctor to stabilize the condition before applying often results in better classifications. Similarly, if you've recently quit smoking, waiting until you've been tobacco-free for the carrier's required period (typically 12 months) dramatically reduces your premiums.
Weight presents another timing consideration. If you're slightly above optimal weight ranges, losing 10-20 pounds before the medical exam can shift you into a more favorable health class, potentially saving hundreds annually in premiums.
Before applying:
- Schedule your annual physical and address any outstanding health concerns
- Gather documentation for well-controlled chronic conditions
- Compile a complete list of current medications with dosages
- Review your family health history for accurate reporting
- Avoid alcohol for 48 hours before the medical exam
Working with Independent Agents
Independent insurance agents who represent multiple carriers, including Mutual of Omaha, provide valuable assistance throughout the application process. These professionals understand different carriers' underwriting preferences and can match your specific health profile with the carrier most likely to offer favorable terms.
For residents throughout the Triad Area, working with local expertise ensures you understand how regional factors might influence your coverage options. You can reach knowledgeable professionals at Moser Insurance Group Inc by calling 336-862-1763 or emailing moserinsurancegroup@gmail.com to discuss your specific needs and explore multiple carrier options.
Common Exclusions and Policy Limitations
Understanding what mutual of omaha term life insurance doesn't cover helps set realistic expectations and avoid surprises when beneficiaries file claims. While term life insurance provides broad protection, certain exclusions apply to most policies across the industry.
The contestability period represents the most significant limitation for new policyholders. During the first two years after policy issuance, the company can investigate claims and potentially deny benefits if they discover material misrepresentations on the application. This provision protects against fraud but emphasizes the critical importance of complete honesty during the application process.
Standard Policy Exclusions
| Exclusion Type | Details | Duration |
|---|---|---|
| Suicide | Death by suicide typically not covered | First 2 years |
| Material Misrepresentation | False application information | First 2 years (contestability period) |
| War or Military Action | Active combat participation | Policy lifetime |
| Aviation (in some cases) | Non-commercial pilot activities | Varies by policy |
Most policies pay claims for deaths resulting from accidents, illness, natural causes, and even some high-risk activities once the contestability period expires. The suicide exclusion, while difficult to discuss, represents standard industry practice designed to prevent adverse selection from individuals purchasing coverage with intent to self-harm.
Policy Renewal and Conversion Options
What happens when your term ends remains an important consideration when purchasing mutual of omaha term life insurance. Understanding your options at term expiration helps you plan for long-term protection needs that may extend beyond your original coverage period.
Annual Renewable Term (ART) Continuation
Most term policies include an option to renew coverage annually after the level premium period ends, though premiums increase substantially each year based on your attained age. While this ensures continued coverage without medical underwriting, the rapidly escalating costs make long-term renewal impractical for most policyholders.
For example, a $500,000 policy that cost $100 monthly during the level term might jump to $300 monthly in the first renewal year, then $400 the following year, with costs continuing to rise annually. This steep progression makes renewal suitable only as a short-term bridge while exploring other coverage options.
Conversion to Permanent Coverage
The conversion privilege provides a more viable long-term solution. This feature allows you to convert part or all of your term coverage to permanent life insurance without answering health questions or undergoing medical exams. The conversion premium reflects your age at conversion, not your age when you originally purchased the term policy.
Conversion becomes particularly valuable if your health has deteriorated during the term, making new coverage impossible or prohibitively expensive. Even with higher permanent insurance premiums, maintaining coverage through conversion often beats losing protection entirely.
Regional Considerations for North Carolina Residents
Residents throughout the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, should understand how local factors might influence their life insurance decisions and coverage needs. While term life insurance operates similarly across states, regional economic conditions and family dynamics create specific considerations.
North Carolina's relatively moderate cost of living compared to national averages allows families to potentially purchase higher coverage amounts at more affordable premium levels. A $500,000 policy might represent more substantial protection here than in higher-cost metropolitan areas, providing greater financial security for beneficiaries.
Local Economic Factors
The Triad Area's diverse economy, including manufacturing, healthcare, education, and service industries, creates varied income profiles and protection needs. Manufacturing workers might prioritize coverage amounts that replace 20-30 years of income, while business owners often need substantially higher coverage to protect business interests and personal family finances.
Additionally, North Carolina residents should consider how state-specific factors like property values, education costs at state universities, and family structures influence appropriate coverage amounts. A mortgage on a $300,000 home in Winston Salem, combined with college savings goals and income replacement needs, might suggest a $750,000 to $1 million policy for primary earners.
Claim Filing Process and Beneficiary Guidance
While nobody wants to think about the circumstances requiring a claim, understanding the process helps beneficiaries navigate difficult times more smoothly. Mutual of omaha term life insurance claims typically follow standard industry procedures, though specific requirements may vary based on circumstances.
Basic claim steps include:
- Notification: Contact the company immediately by phone at their claims department
- Documentation: Submit an official death certificate (certified copy)
- Claim Form: Complete the beneficiary claim form with required information
- Additional Information: Provide any supplementary documentation requested
- Processing: Allow the company time to review and verify the claim
- Payment: Receive death benefit proceeds via check or electronic transfer
Most straightforward claims process within 30-60 days from submission of complete documentation. Claims occurring during the contestability period may take longer as the company conducts required investigations. Beneficiaries can expedite processing by submitting all requested documentation promptly and responding quickly to any company inquiries.
Making Your Coverage Decision
Choosing the right mutual of omaha term life insurance policy requires balancing coverage needs, budget constraints, and long-term financial goals. Rather than selecting coverage based solely on premium affordability, evaluate what your family truly needs to maintain financial stability if you're no longer there to provide.
Financial professionals typically recommend coverage amounts equal to 5-10 times your annual income, though individual circumstances vary significantly. Consider outstanding debts, future income needs, education funding goals, final expense costs, and any special circumstances when calculating appropriate coverage levels.
For personalized guidance exploring coverage options, including mutual of omaha term life insurance and alternatives from other carriers, contact Moser Insurance Group Inc at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com. Independent advice helps you compare multiple options and find coverage perfectly matched to your family's unique situation in Greensboro, Kernersville, High Point, Winston Salem, or throughout the Triad Area.
Protecting your family's financial future requires careful consideration of coverage options, carrier selection, and policy features that match your specific circumstances. Mutual of omaha term life insurance provides one of many solutions worth exploring as you build comprehensive financial protection. At Moser Insurance Group Inc, we help families throughout the Triad Area understand their life insurance options with clear, unbiased guidance and personalized support. Whether you're comparing term life carriers, exploring coverage amounts, or evaluating alternatives, we're here to answer your questions and help you make confident decisions. Contact us at 336-862-1763 or visit Moser Insurance Group Inc to start a conversation about protecting what matters most.
Recent Comments