

When you purchase a home, protecting that investment becomes a top priority. Many homeowners in the Triad Area-including Greensboro, Kernersville, High Point, and Winston Salem-hear the term mortgage protection and wonder whether it's something they need. Understanding what mortgage protection actually covers, how it differs from other types of insurance, and whether it aligns with your family's financial goals can help you make an informed decision without pressure.
What Is Mortgage Protection Insurance?
Mortgage protection insurance is a type of policy designed to pay off or cover your mortgage payments if you die, become disabled, or lose your job. The primary purpose is to ensure your family won't lose the home if you're no longer able to make payments. This coverage is sold as a safeguard for borrowers who want peace of mind that their mortgage obligation won't burden loved ones.
How Mortgage Protection Works
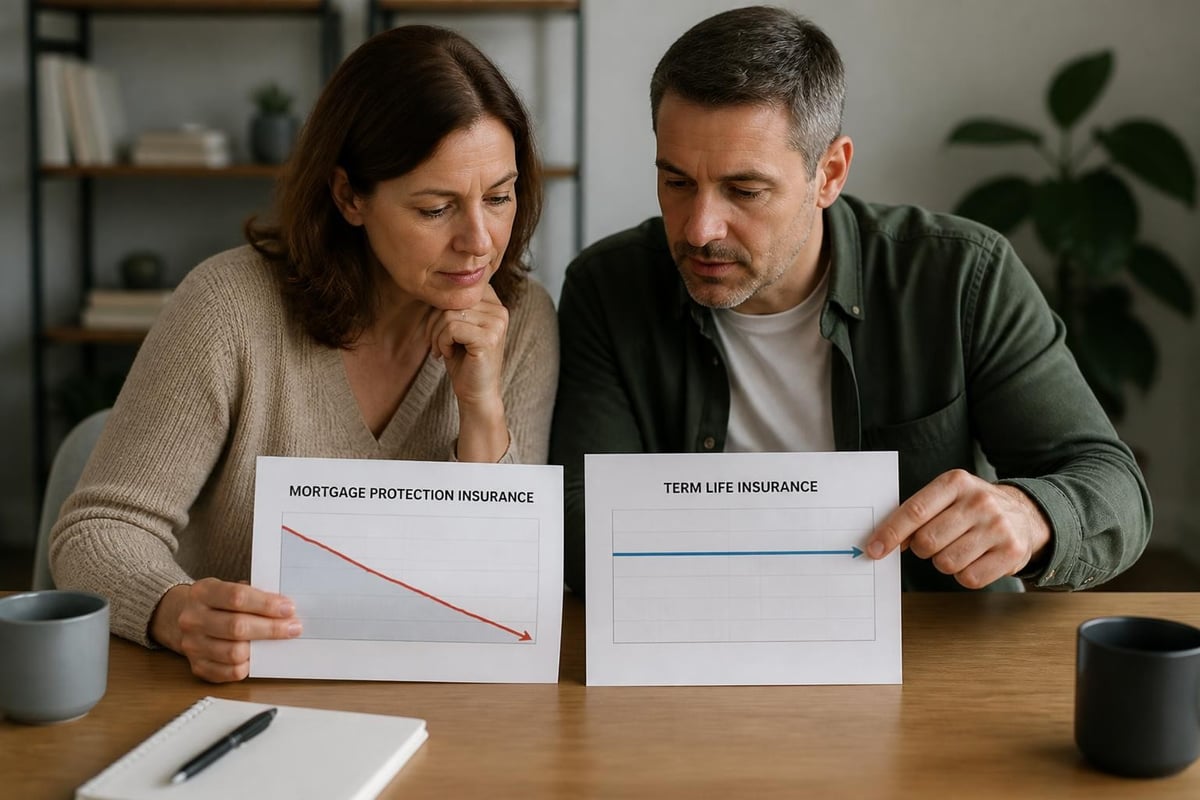
When you purchase mortgage protection, the policy pays a benefit directly to your lender or to you, depending on the product structure. Most policies are structured as decreasing term life insurance, meaning the death benefit shrinks over time as your mortgage balance decreases. If you pass away during the policy term, the insurer pays the remaining mortgage balance or provides funds to cover monthly payments.
- Death benefit: Pays off or covers the mortgage if you die
- Disability rider: Covers monthly payments if you become disabled
- Unemployment rider: Provides temporary payment coverage if you lose your job
These features sound appealing, but it's essential to compare costs, flexibility, and alternatives before committing.
Mortgage Protection vs. Private Mortgage Insurance (PMI)
Many people confuse mortgage protection with private mortgage insurance (PMI), but they serve completely different purposes. PMI protects the lender, not you. If you make a down payment of less than 20% on a conventional loan, lenders typically require PMI to protect themselves in case you default. According to the Consumer Financial Protection Bureau, PMI can be canceled once you reach 20% equity, while mortgage protection is a separate life insurance product you purchase voluntarily.
| Feature | Mortgage Protection Insurance | Private Mortgage Insurance (PMI) |
|---|---|---|
| Who it protects | You and your family | The lender |
| Purpose | Pays off mortgage if you die/disabled | Protects lender if you default |
| Required? | Voluntary | Required if down payment < 20% |
| Can be canceled? | Yes, anytime | Yes, at 20% equity |
| Benefit amount | Decreases over time | N/A |
Understanding this distinction helps you avoid paying for coverage you don't need or assuming PMI provides family protection when it doesn't.
Mortgage Protection vs. Term Life Insurance
Another critical comparison is between mortgage protection and traditional term life insurance. While both provide a death benefit, term life offers significantly more flexibility and often better value. With term life insurance, your beneficiaries receive a fixed payout that they can use for any purpose: paying off the mortgage, covering daily expenses, funding education, or investing for the future.
Key Differences
Mortgage protection insurance ties the benefit directly to your mortgage balance. As you pay down your loan, the death benefit decreases, but your premiums typically stay the same. The payout goes directly to the lender in many cases, leaving your family with no flexibility.
Term life insurance provides a level death benefit for the entire term (10, 20, or 30 years). Your family receives the full amount and decides how to use it. If you've already paid off half your mortgage, they still get the full benefit amount.
From a cost perspective, term life is often less expensive for the same or greater coverage. For example, a healthy 35-year-old in North Carolina might pay $30–$50 per month for a $500,000, 20-year term policy, while mortgage protection for the same loan amount could cost similar or more with a shrinking benefit.
Who Needs Mortgage Protection?
Mortgage protection may make sense in specific situations, but it's not the right fit for everyone. Consider your overall financial picture, existing coverage, and family needs before purchasing.
Scenarios Where It Might Help
- Health issues: If you have serious health conditions that make qualifying for traditional term life difficult, mortgage protection policies often have simplified underwriting or guaranteed acceptance
- Immediate need: You've just closed on a home and want instant coverage without a medical exam
- Single income household: One earner supports the family, and losing that income would immediately threaten homeownership
When Term Life Is a Better Choice
For most families in Greensboro, Kernersville, High Point, and Winston Salem, term life insurance offers superior value and flexibility. If you're in good health, you'll likely qualify for lower rates and a policy that adapts as your needs change. Your beneficiaries aren't locked into using the funds for the mortgage alone.
When evaluating your options, think beyond just the mortgage. Consider other debts, income replacement needs, and long-term goals. A comprehensive approach often reveals that a larger term life policy-or a combination of term life and permanent coverage like universal life insurance-provides better protection for the same premium.
Understanding Costs and Coverage Limits
Mortgage protection premiums depend on your mortgage balance, age, health, and the riders you add. Policies sold through direct mail or telemarketing often charge higher premiums because they include simplified underwriting and accept applicants with health issues.
Cost Factors
- Loan amount: Higher balances mean higher premiums
- Term length: Matching your policy term to your mortgage term affects cost
- Riders: Disability and unemployment coverage add to monthly costs
- Health status: Simplified underwriting policies charge more but require less medical information
Always request quotes from multiple sources and compare them to term life alternatives. Don't rely solely on direct mail offers or high-pressure sales tactics. Research from the Urban Institute shows that mortgage insurance markets vary significantly in pricing and product features, making comparison shopping essential.
Common Misconceptions About Mortgage Protection
Several myths surround mortgage protection, leading homeowners to make decisions based on incomplete or incorrect information.
Myth: Mortgage Protection Is Required
Reality: Mortgage protection is never required by lenders. Private mortgage insurance (PMI) or FHA mortgage insurance premiums (MIP) may be required on certain loans, but those protect the lender. As explained by the U.S. Department of Housing and Urban Development, MIP is mandatory on FHA loans but has nothing to do with voluntary mortgage protection products.
Myth: It's the Cheapest Option
Reality: For healthy applicants, term life insurance almost always costs less for the same or better coverage. Mortgage protection's simplified underwriting comes at a price: higher premiums and shrinking benefits.
Myth: The Lender Provides It
Reality: Lenders may offer information about mortgage protection, but they don't provide the coverage. Third-party insurers sell these policies, sometimes using the lender's name or branding to imply endorsement. Always verify the insurer's credentials and compare independent options.
Regulatory and Consumer Protection Considerations
Because mortgage protection marketing can be aggressive, consumer protection agencies monitor sales practices closely. The Federal Trade Commission has taken enforcement action against companies using deceptive tactics to sell mortgage-related products, including falsely implying government affiliation or lender endorsement.
Red Flags to Watch For
- High-pressure sales calls or mailers claiming your lender "requires" coverage
- Refusal to provide written policy details before purchase
- Statements that the offer is "limited time only" or available only through that specific agent
- Lack of clarity about who receives the death benefit (you or the lender)
If you receive unsolicited mortgage protection offers, take your time. Request written materials, compare quotes from independent agents, and consult with a licensed insurance professional who can review your full financial picture. In the Triad Area, working with a local advisor who understands North Carolina's insurance landscape provides valuable context and unbiased guidance.
Alternatives to Mortgage Protection Insurance
Beyond traditional term life insurance, several other strategies can protect your mortgage and family without purchasing a specialized product.
Build an Emergency Fund
Establishing 3–6 months of expenses in savings provides a cushion if you lose your job or face a temporary disability. This fund can cover mortgage payments while you recover or find new employment.
Disability Insurance
If you're concerned about losing income due to illness or injury, disability insurance replaces a percentage of your salary and can be used for any expense, including your mortgage. Many employers offer group disability coverage, and individual policies provide tailored protection.
Life Insurance with Cash Value
Permanent life insurance policies, such as whole life or universal life, build cash value you can borrow against in emergencies. While more expensive than term life, they offer lifetime coverage and a savings component that grows tax-deferred.
According to guidance from the National Association of Insurance Commissioners, comparing term and permanent life options helps consumers choose coverage that fits their budget and long-term goals.
How to Evaluate Mortgage Protection Offers
If you're considering mortgage protection, use a structured approach to evaluate whether it's the right choice.
Steps to Take
- Calculate your total protection need: Add up your mortgage balance, other debts, income replacement needs, and future expenses (education, retirement)
- Get multiple quotes: Compare mortgage protection to term life from at least three insurers
- Review policy details: Understand whether the benefit goes to you or the lender, how the benefit amount changes, and what exclusions apply
- Check insurer ratings: Verify the company's financial strength through ratings agencies
- Consult an independent advisor: Speak with a licensed agent who can explain all your options without pressure
For personalized support, you can reach Moser Insurance Group Inc at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com to discuss your coverage needs.
The Role of Underwriting in Mortgage Protection
One of mortgage protection's selling points is simplified or guaranteed issue underwriting, which allows people with health issues to obtain coverage. However, this convenience comes at a cost.
Simplified Issue vs. Fully Underwritten
Simplified issue policies ask basic health questions but don't require a medical exam. Approval is faster, but premiums are higher. Benefit amounts may also be capped at lower levels.
Fully underwritten policies (typical for term life) require a medical exam, health records review, and detailed questions. Healthy applicants receive the best rates, and coverage amounts can be much higher.
If you have significant health concerns that would disqualify you from traditional term life, mortgage protection might be your best option. But if you're in average or good health, the savings from a fully underwritten term life policy often outweigh the convenience of simplified underwriting.
Mortgage Protection and Estate Planning
Mortgage protection fits into broader estate planning by ensuring your home doesn't become a financial burden on heirs. However, integrating it with other tools creates a more comprehensive plan.
Coordinating with Other Coverage
- Existing life insurance: If you already have term or permanent life coverage, adding mortgage protection may be redundant
- Spousal coverage: Ensure both spouses are adequately covered, especially if both incomes are needed for the mortgage
- Beneficiary designations: Clarify whether the benefit is payable to the estate, a trust, or directly to the lender
Effective estate planning also considers income taxes, probate, and legacy goals. A holistic review ensures your insurance coverage aligns with your will, trusts, and other estate documents. As noted by Experian, understanding the differences between mortgage-specific products and flexible life insurance helps you build a plan that adapts as your life changes.
Practical Tips for Homeowners in North Carolina
Living in North Carolina means navigating state-specific insurance regulations and market conditions. Here are practical tips for homeowners in Greensboro, Kernersville, High Point, Winston Salem, and throughout the Triad Area.
Shop Locally and Independently
Working with a local, independent insurance agent gives you access to multiple carriers and unbiased advice. Unlike captive agents who represent one company, independent agents compare options and tailor recommendations to your needs.
Review Coverage Annually
Your mortgage balance decreases each year, and your family's needs evolve. Review your coverage annually to ensure it still makes sense. If you have a decreasing benefit mortgage protection policy, consider whether switching to level term life provides better value.
Avoid Impulse Decisions
Don't sign up for mortgage protection during the closing process or immediately after receiving a solicitation. Take time to research, compare quotes, and consult with an advisor.
Leverage North Carolina Resources
North Carolina residents can verify insurer licenses and file complaints through the state Department of Insurance. Always confirm that the company and agent are properly licensed before purchasing coverage.
For more guidance on life insurance options, Moser Insurance Group Inc offers educational resources and personalized consultations to help you understand your choices.
When Mortgage Protection Makes Sense
Despite the general preference for term life insurance, mortgage protection can be appropriate in select cases. Recognizing these situations helps you make the right choice.
Health Challenges
If you've been declined for traditional term life due to serious health conditions-cancer, heart disease, diabetes-mortgage protection's guaranteed or simplified issue options may be your only path to coverage.
Immediate Coverage Needs
When you need coverage today and can't wait for underwriting, mortgage protection provides instant approval. This scenario might apply if you've just been diagnosed with a condition and want to lock in coverage before your health deteriorates further.
Specific Lender Requirements or Preferences
In rare cases, lenders or loan programs may incentivize or suggest mortgage protection. Always verify whether this is truly required or simply marketed as an option.
According to Kiplinger, weighing these scenarios against term life alternatives ensures you're not overpaying for limited benefits when better options exist.
Final Considerations Before Purchasing
Before committing to any mortgage protection policy, ask yourself these questions:
- Do I already have life insurance that would cover my mortgage?
- Am I healthy enough to qualify for a fully underwritten term life policy?
- Would my family benefit more from a flexible death benefit they can use for any purpose?
- Have I compared at least three quotes from different insurers?
- Do I understand exactly who receives the benefit and how the amount changes over time?
Honest answers to these questions guide you toward the coverage that truly protects your family without unnecessary cost.
Protecting your home and family requires thoughtful planning, not impulsive decisions driven by fear or pressure. Whether mortgage protection, term life, or another solution fits your needs depends on your health, budget, and long-term goals. Moser Insurance Group Inc helps individuals and families in the Triad Area understand their insurance options with clear guidance and personalized support, so you can make confident decisions without pressure. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your coverage needs today.
Recent Comments