

Protecting your family's home is one of the most important financial decisions you'll make. When you take out a mortgage, you're committing to decades of payments, and the thought of leaving that burden to loved ones if something happens to you can be overwhelming. This is where specialized coverage designed to pay off your home loan comes into play, offering peace of mind that your family won't lose the house during an already difficult time. Understanding how this protection works, what it costs, and whether it's the right choice for your situation requires careful consideration of several factors.
What Is Mortgage Life Insurance
Mortgage life insurance is a type of decreasing term policy specifically designed to pay off your remaining mortgage balance if you pass away during the loan term. Unlike traditional life insurance policies where your beneficiaries receive the death benefit and decide how to use it, this coverage pays directly to your mortgage lender.
The defining characteristic of mortgage life insurance is that the death benefit decreases over time as you pay down your mortgage principal. In the early years of a 30-year mortgage, you might owe $300,000, but after 15 years, you might only owe $150,000. The insurance coverage mirrors this declining balance.
How the Coverage Works
When you purchase mortgage life insurance, the policy amount typically matches your outstanding loan balance at the time of purchase. As you make monthly mortgage payments, your coverage amount automatically decreases proportionally.
Key operational features include:
- Coverage that declines as your mortgage balance decreases
- Premiums that generally remain level throughout the policy term
- Direct payment to the mortgage lender upon the policyholder's death
- No medical exam required in many cases
- Simplified application process compared to traditional life insurance
The policy remains in effect as long as you continue paying premiums and maintain your mortgage. If you pay off your mortgage early or refinance with a different lender, the policy may terminate or require adjustment.
Mortgage Life Insurance vs Traditional Term Life Insurance
Understanding the differences between mortgage life insurance and standard term life insurance helps you make an informed decision about which provides better value for your specific needs.
| Feature | Mortgage Life Insurance | Traditional Term Life Insurance |
|---|---|---|
| Death Benefit | Decreases over time | Remains level throughout term |
| Beneficiary | Mortgage lender | Person(s) you choose |
| Flexibility | Low – tied to mortgage | High – beneficiaries choose how to use funds |
| Medical Exam | Often not required | Usually required for best rates |
| Cost | Higher per dollar of coverage | Generally lower for healthy applicants |
| Coverage Amount Control | Matches mortgage balance | You select any amount you need |
NerdWallet’s guide to mortgage protection insurance explains that traditional term life insurance often provides more value and flexibility for most homeowners. With term life, your beneficiaries receive the full death benefit regardless of how much you still owe on the mortgage, and they can use those funds for any purpose, including keeping the house, paying off the mortgage, or selling the property and using the money for other needs.
The Medical Underwriting Difference
One significant distinction lies in the underwriting process. Mortgage life insurance policies frequently offer guaranteed acceptance or simplified underwriting, meaning you can qualify even with health conditions that would result in higher premiums or denial for traditional coverage.
However, this convenience comes at a cost. The guaranteed acceptance feature means insurers spread the risk across all policyholders, resulting in higher premiums for healthy individuals who would qualify for preferred rates on traditional policies.
Who Should Consider Mortgage Life Insurance
Despite the limitations, mortgage life insurance serves specific situations where it may be the appropriate choice for homeowners in the Triad Area, including Greensboro, Kernersville, High Point, and Winston-Salem.
Situations where mortgage life insurance makes sense:
- Significant health issues that prevent you from qualifying for traditional life insurance at affordable rates
- Older homeowners who face age-related premium increases on standard term policies
- Time-sensitive needs when you want immediate coverage without waiting for medical exam results
- Simplified estate planning where you specifically want the mortgage paid off rather than leaving decision-making to beneficiaries
For individuals with serious pre-existing conditions such as diabetes, heart disease, or cancer history, the guaranteed acceptance aspect of mortgage life insurance can provide coverage that might otherwise be unavailable or prohibitively expensive.
When Traditional Coverage Works Better
Most healthy homeowners under age 60 will find better value in traditional term life insurance. Kiplinger’s explanation of mortgage protection insurance notes that term life policies typically cost 30-50% less than mortgage life insurance for the same initial coverage amount.
Additionally, term life insurance provides flexibility to protect multiple financial obligations simultaneously. A $500,000 term policy can cover your mortgage, replace income for your family, fund children's education, and pay final expenses, whereas mortgage life insurance only addresses the home loan.
Cost Factors and Premium Considerations
The price of mortgage life insurance varies based on several factors, but understanding how premiums are calculated helps you evaluate whether the cost justifies the benefits for your situation.
Primary factors affecting mortgage life insurance premiums:
- Remaining mortgage balance at policy inception
- Length of your mortgage term
- Your age at the time of application
- Whether medical underwriting is required or waived
- The insurance company's risk assessment models
- State regulations and insurance market competition
A 40-year-old homeowner with a $250,000 mortgage might pay $60-100 per month for mortgage life insurance with guaranteed acceptance. By comparison, the same person in good health could obtain a $300,000 20-year term life policy for $30-50 per month, providing more initial coverage at a lower cost.
Hidden Costs and Premium Stability
While mortgage life insurance premiums typically remain level, the value proposition deteriorates over time. You pay the same premium in year 20 as you did in year 1, but your coverage has decreased substantially as you've paid down the mortgage principal.
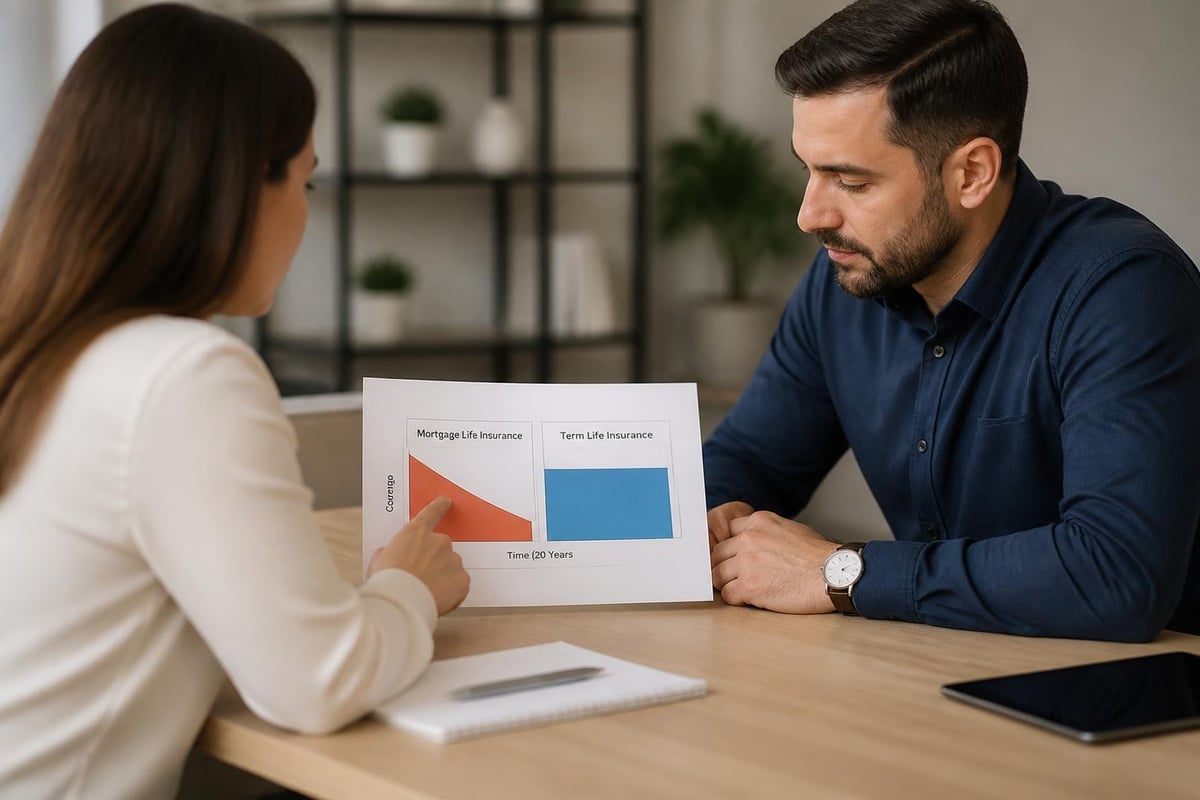
Consider a $300,000 mortgage life insurance policy with $75 monthly premiums. Over 20 years, you'll pay $18,000 in premiums while your coverage drops from $300,000 to approximately $100,000. With term life insurance at $40 monthly, you'd pay $9,600 for consistent $300,000 coverage.
Alternative Protection Strategies
Before committing to mortgage life insurance, explore alternative approaches that might provide superior protection and financial flexibility for your family's long-term security.
Term Life Insurance as Primary Protection
Term life insurance offers the most cost-effective solution for most homeowners. By purchasing a policy with a death benefit sufficient to cover your mortgage plus additional family needs, you provide comprehensive protection with beneficiary flexibility.
Calculate your total coverage needs by adding:
- Outstanding mortgage balance
- 3-5 years of income replacement
- Children's education costs
- Final expenses and estate settlement costs
- Outstanding debts beyond the mortgage
This comprehensive approach ensures your family maintains their lifestyle even while grieving, rather than simply avoiding foreclosure.
Disability Insurance for Income Protection
While life insurance addresses death, disability insurance protects against the more common scenario of being unable to work due to injury or illness. Most mortgage defaults result from job loss or disability, not death.
Income protection coverage ensures you can continue making mortgage payments if you're unable to work, preventing foreclosure while you're still alive to experience the financial stress. This proactive approach complements life insurance by addressing the full spectrum of risks to your home ownership.
Building Emergency Savings
A robust emergency fund covering 6-12 months of expenses, including your mortgage payment, provides flexible protection against various financial disruptions. Unlike insurance that only pays in specific circumstances, savings can address any challenge from job loss to medical emergencies to home repairs.
Making the Right Decision for Your Family
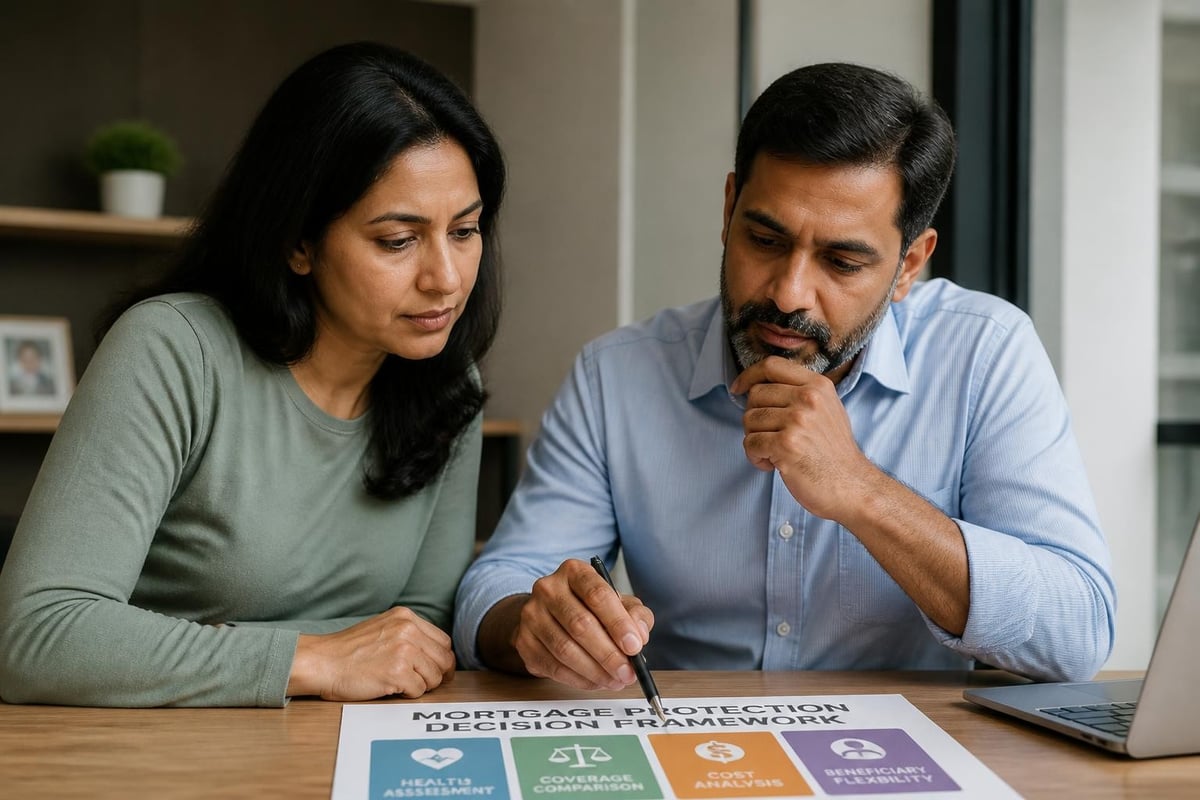
Choosing between mortgage life insurance and alternatives requires honest assessment of your health status, financial situation, and family protection goals. Zillow’s analysis of mortgage life insurance pros and cons emphasizes that most financial advisors recommend traditional term life insurance for its superior value and flexibility.
Questions to ask yourself:
- Do I have health conditions that would prevent me from qualifying for traditional life insurance?
- Would my beneficiaries benefit from flexibility in using death benefit funds?
- Am I comfortable with decreasing coverage while paying level premiums?
- Could I obtain more comprehensive protection at a lower cost through term life insurance?
- Do I have other financial obligations beyond my mortgage that need protection?
If you're in good health and qualify for standard insurance rates, traditional term life insurance almost always provides better value. The combination of level death benefits, lower premiums, and beneficiary flexibility makes it the superior choice for comprehensive family protection.
Working With an Insurance Professional
Navigating life insurance options requires expertise and personalized guidance. An experienced insurance professional can evaluate your specific health situation, financial obligations, and protection goals to recommend the most appropriate coverage.
For residents throughout the Triad Area, including Greensboro, Kernersville, High Point, and Winston-Salem, working with a local advisor who understands regional factors and can compare multiple carriers ensures you receive competitive pricing and suitable coverage. You can reach Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com for personalized guidance.
Understanding Policy Terms and Exclusions
Before purchasing mortgage life insurance, carefully review policy documents to understand limitations, exclusions, and circumstances that might prevent your family from receiving benefits.
Common Exclusions and Limitations
Most mortgage life insurance policies include standard exclusions that deny coverage under specific circumstances:
| Exclusion Type | Details | Duration |
|---|---|---|
| Suicide Clause | Death by suicide not covered | First 1-2 years |
| Pre-existing Conditions | Conditions present before coverage | First 12-24 months |
| Hazardous Activities | Death during extreme sports or activities | Entire policy term |
| War or Military Action | Death during active combat | Entire policy term |
| Fraudulent Application | Material misrepresentation on application | Entire policy term |
Insurance.com’s comparison of mortgage life insurance to standard policies notes that some policies include waiting periods where only accidental death is covered, with full coverage beginning after 12-24 months.
Policy Portability and Conversion Options
Unlike traditional life insurance that remains in effect regardless of employment or residence changes, mortgage life insurance terminates when you pay off or refinance your mortgage with a different lender. This lack of portability means you lose coverage precisely when you've built significant home equity.
Some policies offer conversion options allowing you to convert to permanent life insurance without medical underwriting, but these conversions typically come with substantially higher premiums and may have limited time windows for execution.
Regulatory Protections and Consumer Rights
Mortgage life insurance falls under state insurance regulations, providing consumers with specific protections and rights when purchasing and maintaining coverage.
Your rights as a policyholder include:
- Free look period (typically 10-30 days) to review and cancel for a full refund
- Clear disclosure of premiums, coverage amounts, and policy terms
- Protection against unfair claims denials through state insurance departments
- Grace periods for late premium payments before policy termination
- Reinstatement rights if coverage lapses due to non-payment
If you experience claim difficulties or believe an insurer has acted unfairly, you can file complaints with your state insurance commissioner, who investigates consumer grievances and enforces insurance regulations.
Special Considerations for Specific Situations
Certain life circumstances create unique considerations when evaluating mortgage life insurance versus alternative protection strategies.
Single Income Households
Families dependent on one income face heightened risk if that earner passes away. While mortgage life insurance protects the home, it doesn't replace the income needed for daily expenses, utilities, food, transportation, and other necessities.
A comprehensive term life insurance policy equal to 10-15 times annual income provides both mortgage protection and income replacement, ensuring your family maintains their standard of living while grieving your loss.
Co-Borrowers and Joint Mortgages
When multiple people share mortgage responsibility, coordination of life insurance coverage becomes essential. Some mortgage life insurance policies cover only the primary borrower, leaving the co-borrower responsible for the full mortgage payment if their partner dies first.
Verify whether the policy covers one or both borrowers and whether it pays the full remaining balance regardless of which borrower dies first. For many couples, purchasing separate term life policies on each person provides clearer coverage and better value.
Self-Employed and Business Owners
Self-employed individuals often face more complex underwriting for traditional life insurance due to variable income documentation. However, the long-term cost savings typically justify the additional application requirements.
Business owners should also consider how business debts, partner buyout agreements, and key person insurance factor into their overall protection strategy, as these specialized needs extend beyond simple mortgage protection. Universal life insurance can provide the lifetime coverage and cash value accumulation that supports both personal protection and business planning needs.
Mortgage Life Insurance in the Broader Insurance Portfolio
Mortgage life insurance shouldn't exist in isolation but rather as one component of a comprehensive financial protection strategy that addresses all major risks to your family's security.
A well-structured insurance portfolio for homeowners typically includes:
- Adequate life insurance covering mortgage, income replacement, and legacy goals
- Disability insurance protecting against income loss due to injury or illness
- Health insurance controlling medical costs and protecting assets from healthcare expenses
- Homeowners insurance protecting the physical structure and possessions
- Umbrella liability coverage protecting assets from lawsuits and claims
- Long-term care insurance (for older homeowners) preventing asset depletion from extended care needs
SoFi’s analysis of mortgage life insurance advantages and drawbacks emphasizes that financial security requires addressing the full spectrum of risks, not just the isolated risk of dying with an outstanding mortgage balance.
Coordinating Multiple Coverage Types
When you own multiple life insurance policies, coordination prevents over-insurance while ensuring adequate coverage. Calculate your total coverage across all policies and verify it aligns with your actual protection needs based on current debts, income replacement requirements, and legacy goals.
Review your coverage annually as your mortgage balance decreases, children become financially independent, and other financial obligations change. What constituted appropriate coverage when you purchased your home may be excessive or insufficient a decade later.
Tax Implications and Estate Planning
Understanding the tax treatment of mortgage life insurance death benefits helps you evaluate the true value of coverage and integrate it effectively into your overall estate plan.
Death benefits from mortgage life insurance generally pass to the lender tax-free, paying off the mortgage without creating taxable income for your estate or beneficiaries. However, because the money goes directly to the lender rather than your estate, it doesn't increase your estate's value for distribution purposes.
With traditional life insurance where beneficiaries receive the death benefit directly, they can choose to pay off the mortgage and retain the remaining funds for other purposes. These death benefits are also typically income tax-free to beneficiaries, though they may be subject to estate taxes if your total estate exceeds federal or state exemption thresholds.
For 2026, the federal estate tax exemption remains high enough that most families won't face estate tax concerns, but state-level estate taxes may apply depending on where you live. Consulting with an estate planning attorney ensures your life insurance strategy aligns with your overall wealth transfer goals.
Recent Industry Changes and 2026 Updates
The mortgage life insurance market has evolved significantly in recent years, with regulatory changes and industry innovations affecting product availability, pricing, and features.
Several states have implemented stronger consumer protection regulations requiring clearer disclosure of how mortgage life insurance differs from traditional term life insurance. These regulations mandate that insurers provide side-by-side comparisons showing how coverage decreases over time while premiums remain level.
Additionally, some insurers now offer hybrid products combining level term coverage with mortgage balance tracking, providing beneficiaries with funds beyond the outstanding mortgage balance. These products attempt to address the flexibility limitations of traditional mortgage life insurance while maintaining simplified underwriting.
Interest rates and housing market dynamics in 2026 have also influenced mortgage life insurance demand. As mortgage balances grow with higher home prices, the gap between mortgage life insurance premiums and term life insurance premiums has widened, making traditional coverage even more attractive for healthy applicants.
Mortgage life insurance serves a specific purpose for homeowners with health conditions that prevent them from qualifying for traditional coverage, but most families receive better value and flexibility from term life insurance. Understanding how different protection options work, what they cost, and how they fit into your comprehensive financial plan enables you to make confident decisions about protecting your family's most valuable asset. At Moser Insurance Group Inc, we help individuals and families throughout Greensboro, Kernersville, High Point, and Winston-Salem understand their life insurance options with clear guidance and personalized support, ensuring you can protect your loved ones without pressure or confusion. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss which coverage approach best fits your unique situation.
Recent Comments