
When you approach retirement age, understanding medicare what is becomes one of the most important questions you'll ask yourself. Medicare serves as the federal health insurance program for millions of Americans aged 65 and older, as well as certain younger individuals with disabilities or specific health conditions. For residents throughout the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, navigating this complex system can feel overwhelming. This comprehensive guide breaks down everything you need to know about Medicare in 2026, from eligibility requirements to coverage options and costs.
Understanding Medicare Basics
Medicare represents a federal health insurance program established in 1965 to provide coverage for older Americans and specific qualifying individuals. The Centers for Medicare & Medicaid Services administers the program, which now serves over 65 million beneficiaries nationwide.
When exploring medicare what is, you must first grasp that it consists of different parts working together to provide comprehensive coverage. Each part addresses specific healthcare needs, from hospital stays to prescription medications.
The Four Main Medicare Components
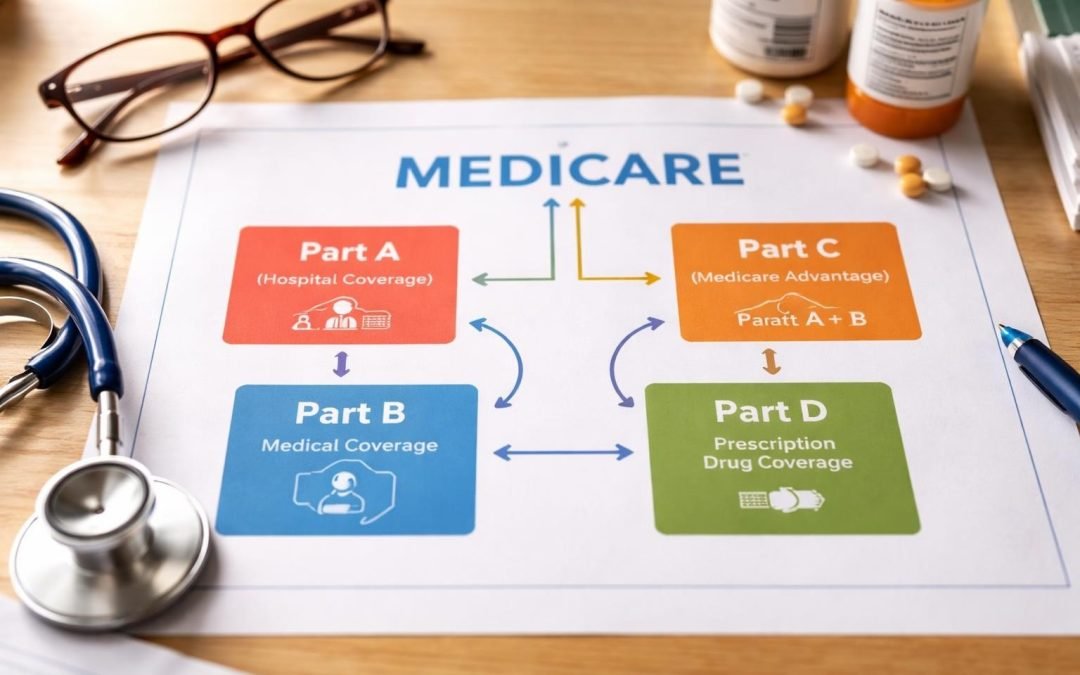
Medicare divides into four distinct parts, each covering different healthcare services:
- Part A (Hospital Insurance): Covers inpatient hospital stays, skilled nursing facility care, hospice care, and some home health services
- Part B (Medical Insurance): Covers doctor visits, outpatient care, preventive services, and medical equipment
- Part C (Medicare Advantage): Private insurance plans that combine Parts A and B, often including prescription drug coverage
- Part D (Prescription Drug Coverage): Helps cover the cost of prescription medications through private insurance companies
Medicare Part A: Hospital Insurance Coverage
Part A serves as the foundation of Medicare coverage for most beneficiaries. This component requires no monthly premium for most people who worked and paid Medicare taxes for at least 10 years (40 quarters).
Part A coverage includes inpatient hospital care, providing protection when you need to stay overnight in a hospital. The program covers semi-private rooms, meals, general nursing care, and necessary medications during your hospital stay.
What Part A Covers in Detail
| Service Type | Coverage Details | Benefit Period Limits |
|---|---|---|
| Inpatient Hospital | Semi-private room, meals, nursing | First 60 days after deductible |
| Skilled Nursing Facility | Following hospital stay of 3+ days | Up to 100 days per benefit period |
| Hospice Care | Pain relief, symptom management | No time limit if certified |
| Home Health Care | Part-time skilled nursing, therapy | As medically necessary |
In 2026, understanding medicare what is means recognizing the cost-sharing responsibilities. The Part A deductible applies for each benefit period rather than annually, making it crucial to track your hospital admissions carefully.
Medicare Part B: Medical Insurance Essentials
Part B requires a monthly premium that varies based on your income level. According to Kiplinger’s 2026 Medicare cost projections, most beneficiaries pay the standard premium, while higher-income individuals pay additional Income-Related Monthly Adjustment Amounts (IRMAA).
This Medicare component covers medically necessary services and preventive care to detect or prevent illness. Part B ensures you can visit doctors, receive outpatient treatments, and access essential medical equipment.
Key Part B Services
Part B provides extensive coverage for medical services you need outside hospital settings:
- Doctor visits and outpatient care: Regular checkups, specialist consultations, and outpatient procedures
- Preventive services: Annual wellness visits, screenings for cancer, diabetes, and cardiovascular disease
- Durable medical equipment: Wheelchairs, walkers, hospital beds, and other necessary equipment
- Mental health services: Outpatient therapy, counseling, and psychiatric care
- Laboratory tests and diagnostic services: Blood work, X-rays, and other diagnostic procedures
The program operates on a coinsurance model where you typically pay 20% of Medicare-approved amounts after meeting your annual deductible. For residents seeking Medicare age eligibility information, understanding these cost structures proves essential for budgeting healthcare expenses.
Medicare Part C: Medicare Advantage Plans
Medicare Advantage represents an alternative way to receive Medicare benefits through private insurance companies approved by Medicare. When researching medicare what is in the context of Part C, recognize that these plans must cover everything Original Medicare (Parts A and B) covers, but they often include additional benefits.
Medicare Advantage Benefits and Considerations
These plans frequently bundle multiple coverage types into one convenient package:
- Prescription drug coverage (Part D)
- Dental, vision, and hearing services
- Fitness programs and wellness benefits
- Telehealth services
- Over-the-counter medication allowances
However, major insurers have scaled back Medicare Advantage plans for 2026, affecting benefits and network availability in some regions. This makes it critical to review plans annually during the enrollment period.
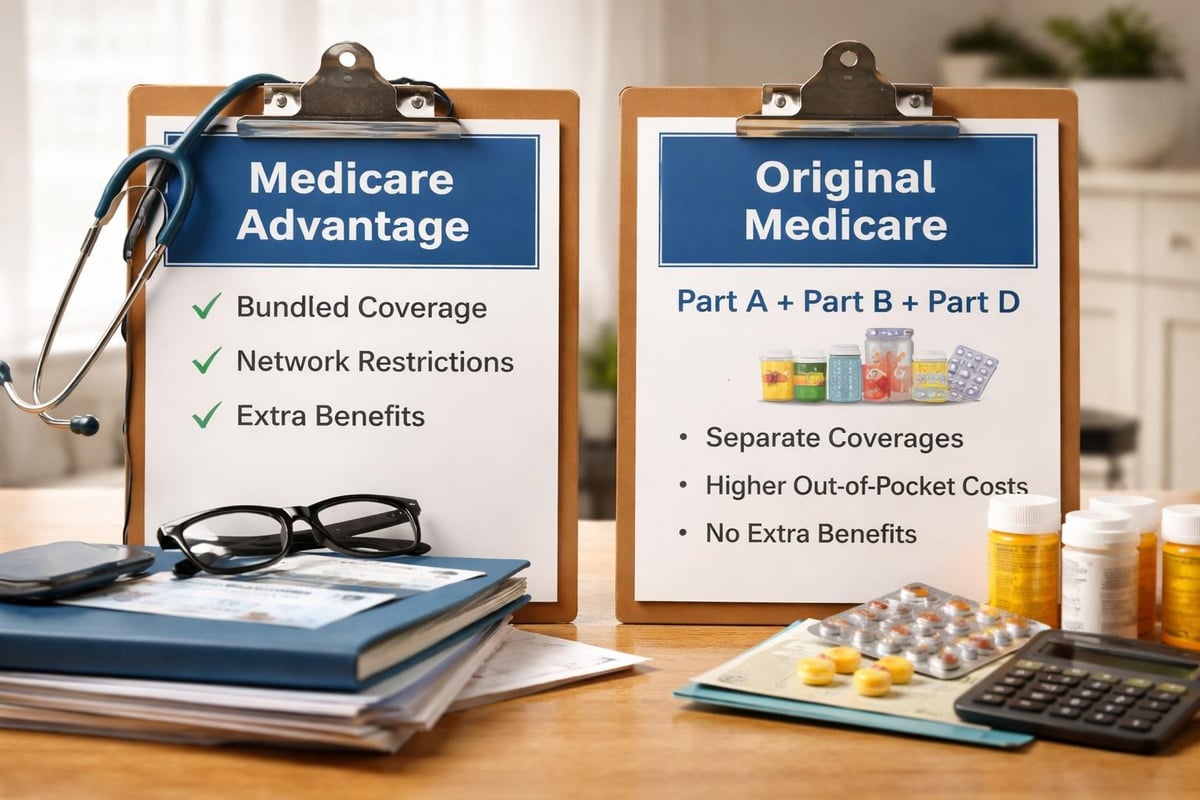
Medicare Advantage plans typically use network restrictions, meaning you must use specific doctors and hospitals except in emergencies. In the Greensboro, High Point, Winston Salem, and Kernersville areas, network availability varies significantly between insurance carriers.
| Plan Feature | Medicare Advantage | Original Medicare + Medigap |
|---|---|---|
| Network Requirements | Usually required | Any Medicare provider |
| Extra Benefits | Often included | Rarely included |
| Out-of-Pocket Maximum | Yes, capped annually | No maximum (unless Medigap) |
| Prescription Coverage | Often bundled | Requires separate Part D |
| Travel Coverage | Limited | Nationwide |
Medicare Part D: Prescription Drug Coverage
Part D provides prescription medication coverage through private insurance companies that contract with Medicare. Understanding medicare what is in relation to prescription drugs requires knowing that this coverage operates independently unless bundled within a Medicare Advantage plan.
Recent changes to Medicare prescription drug benefits for 2026 include important cost protections. The program now caps out-of-pocket expenses, providing significant financial relief for beneficiaries with high medication costs.
How Part D Plans Work
These plans organize medications into tiers, with different cost-sharing levels for each tier:
- Tier 1: Preferred generic drugs (lowest cost)
- Tier 2: Generic drugs
- Tier 3: Preferred brand-name drugs
- Tier 4: Non-preferred brand-name drugs
- Tier 5: Specialty medications (highest cost)
Each plan maintains its own formulary (list of covered drugs), making it essential to verify your medications appear on the list before enrolling. Plans can change their formularies annually, requiring careful review during enrollment periods.
Medicare Eligibility Requirements
Determining medicare what is in terms of qualification involves several pathways to coverage. Most people become eligible at age 65, but younger individuals may qualify under specific circumstances.
Primary Eligibility Criteria
Age-Based Eligibility:
You qualify for Medicare at age 65 if you or your spouse worked and paid Medicare taxes for at least 10 years. The Initial Enrollment Period begins three months before your 65th birthday month and extends three months after.
Disability-Based Eligibility:
Individuals under 65 may qualify after receiving Social Security Disability Insurance (SSDI) for 24 months. This waiting period applies to most disabilities, with certain conditions like ALS (Lou Gehrig's disease) qualifying immediately.
Specific Health Conditions:
People with End-Stage Renal Disease (ESRD) requiring dialysis or kidney transplant qualify for Medicare regardless of age. Those diagnosed with ALS become eligible for Medicare the month their disability benefits begin.
Medicare Costs for 2026
Financial planning requires understanding the various costs associated with Medicare coverage. When evaluating medicare what is from a budgetary perspective, consider premiums, deductibles, coinsurance, and copayments.
2026 Medicare Cost Breakdown
| Medicare Part | Premium | Deductible | Additional Costs |
|---|---|---|---|
| Part A | $0 for most | $1,676 per benefit period | Coinsurance after day 60 |
| Part B | $185 standard monthly | $257 annual | 20% coinsurance |
| Part C | Varies by plan | Varies by plan | Copays/coinsurance |
| Part D | Varies by plan | Varies by plan | Tiered copays |
Higher-income beneficiaries pay IRMAA surcharges on top of standard Part B and Part D premiums. These adjustments base on modified adjusted gross income from two years prior, meaning 2024 income determines 2026 IRMAA amounts.
For personalized guidance on Medicare costs specific to your situation in the Triad Area, contact Moser Insurance Group Inc at 336-862-1763 or email moserinsurancegroup@gmail.com.
Enrollment Periods and Deadlines
Medicare operates on specific enrollment timelines that determine when you can sign up or make changes to your coverage. Missing these windows can result in coverage gaps and permanent late enrollment penalties.
Critical Medicare Enrollment Windows
Initial Enrollment Period (IEP):
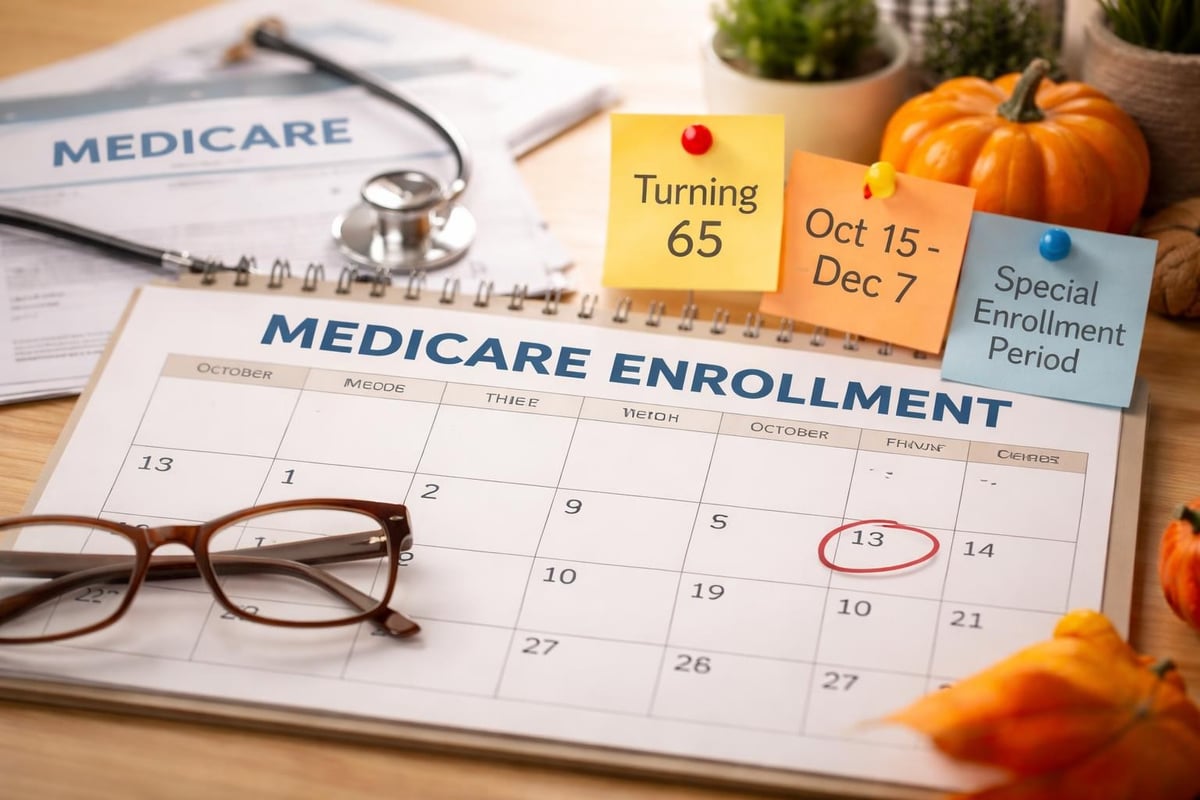
This seven-month window surrounding your 65th birthday represents your first opportunity to enroll in Medicare. It begins three months before your birthday month, includes your birthday month, and extends three months after.
General Enrollment Period (GEP):
Running from January 1 through March 31 annually, this period allows those who missed their IEP to enroll. Coverage begins July 1, and late enrollment penalties may apply permanently.
Annual Enrollment Period (AEP):
From October 15 through December 7 each year, beneficiaries can switch between Original Medicare and Medicare Advantage, change Part D plans, or add/drop coverage. Changes take effect January 1.
Special Enrollment Periods (SEP):
Qualifying life events like moving, losing employer coverage, or entering a nursing home trigger special enrollment opportunities outside standard periods.
Medigap Supplemental Insurance
Original Medicare leaves coverage gaps that create out-of-pocket expenses. Medigap (Medicare Supplement Insurance) policies help fill these gaps by covering deductibles, coinsurance, and copayments.
When considering medicare what is in relation to supplemental coverage, understand that Medigap plans work only with Original Medicare, not Medicare Advantage. Private insurance companies offer standardized plans labeled with letters (Plan A, Plan B, Plan G, etc.).
Popular Medigap Plans
- Plan G: Covers all gaps except Part B deductible; most popular option for new enrollees
- Plan N: Lower premiums with small copays for doctor visits and emergency room use
- Plan F: Comprehensive coverage but only available to those Medicare-eligible before 2020
Medigap enrollment timing matters significantly. The best time to purchase coverage is during your Medigap Open Enrollment Period, which lasts six months starting when you're 65 and enrolled in Part B. During this window, insurance companies cannot deny coverage or charge higher premiums based on health conditions.
Medicare Coordination with Other Insurance
Many people maintain other insurance coverage when becoming Medicare-eligible, creating questions about coordination of benefits. Understanding medicare what is in relation to employer coverage, COBRA, or veterans' benefits helps prevent coverage confusion.
Employer Coverage Considerations
If you or your spouse currently works and has employer health insurance with 20 or more employees, you can delay Medicare Part B enrollment without penalties. This option helps avoid paying dual premiums.
Once employer coverage ends, you receive a Special Enrollment Period to sign up for Part B without penalties. Keep documentation from your employer verifying coverage dates.
Veterans with TRICARE or VA benefits can use Medicare alongside these programs. Medicare typically pays first, with TRICARE or VA covering remaining costs. The Kaiser Family Foundation provides detailed information about how Medicare coordinates with various insurance types.
Medicare Advantage Changes for 2025 and 2026
The Centers for Medicare & Medicaid Services finalized significant payment changes affecting Medicare Advantage and Part D plans. These modifications impact plan availability, benefits, and costs throughout the Triad Area.
What's Changing
Insurance companies have adjusted their Medicare Advantage offerings in response to payment policy changes:
- Network reductions: Some plans narrowed provider networks in Greensboro, Winston Salem, and surrounding areas
- Benefit modifications: Certain extra benefits face reduction or elimination
- Premium adjustments: Plan costs shifted to reflect changing reimbursement rates
- Formulary changes: Prescription drug coverage lists updated for 2026
These changes underscore the importance of reviewing your coverage annually rather than automatically renewing. What worked well last year might not provide the same value or network access in 2026.
Making Informed Medicare Decisions
Choosing the right Medicare coverage requires careful evaluation of your health needs, budget, and preferences. When determining medicare what is best for your situation, consider multiple factors beyond just monthly premiums.
Decision-Making Framework
Assess Your Healthcare Needs:
Consider your current medications, regular doctors, and expected medical services. Do you need extensive specialist care? Do you travel frequently? These factors influence whether Original Medicare or Medicare Advantage better suits your lifestyle.
Calculate Total Costs:
Look beyond premiums to understand your complete financial picture. Include deductibles, coinsurance, copayments, and out-of-pocket maximums when comparing plans.
Verify Network Coverage:
For Medicare Advantage plans, confirm your preferred doctors and hospitals participate in the network. This proves especially important in the High Point and Kernersville areas where network options vary.
Review Prescription Coverage:
Check that your medications appear on the plan's formulary and understand which tier they occupy. Calculate your annual drug costs under different plans to identify the most cost-effective option.
Getting Professional Medicare Guidance
The complexity of Medicare options makes professional guidance valuable for most beneficiaries. Independent insurance agents provide objective comparisons across multiple carriers without favoring specific companies.
Moser Insurance Group Inc serves the Greensboro, Winston Salem, High Point, and Kernersville communities with personalized Medicare education. Rather than pushing sales, the focus remains on helping you understand your options and make confident decisions.
Local expertise matters when selecting Medicare coverage. Agents familiar with the Triad Area understand which plans offer strong provider networks at local hospitals and medical centers. They also recognize regional cost variations and community-specific healthcare resources.
For assistance understanding medicare what is and which coverage options align with your needs, visit Moser Insurance Group Inc or call 336-862-1763. You can also reach out via email at moserinsurancegroup@gmail.com to schedule a no-pressure consultation.
Resources for Medicare Information
Staying informed about Medicare changes and updates helps you maintain optimal coverage. Several reliable resources provide current information:
- Medicare.gov: Official government website with plan comparison tools and enrollment resources
- 1-800-MEDICARE: 24/7 helpline for Medicare questions and assistance
- State Health Insurance Assistance Program (SHIP): Free local counseling about Medicare options
- Social Security Administration: Information about enrollment and premium payments
Annual reviews of your coverage ensure you adapt to changing health needs and take advantage of improved plan options. The Medicare landscape shifts each year, making ongoing education essential for maximizing your benefits while minimizing costs.
Understanding medicare what is represents the first step toward securing comprehensive healthcare coverage during retirement. With multiple parts, varying costs, and numerous plan options, Medicare requires careful consideration and informed decision-making. Whether you're approaching eligibility or helping a loved one navigate enrollment, having clear, personalized guidance makes the process manageable. Moser Insurance Group Inc provides the education and support you need to choose Medicare coverage with confidence throughout the Triad Area. Contact us at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your specific situation and explore your options without pressure.
Recent Comments