

Understanding medicare what is it can feel overwhelming when you're approaching retirement or helping a loved one navigate healthcare options. Medicare is the federal health insurance program that primarily serves Americans aged 65 and older, though certain younger individuals with disabilities or specific medical conditions also qualify. As you prepare for this significant transition in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, knowing how Medicare works helps you make informed decisions about your healthcare coverage and budget. This comprehensive guide breaks down Medicare's components, eligibility requirements, costs, and enrollment procedures to help you understand what to expect.
What Medicare Actually Is and Who It Serves
Medicare what is it at its core? Medicare represents a federally funded health insurance program established in 1965 to provide healthcare coverage for older Americans and certain qualifying individuals. The Centers for Medicare & Medicaid Services (CMS) administers this program, which now serves over 65 million Americans nationwide.
The program primarily covers people who are 65 or older, regardless of income or medical history. However, younger individuals may qualify under specific circumstances:
- People under 65 with certain disabilities who have received Social Security Disability Insurance (SSDI) for 24 months
- Individuals diagnosed with End-Stage Renal Disease (ESRD) requiring dialysis or a kidney transplant
- People with Amyotrophic Lateral Sclerosis (ALS), who receive Medicare immediately upon SSDI eligibility
The Four Parts of Medicare Coverage
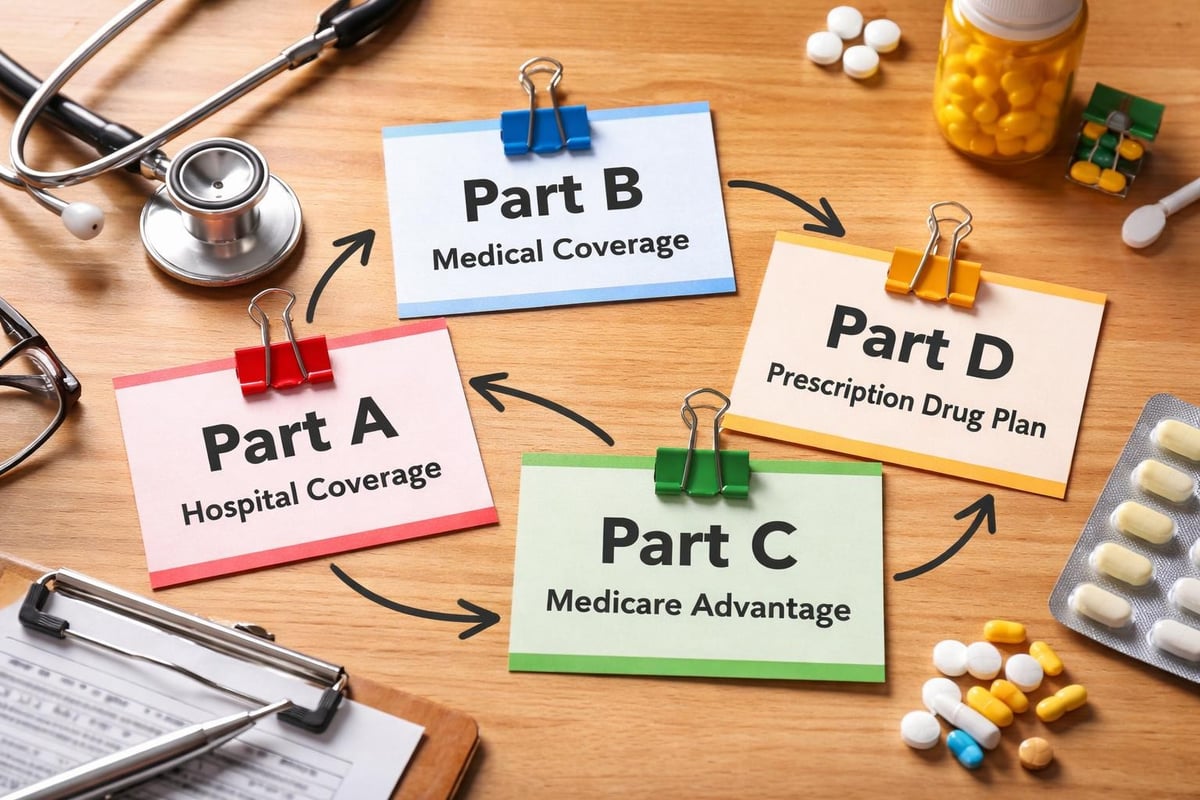
Understanding medicare what is it requires knowing that the program divides into four distinct parts, each covering different healthcare services. Many residents throughout Greensboro, Winston Salem, and High Point benefit from combining these parts to create comprehensive coverage.
Part A (Hospital Insurance) covers inpatient hospital stays, skilled nursing facility care, hospice care, and some home health services. Most people don't pay a monthly premium for Part A because they or their spouse paid Medicare taxes while working.
Part B (Medical Insurance) covers doctor visits, outpatient care, preventive services, medical equipment, and some home health services. Part B requires a monthly premium that most beneficiaries pay, with the standard amount adjusted annually.
Part C (Medicare Advantage) provides an alternative way to receive Medicare benefits through private insurance companies approved by Medicare. These plans include everything in Parts A and B, often adding prescription drug coverage and extra benefits like dental, vision, and hearing services.
Part D (Prescription Drug Coverage) helps cover the cost of prescription medications. This optional coverage comes through private insurance companies, and adding it to Original Medicare helps protect against high medication costs.
Medicare Eligibility Requirements Explained
When people ask medicare what is it in terms of qualification, the answer involves both age and work history considerations. Understanding these requirements helps you plan for enrollment timing and avoid potential penalties.
Age-Based Eligibility
The standard eligibility age for Medicare is 65. You become eligible during your Initial Enrollment Period, which includes:
- The three months before your 65th birthday month
- Your birthday month itself
- The three months following your birthday month
This seven-month window gives you ample time to enroll without facing late enrollment penalties. Residents in Kernersville and throughout the Triad Area should mark their calendars to ensure they don't miss this critical period.
Work History Requirements
To qualify for premium-free Part A, you or your spouse must have worked and paid Medicare taxes for at least 10 years (40 quarters). If you don't meet this requirement, you can still purchase Part A coverage, though monthly premiums apply based on your work history.
| Work Credits | Part A Premium (2026) |
|---|---|
| 30-39 quarters | Approximately $285/month |
| Less than 30 quarters | Approximately $518/month |
| 40+ quarters | $0/month |
Special Enrollment Situations
Some circumstances allow for Special Enrollment Periods beyond the standard Initial Enrollment Period. These include:
- Losing employer-sponsored health coverage
- Moving outside your plan's service area
- Qualifying for Extra Help with prescription drug costs
- Entering or leaving a skilled nursing facility
Understanding Medicare enrollment periods helps ensure continuous coverage without penalties.
Medicare Costs in 2026
Answering medicare what is it from a financial perspective requires examining premiums, deductibles, and out-of-pocket costs. Medicare costs for 2025 and beyond continue to evolve, making it essential to stay informed about current rates.
Part A Costs
Most beneficiaries pay no monthly premium for Part A. However, you'll encounter other costs:
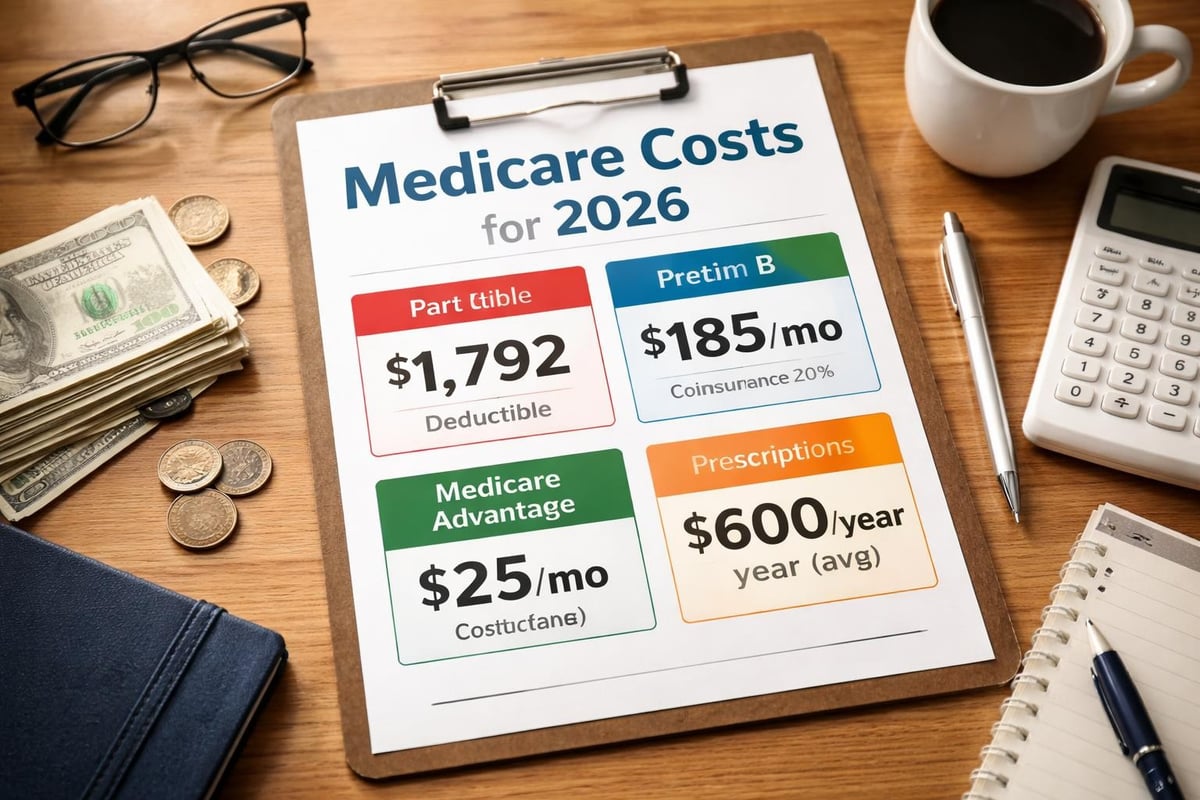
- Hospital deductible: $1,676 per benefit period (2026 estimate)
- Daily coinsurance: Applies for extended hospital stays beyond 60 days
- Skilled nursing facility coinsurance: $209.50 per day for days 21-100
Part B Costs
Part B requires monthly premiums based on your income level. The standard premium for 2026 is approximately $185 per month, though high-income earners pay more through Income-Related Monthly Adjustment Amounts (IRMAA).
Part B also includes:
- Annual deductible of approximately $257
- 20% coinsurance for most services after meeting the deductible
- No out-of-pocket maximum under Original Medicare
Part C and D Costs
Medicare Advantage plans vary widely in cost depending on the insurance company and specific plan. You'll still pay your Part B premium plus any additional plan premium. These plans include annual out-of-pocket maximums that provide financial protection.
Part D premiums also vary by plan, with the national average around $45 per month. New Medicare changes for 2026 include a $2,000 cap on out-of-pocket prescription drug costs, providing significant relief for those with high medication expenses.
Original Medicare vs Medicare Advantage
Understanding medicare what is it means recognizing you have choices in how you receive benefits. The decision between Original Medicare and Medicare Advantage represents one of the most important choices you'll make. Our team at Moser Insurance Group Inc helps residents throughout High Point, Winston Salem, and Greensboro evaluate differences in Medicare plans to find the best fit.
Original Medicare (Parts A & B)
Original Medicare provides coverage directly through the federal government. You can see any doctor or specialist who accepts Medicare nationwide without needing referrals.
Benefits of Original Medicare:
- Freedom to choose healthcare providers
- No network restrictions when traveling
- Consistent coverage rules nationwide
- Ability to add a Medigap policy for additional coverage
Limitations include:
- No coverage for prescription drugs (requires separate Part D)
- No out-of-pocket maximum
- Limited coverage for dental, vision, and hearing
- 20% coinsurance can add up without supplemental coverage
Medicare Advantage (Part C)
Private insurance companies offer Medicare Advantage plans as an alternative to Original Medicare. These plans must cover everything Original Medicare covers but often include additional benefits.
Medicare Advantage advantages:
- Often includes prescription drug coverage
- Annual out-of-pocket maximums
- Extra benefits like dental, vision, hearing, and fitness programs
- Potentially lower overall costs for some beneficiaries
Considerations include:
- Network restrictions (HMO, PPO, or other plan types)
- May require referrals to see specialists
- Coverage varies by plan and location
- Need to switch plans if you move
| Feature | Original Medicare | Medicare Advantage |
|---|---|---|
| Provider Network | Any Medicare provider | Plan network (varies) |
| Out-of-Pocket Max | None | Yes (plan-specific) |
| Prescription Drugs | Separate Part D needed | Often included |
| Extra Benefits | No | Often included |
| Premiums | Part B + possible Part D | Part B + plan premium |
Supplemental Coverage Options
When exploring medicare what is it in terms of comprehensive protection, many beneficiaries choose supplemental coverage to fill gaps in Original Medicare. These options help manage out-of-pocket costs and provide financial predictability.
Medigap Policies
Medicare Supplement plans help cover costs that Original Medicare doesn't, such as deductibles, coinsurance, and copayments. Standardized plans lettered A through N each offer different coverage levels.
Popular Medigap plans include:
- Plan G: Covers all gaps except the Part B deductible, making it the most comprehensive option available to new beneficiaries
- Plan N: Offers slightly lower premiums with small copays for doctor visits and emergency room use
- Plan F: Only available to those who became Medicare-eligible before January 1, 2020
Prescription Drug Coverage
If you choose Original Medicare, adding Part D prescription drug coverage protects you from high medication costs. The coverage gap, often called the "donut hole," has closed significantly due to recent legislation, and the Part D coverage gap continues to improve for beneficiaries.
Employer Coverage Coordination
Many people wonder about medicare what is it in relation to employer coverage. If you or your spouse still work and have employer health insurance, you may be able to delay Medicare enrollment without penalty. However, this depends on the employer's size and specific circumstances. Companies with 20 or more employees typically provide primary coverage, allowing you to delay Part B enrollment.
Enrollment Processes and Important Deadlines
Understanding medicare what is it from an enrollment perspective helps you avoid costly mistakes and coverage gaps. The enrollment system includes several different periods, each with specific rules and deadlines.
Initial Enrollment Period
Your Initial Enrollment Period begins three months before your 65th birthday month and extends three months after. During this seven-month window, you can enroll in Medicare Parts A and B, choose between Original Medicare or Medicare Advantage, and add prescription drug coverage.
Enrollment tips for success:
- Apply online at SSA.gov, by phone, or at your local Social Security office
- Consider your healthcare needs and budget before choosing coverage
- Research available plans in your area
- Don't miss the deadline to avoid late enrollment penalties
Annual Enrollment Period
The Annual Enrollment Period runs from October 15 through December 7 each year. During this time, all Medicare beneficiaries can:
- Switch from Original Medicare to Medicare Advantage or vice versa
- Change Medicare Advantage plans
- Add, drop, or switch Part D prescription drug plans
- Add or drop a Medigap policy (subject to medical underwriting in most states)
Changes made during this period take effect January 1 of the following year. The American Hospital Association reports on payment changes that may affect plan availability and costs during each enrollment period.
Special Enrollment Periods
Life changes can trigger Special Enrollment Periods that allow you to modify coverage outside the standard timeframes. Qualifying events include moving to a new area, losing current coverage, or qualifying for financial assistance programs.
Medicare in North Carolina's Triad Area
For residents wondering medicare what is it like in our region, North Carolina offers robust Medicare options throughout Greensboro, Winston Salem, High Point, and Kernersville. The Triad Area provides access to quality healthcare facilities and numerous plan choices.
Local Healthcare Access
Medicare beneficiaries in the Triad Area can access excellent medical facilities including:
- Major hospital systems throughout Greensboro and Winston Salem
- Specialized care centers in High Point
- Primary care networks across Kernersville
- Urgent care facilities accepting Medicare throughout the region
Plan Availability
North Carolina residents typically have access to multiple Medicare Advantage plans, prescription drug plans, and Medigap policies. Plan availability and costs vary by county, making it important to review options specific to your zip code.
Working with a local insurance professional helps you navigate North Carolina health insurance Medicare options and find plans that include your preferred doctors and medications.
Medicare and Social Security Integration
Medicare what is it in relationship to Social Security? These two programs interconnect in several important ways. If you're already receiving Social Security benefits when you turn 65, you'll automatically be enrolled in Medicare Parts A and B. Your Medicare card arrives in the mail about three months before your 65th birthday.
Understanding Social Security and Medicare coordination helps you plan for retirement effectively. You can decline Part B if you have other coverage, but you must do so actively to avoid paying premiums.
Future of Medicare and Recent Changes
The question medicare what is it evolving into becomes increasingly relevant as the program adapts to changing healthcare needs. Major Medicare changes continue to reshape coverage and costs.
Financial Sustainability
According to the Associated Press, Medicare faces financial challenges due to rising healthcare costs and demographic shifts. However, legislative changes continue to strengthen the program and improve benefits for current and future beneficiaries.
Recent Improvements
Recent years have brought significant enhancements:
- Elimination of cost-sharing for many preventive services
- Closure of the Part D coverage gap
- Implementation of the $2,000 out-of-pocket drug cost cap for 2026
- Expanded telehealth coverage options
- Enhanced Medicare enrollment and coverage rules
Getting Personalized Medicare Help
Understanding medicare what is it represents just the first step. Applying this knowledge to your specific situation requires personalized guidance. Every individual's healthcare needs, budget, and preferences differ, making one-on-one consultation valuable.
Questions to Consider
Before enrolling, think about:
- Which doctors and specialists do you want to keep seeing?
- What prescription medications do you take regularly?
- How much can you budget for monthly premiums versus potential out-of-pocket costs?
- Do you travel frequently or spend time in multiple locations?
- What additional benefits matter most to you (dental, vision, hearing, fitness)?
Local Resources and Support
Residents throughout the Triad Area can access Medicare assistance through various channels. Whether you're turning 65 in Kernersville or helping a parent in Winston Salem understand their options, local support makes the process manageable.
For immediate assistance, you can reach us at:
- Phone: 336-862-1763
- Email: moserinsurancegroup@gmail.com
- Website: moserinsurancegroup.com
Medicare Advantage Plan Features
When considering medicare what is it in terms of comprehensive coverage, Medicare Advantage plans deserve special attention. These plans often include benefits beyond Original Medicare that address common healthcare needs.
Common Additional Benefits
Many Medicare Advantage plans in the Triad Area include:
- Dental coverage for preventive care, basic procedures, and sometimes major work
- Vision benefits including routine eye exams and allowances for glasses or contacts
- Hearing services with coverage for exams and hearing aids
- Fitness programs like Silver Sneakers for gym access
- Over-the-counter allowances for health-related items
- Transportation to medical appointments
- Telehealth services for convenient care access
Plan Types Explained
Medicare Advantage plans come in several varieties:
Health Maintenance Organization (HMO) plans require you to use network providers and typically need referrals to see specialists. These plans often offer lower premiums and predictable costs.
Preferred Provider Organization (PPO) plans provide more flexibility, allowing you to see out-of-network providers at higher costs. You don't need referrals for specialists.
Private Fee-for-Service (PFFS) plans determine how much they'll pay providers and how much you pay when receiving care. Not all providers accept these plans.
Special Needs Plans (SNP) serve specific populations, such as those with chronic conditions, dual Medicare-Medicaid eligibility, or institutional care needs.
Understanding medicare what is it empowers you to make confident decisions about your healthcare coverage as you approach 65 or experience qualifying life events. From the basic structure of Parts A, B, C, and D to the nuances of enrollment periods and supplemental coverage, each element plays a role in your overall healthcare security. At Moser Insurance Group Inc, we help individuals and families throughout Greensboro, Winston Salem, High Point, and Kernersville navigate Medicare options with clear guidance and personalized support. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your Medicare questions and find coverage that fits your needs without pressure or confusion.
Recent Comments