

Getting a medicare quote might seem straightforward, but understanding what you're actually comparing requires more than just looking at monthly premiums. Whether you're approaching your 65th birthday, retiring early, or helping a family member navigate Medicare for the first time, the quote process reveals critical differences in coverage, costs, and benefits that directly impact your healthcare experience. The right quote helps you see beyond the surface numbers to understand deductibles, copayments, prescription drug coverage, and provider networks that shape your actual out-of-pocket expenses throughout the year.
Understanding What a Medicare Quote Actually Includes
A comprehensive medicare quote goes far beyond a simple monthly premium figure. It represents a snapshot of your potential healthcare costs across multiple dimensions, including hospital coverage, doctor visits, prescription medications, and preventive services.
When you request a quote, you're evaluating how different Medicare options align with your health status, preferred doctors, medication needs, and budget. The quote process examines Original Medicare (Parts A and B), Medicare Advantage plans (Part C), prescription drug plans (Part D), and Medicare Supplement plans that fill coverage gaps.
Breaking Down the Core Components
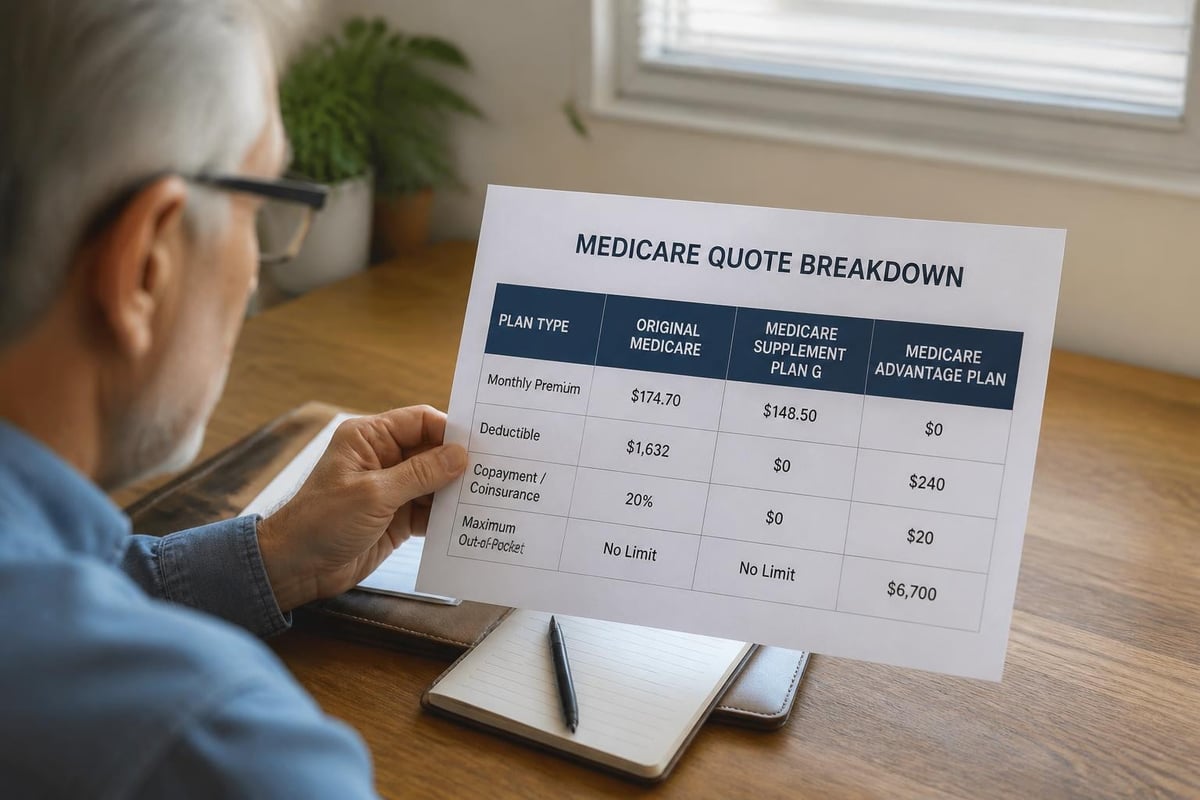
Every medicare quote should clearly itemize several essential cost categories:
- Monthly premium: The amount you pay each month for coverage
- Annual deductible: What you pay before insurance starts covering costs
- Copayments and coinsurance: Your share of costs for each service
- Out-of-pocket maximum: The most you'll pay in a year for covered services
- Prescription drug coverage: Formulary tiers and pharmacy networks
The Centers for Medicare & Medicaid Services provides detailed information on how Medicare functions, which helps clarify what each quote component means for your actual healthcare access.
Comparing Original Medicare vs. Medicare Advantage Quotes
One of the most significant decisions reflected in your medicare quote is choosing between Original Medicare and Medicare Advantage. These two pathways offer fundamentally different approaches to healthcare coverage.
Original Medicare consists of Part A (hospital insurance) and Part B (medical insurance), providing nationwide coverage with freedom to see any provider who accepts Medicare assignment. Most people don't pay a premium for Part A, but Part B requires a standard monthly premium of approximately $174.70 in 2026 for most beneficiaries.
Medicare Advantage plans, by contrast, bundle Parts A, B, and usually D (prescription drugs) into a single plan offered by private insurance companies. Understanding the comparison between Original Medicare and Medicare Advantage is essential before evaluating quotes.
| Feature | Original Medicare | Medicare Advantage |
|---|---|---|
| Provider Network | Any Medicare-accepting provider nationwide | Restricted to plan network (HMO/PPO) |
| Monthly Premium | Part B premium only | Part B premium + plan premium (sometimes $0) |
| Out-of-Pocket Maximum | None (unless you add Medigap) | Annual cap (typically $7,550-$8,850) |
| Prescription Coverage | Requires separate Part D plan | Usually included |
| Extra Benefits | Not included | Often includes dental, vision, hearing |
Geographic Considerations for Medicare Quotes
Location significantly affects medicare quote options and costs. In the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, beneficiaries have access to multiple carriers with varying plan designs and premium structures.
Network availability differs substantially across these communities. A plan with excellent provider coverage in Greensboro might have limited options in Kernersville, making it essential to verify that your preferred doctors and hospitals participate in any plan you're considering.
Medicare Supplement plans offer standardized benefits across all carriers, but premiums vary based on your age, location, and the insurance company's rating method. This makes comparing quotes from multiple carriers particularly valuable.
The Medicare Quote Process: Step-by-Step
Obtaining an accurate medicare quote requires gathering specific information and understanding your coverage priorities. The process becomes more manageable when you prepare the necessary documentation and clarify your healthcare needs in advance.
Information You'll Need
- Medicare number and effective dates: From your red, white, and blue Medicare card
- Current medications: Complete list with dosages
- Preferred doctors and facilities: Names and locations
- Income information: For premium subsidy eligibility (Part D)
- Current health conditions: To assess coverage adequacy
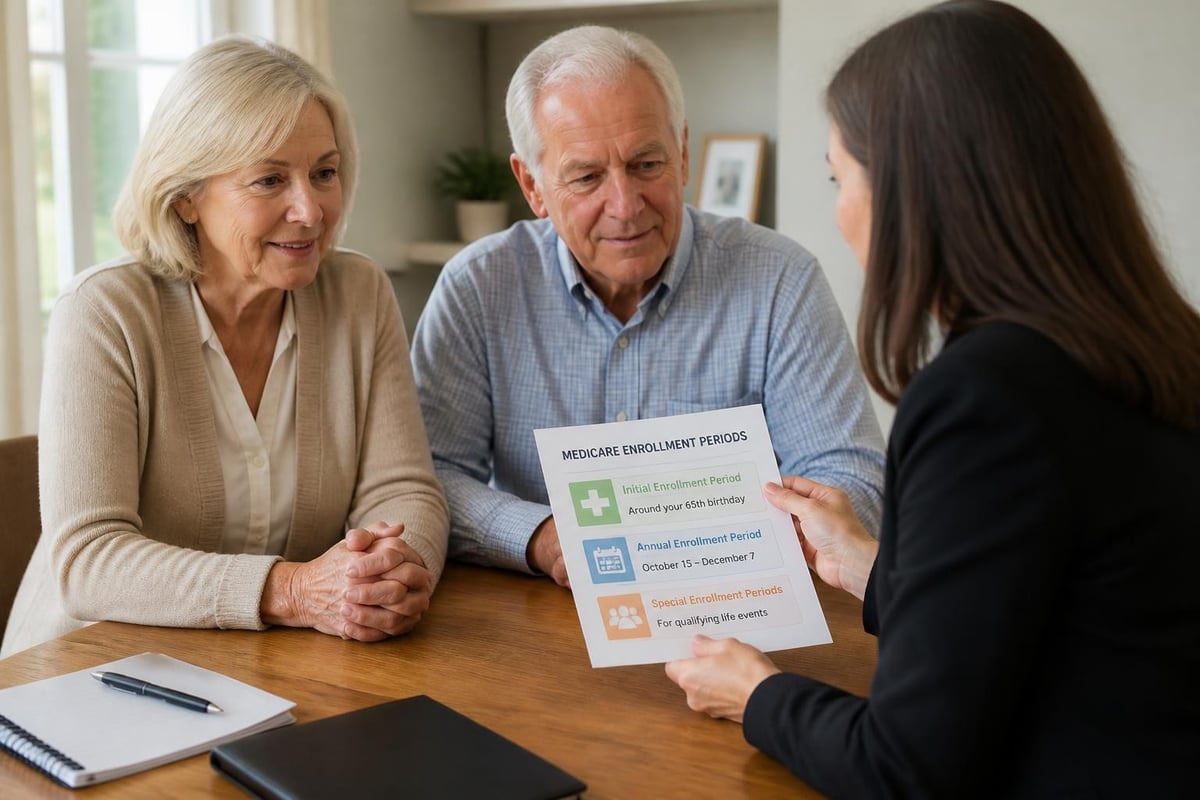
Starting three months before your 65th birthday gives you adequate time to compare options during your Initial Enrollment Period. For those already enrolled, the Annual Enrollment Period (October 15 – December 7) allows plan changes effective January 1st.
Questions to Ask When Reviewing Quotes
- Does this plan cover my current specialists and primary care physician?
- Are my prescription medications included in the formulary?
- What are the total estimated annual costs, not just monthly premiums?
- Are there prior authorization requirements for specific treatments?
- What happens if I need care while traveling?
The MedPAC Medicare 101 guide provides comprehensive background on eligibility and benefits that helps you evaluate whether quotes align with program requirements.
Prescription Drug Coverage in Your Medicare Quote
Prescription drug costs represent a substantial portion of healthcare expenses for many Medicare beneficiaries, making Part D coverage analysis a critical component of any medicare quote.
Each Part D plan organizes medications into tiers, with generic drugs typically costing less than brand-name medications. Your out-of-pocket costs depend on which tier your medications fall into and whether you're using preferred pharmacies within the plan's network.
Understanding the Coverage Gap
The Part D coverage gap, commonly called the "donut hole," affects how much you pay for medications after reaching certain spending thresholds. In 2026, you enter the gap after your total drug costs reach approximately $5,030.
During this phase, you pay 25% of the cost for both brand-name and generic drugs. Once your out-of-pocket spending reaches about $8,000, catastrophic coverage begins and your costs drop significantly.
When comparing medicare quote options that include prescription coverage, use the plan finder tools to enter your specific medications. This generates accurate cost estimates rather than relying on general premium comparisons.
Medicare Supplement Insurance Quotes
For beneficiaries choosing Original Medicare, Medicare Supplement insurance (Medigap) fills coverage gaps by paying deductibles, copayments, and coinsurance that Original Medicare doesn't cover.
Medigap plans are standardized and labeled with letters (Plan A, Plan G, Plan N, etc.). Plan G has become the most popular option since Plan F became unavailable to new Medicare beneficiaries after January 1, 2020.
A medicare quote for Medigap coverage focuses primarily on monthly premiums since benefits are standardized. However, insurance companies use different rating methods that affect how premiums increase over time:
- Community-rated: Same premium regardless of age
- Issue-age-rated: Based on age when you first buy
- Attained-age-rated: Increases as you get older
Medigap Enrollment Timing
Your six-month Medigap Open Enrollment Period begins when you're 65 or older and enrolled in Part B. During this window, insurance companies cannot deny coverage or charge higher premiums based on health conditions.
Outside this period, medical underwriting typically applies, potentially resulting in higher premiums or coverage denial. This makes getting an initial medicare quote during your optimal enrollment window particularly important.
Medicare Advantage Plan Quote Considerations
Medicare Advantage plans from private insurers often feature $0 premiums, making them appear more affordable than Original Medicare with Medigap. However, a thorough medicare quote analysis examines total potential costs, not just monthly premiums.
Star Ratings and Quality Measures
Medicare assigns Star Ratings (1-5 stars) to Medicare Advantage and Part D plans based on quality and performance. Plans with higher ratings often provide better member experiences, though ratings alone shouldn't determine your choice.
When reviewing quotes for top Medicare Advantage plans, consider both ratings and practical factors like provider networks and pharmacy coverage.
| Plan Feature | What to Verify |
|---|---|
| Primary Care Copay | Typical $0-$25 per visit |
| Specialist Copay | Usually $30-$50 per visit |
| Hospital Costs | Daily copays or coinsurance |
| Maximum Out-of-Pocket | Your financial risk ceiling |
| Part D Coverage | Included or separate required |
Additional benefits like dental, vision, hearing, and fitness memberships (such as Silver Sneakers) add value beyond traditional Medicare but shouldn't overshadow fundamental coverage quality.
Special Considerations for Different Situations
Medicare beneficiaries face varying circumstances that affect which quotes provide the most relevant comparisons. Understanding your specific situation ensures you're evaluating appropriate plan types.
Working Past 65
If you or your spouse continue working past 65 with employer coverage of 20 or more employees, you may delay Part B enrollment without penalty. However, you should still obtain a medicare quote to compare employer coverage with Medicare options.
For those with smaller employer groups (fewer than 20 employees), Medicare becomes primary coverage, and coordination of benefits changes significantly.
Chronic Conditions and High Healthcare Utilization
Beneficiaries with ongoing health conditions or regular specialist visits should focus medicare quote comparisons on out-of-pocket maximums and specialist copays rather than low monthly premiums.
A plan with a $0 premium but $50 specialist copays and a $7,500 out-of-pocket maximum might cost significantly more annually than a plan with a $40 monthly premium but lower per-visit costs and a $3,000 maximum.
Research from the Kaiser Family Foundation on coverage sources shows that beneficiaries with supplemental coverage have lower out-of-pocket spending, highlighting the importance of comprehensive quote analysis.
Digital Tools and Resources for Medicare Quotes
Technology has streamlined the medicare quote process, offering online tools that compare plans based on your specific location, medications, and preferred providers.
The official Medicare Plan Finder at Medicare.gov allows you to:
- Enter your ZIP code to see available plans
- Input medications to compare drug costs
- Check if specific doctors and hospitals participate
- View total estimated annual costs
- Read plan reviews from current members
Third-party comparison sites also aggregate medicare quote information, though it's essential to verify that these platforms display all available options, not just those that pay referral fees.
Working with Licensed Insurance Professionals
While online tools provide valuable data, personalized guidance from licensed insurance agents helps interpret quotes within the context of your unique healthcare needs and financial situation.
Licensed professionals can explain nuances that online comparisons might overlook, such as prior authorization requirements, step therapy protocols, and how plans handle specialist referrals.
At Moser Insurance Group Inc, clients receive educational support without pressure tactics. You can reach our team at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your medicare quote options in detail.
Common Medicare Quote Mistakes to Avoid
Many beneficiaries make preventable errors when comparing medicare quote options, leading to coverage gaps or unexpected costs.
Focusing exclusively on monthly premiums: A plan with a low premium might have high deductibles, copays, or limited provider networks that cost more annually.
Not verifying provider participation: Assuming your doctor accepts all Medicare plans can result in out-of-network charges or the need to change physicians.
Ignoring prescription drug coverage: Skipping Part D enrollment when you don't currently take medications can result in late enrollment penalties if you need coverage later.
Overlooking enrollment deadlines: Missing your Initial Enrollment Period can trigger lifetime Part B premium penalties of 10% for each 12-month period you were eligible but didn't enroll.
Choosing based on advertising alone: Plans that advertise heavily might not offer the best value for your specific healthcare needs and location.
Understanding Medicare Costs Beyond the Quote
A medicare quote represents projected costs, but understanding how Medicare is funded and structured helps you anticipate potential future changes.
The funding mechanisms of Medicare rely on payroll taxes, premiums, and general revenue. Part A is primarily funded through payroll taxes, while Part B combines premiums with general tax revenue.
Income-Related Monthly Adjustment Amounts (IRMAA) affect higher-income beneficiaries, adding surcharges to Part B and Part D premiums based on tax returns from two years prior. For 2026, IRMAA thresholds begin at modified adjusted gross incomes above $103,000 for individuals or $206,000 for couples.
Provider Assignment and Your Costs
When reviewing a medicare quote for Original Medicare, understanding provider assignment impacts your final costs. Providers who accept assignment agree to Medicare's approved amount as full payment, limiting your cost share to applicable deductibles and coinsurance.
Non-participating providers can charge up to 15% above Medicare's approved amount, increasing your out-of-pocket expenses. The importance of choosing providers who accept Medicare assignment becomes clear when managing healthcare budgets.
Making Your Final Decision
After collecting multiple medicare quote options, organizing your findings helps clarify which plan best balances coverage, costs, and convenience for your situation.
Create a comparison spreadsheet that includes:
- Monthly premium amounts
- Annual deductibles
- Estimated prescription drug costs
- Copays for primary care and specialists
- Total projected annual costs
- Provider network adequacy
- Extra benefits included
Review this information alongside your healthcare priorities. If maintaining your current doctors matters most, network adequacy outweighs premium savings. If you take multiple medications, prescription coverage quality becomes paramount.
Making Changes After Initial Enrollment
Medicare provides specific periods for changing coverage if your initial choice doesn't meet expectations. The Annual Enrollment Period allows switches between Original Medicare and Medicare Advantage or changes to different plans within the same category.
The Medicare Advantage Open Enrollment Period (January 1 – March 31) provides an additional opportunity for those in Medicare Advantage plans to switch to different Medicare Advantage plans or return to Original Medicare.
Understanding these windows ensures you're not locked into unsuitable coverage for extended periods.
Getting Personalized Support for Your Medicare Quote
Navigating medicare quote comparisons becomes significantly easier with expert guidance tailored to your specific circumstances. Whether you're turning 65, retiring, or simply reviewing your current coverage during the annual enrollment period, personalized support ensures you understand all available options.
Educational resources at moserinsurancegroup.com provide additional information about Medicare plans, enrollment periods, and coverage decisions. Professional advisors help you interpret quotes, verify provider participation, and understand how different plan structures affect your actual healthcare costs throughout the year.
Getting an accurate medicare quote requires understanding multiple cost components, coverage differences, and how various plan types align with your healthcare needs and budget. Whether you're considering Original Medicare with supplemental coverage or exploring Medicare Advantage options in the Triad Area, having clear information empowers confident decision-making. Moser Insurance Group Inc specializes in helping individuals and families throughout Greensboro, Kernersville, High Point, and Winston Salem understand their Medicare options without pressure or confusion. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com to discuss your medicare quote options and make informed coverage decisions.
Recent Comments