

Medicare Part G coverage has become one of the most popular supplemental insurance options for beneficiaries seeking comprehensive protection against out-of-pocket healthcare costs. Understanding what this plan covers, how it differs from Original Medicare, and whether it fits your specific healthcare needs is essential for making informed decisions about your Medicare coverage. This guide breaks down the key aspects of Medicare Part G coverage to help you determine if it's the right choice for your situation.
What Is Medicare Part G Coverage
Medicare Part G coverage, technically known as Medicare Supplement Plan G or Medigap Plan G, is a standardized insurance policy sold by private insurance companies to fill the gaps in Original Medicare. Unlike Medicare Part A (hospital insurance) and Part B (medical insurance), which are federal programs, Medicare Supplement Plan G is offered through private insurers but must follow federal guidelines for standardization.
The "G" designation refers to a specific set of benefits that this plan must provide, regardless of which insurance company sells the policy. This standardization means that Plan G from one company offers the same core benefits as Plan G from another company, though premiums and customer service may vary.
How Medicare Part G Coverage Works With Original Medicare
To enroll in medicare part g coverage, you must already have both Medicare Part A and Part B. The supplement plan then works alongside Original Medicare to cover many of the costs that you would otherwise pay out of pocket.
Here's the typical coverage flow:
- Medicare Part A and Part B pay their share of approved healthcare costs
- Medicare Part G coverage pays most of the remaining costs
- You're responsible for the Part B deductible and your monthly premiums
This coordinated coverage means fewer surprise medical bills and more predictable healthcare expenses throughout the year. For residents in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, having this comprehensive coverage provides peace of mind when accessing healthcare services.
Benefits Included in Medicare Part G Coverage
Medicare part g coverage provides extensive benefits that make it one of the most comprehensive Medigap plans available. According to Medicare.org’s comprehensive guide, Plan G covers virtually all gaps in Original Medicare except for the Part B deductible.
| Benefit Category | Coverage Details |
|---|---|
| Part A coinsurance and hospital costs | Up to an additional 365 days after Medicare benefits are exhausted |
| Part B coinsurance or copayment | 100% coverage for approved services |
| Blood (first 3 pints) | Fully covered |
| Part A hospice care coinsurance or copayment | 100% coverage |
| Skilled nursing facility care coinsurance | 100% coverage |
| Part A deductible | Fully covered ($1,676 in 2026) |
| Part B deductible | Not covered (you pay $257 in 2026) |
| Part B excess charges | 100% coverage |
| Foreign travel emergency | Up to plan limits (80% after $250 deductible) |
Part A Benefits Coverage
The medicare part g coverage extends your Part A hospital insurance benefits significantly. When you're hospitalized, Original Medicare covers most costs but leaves you responsible for deductibles and coinsurance after certain periods. Plan G eliminates these gaps.
Specific Part A benefits include:
- Full coverage of the Part A hospital deductible for each benefit period
- Coinsurance for days 61-90 of hospitalization
- Coinsurance for lifetime reserve days
- 100% coverage for an additional 365 days of hospital care after Medicare benefits end
These benefits prove especially valuable for individuals requiring extended hospital stays or multiple hospitalizations throughout the year.
Part B Benefits Coverage
For outpatient services covered under Part B, medicare part g coverage pays the 20% coinsurance that Original Medicare doesn't cover. This applies to doctor visits, outpatient procedures, durable medical equipment, and many preventive services.
Additionally, Plan G covers Part B excess charges, which occur when doctors who don't accept Medicare assignment charge up to 15% more than the Medicare-approved amount. While most doctors accept assignment, this protection eliminates any risk of surprise bills from those who don't.
Understanding Medicare Part G Coverage Costs
The costs associated with medicare part g coverage fall into two main categories: premiums and deductibles. As noted in Medical News Today’s cost analysis, premiums vary significantly based on several factors.
Monthly Premium Factors
Your monthly premium for medicare part g coverage depends on multiple variables that insurance companies use to calculate rates:
- Geographic location – Premiums in the Triad Area, Greensboro, Kernersville, High Point, and Winston Salem may differ from other regions
- Age – Most insurers use attained-age pricing where premiums increase as you get older
- Gender – Some states allow gender-based pricing
- Tobacco use – Smokers typically pay higher premiums
- Household discounts – Some insurers offer discounts when both spouses enroll
The average monthly premium for Plan G in 2026 ranges from $140 to $250, though rates can fall outside this range depending on your specific circumstances. Contact Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com to get personalized quotes for your situation.
Out-of-Pocket Deductibles
While medicare part g coverage eliminates most out-of-pocket costs, you remain responsible for the Medicare Part B annual deductible. For 2026, this deductible is $257. Once you meet this deductible, Plan G covers virtually all remaining costs for Medicare-approved services.
Medicare Part G Coverage vs. Other Medigap Plans
Understanding how medicare part g coverage compares to other supplement options helps you make an informed choice. The two plans most commonly compared are Plan G and Plan N.
Plan G vs. Plan N Comparison
| Feature | Plan G | Plan N |
|---|---|---|
| Part B deductible | You pay | You pay |
| Part B coinsurance | 100% covered | Copays up to $20 (office) or $50 (ER) |
| Part B excess charges | Covered | Not covered |
| Monthly premium | Higher | Lower |
| Predictability | More predictable | Less predictable |
Plan N offers lower monthly premiums but requires copays for certain services. Medicare part g coverage provides more comprehensive benefits with fewer out-of-pocket surprises at the point of service.
High-Deductible Plan G Option
Some insurers offer a high-deductible version of medicare part g coverage. This option requires you to pay all Medicare cost-sharing up to an annual deductible ($2,870 in 2026) before the plan begins paying benefits. After meeting the deductible, the plan covers the same benefits as standard Plan G.
This option appeals to beneficiaries who:
- Want lower monthly premiums
- Have substantial savings to cover potential medical costs
- Are generally healthy and expect minimal healthcare expenses
Enrollment Periods for Medicare Part G Coverage
Timing matters when enrolling in medicare part g coverage. Your enrollment period affects your costs and whether you need medical underwriting.
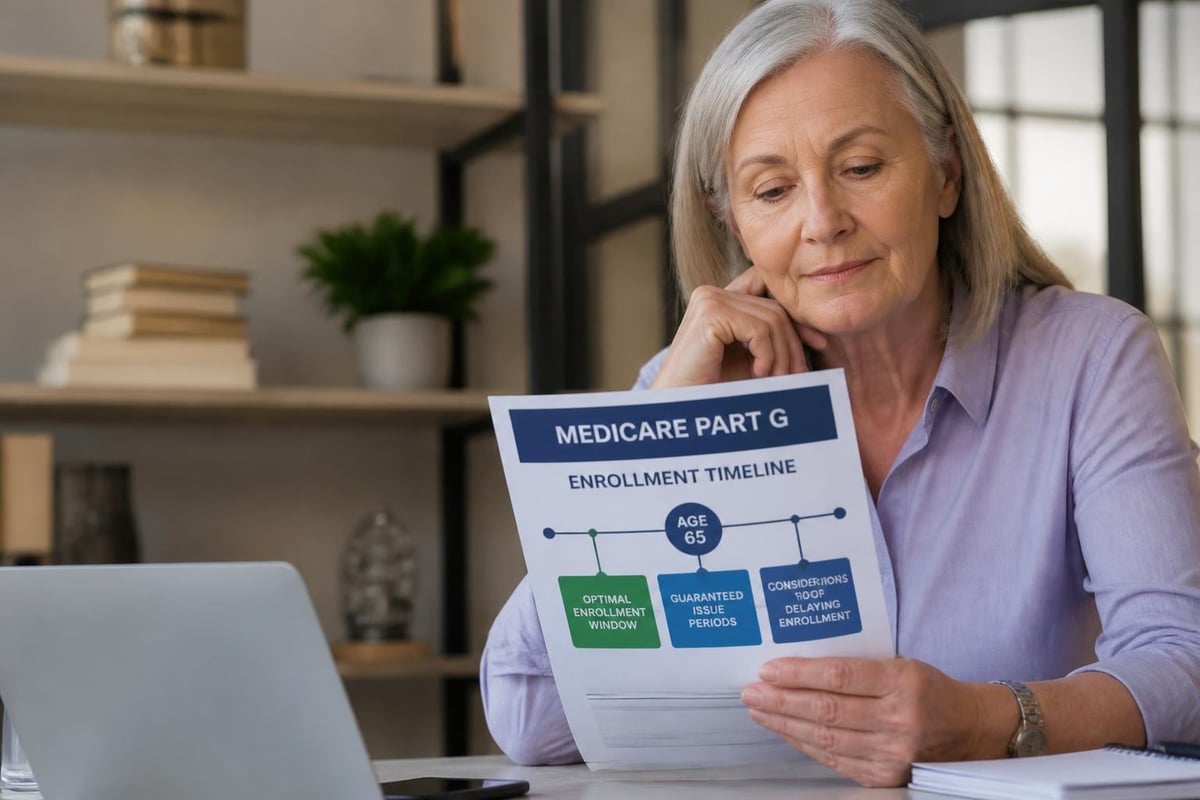
Medicare Supplement Open Enrollment Period
The best time to enroll in medicare part g coverage is during your Medicare Supplement Open Enrollment Period. This six-month window begins the first day of the month you turn 65 and are enrolled in Medicare Part B.
During this period:
- Guaranteed issue rights protect you from medical underwriting
- No health questions or exam required
- Cannot be denied coverage
- Cannot be charged higher premiums due to health conditions
According to Kiplinger’s analysis of preexisting conditions, missing this enrollment window can make coverage more expensive or even unavailable if you have significant health issues.
Special Enrollment Situations
Certain circumstances provide guaranteed issue rights outside the standard enrollment period. These situations allow you to enroll in medicare part g coverage without medical underwriting.
Guaranteed issue rights apply when:
- Your Medicare Advantage plan is leaving Medicare or stops serving your area
- You move out of your plan's service area
- Your Medigap insurance company goes bankrupt
- You're in a Medicare SELECT plan and move out of the service area
For help understanding your enrollment options in Greensboro, Kernersville, High Point, Winston Salem, or anywhere in the Triad Area, Moser Insurance Group Inc provides personalized guidance at moserinsurancegroup.com.
What Medicare Part G Coverage Doesn't Cover
While medicare part g coverage is comprehensive, it doesn't cover everything. Understanding these gaps helps you plan for additional coverage needs.
Services Not Covered by Medicare or Plan G
The following services fall outside both Original Medicare and medicare part g coverage:
- Long-term care (nursing home care)
- Dental care and dentures
- Vision care and eyeglasses
- Hearing aids and exams for fitting them
- Routine foot care
- Cosmetic surgery
- Acupuncture (except as recently added to Medicare)
- Private-duty nursing
Prescription Drug Coverage Gap
Medicare part g coverage does not include prescription drug benefits. To get medication coverage, you need to enroll in a separate Medicare Part D prescription drug plan.
Important considerations for Part D:
- Enrollment is voluntary but highly recommended
- Late enrollment penalties apply if you delay without creditable coverage
- Plans vary significantly in covered medications and costs
- You can change plans annually during the enrollment period
Many beneficiaries combine medicare part g coverage with a standalone Part D plan to create comprehensive healthcare protection. Moser Insurance Group Inc can help you coordinate these coverages effectively.
Choosing the Right Medicare Part G Coverage Plan
Selecting a specific medicare part g coverage policy requires comparing insurers based on factors beyond just the monthly premium.
Key Comparison Factors
When evaluating different Plan G policies, consider these elements:
- Monthly premium – Current rate and historical rate increases
- Financial stability – Insurer's rating from independent agencies
- Customer service – Response times and satisfaction ratings
- Claims processing – Ease and speed of claim payments
- Additional benefits – Some insurers include gym memberships or other perks
- Premium discounts – Household, payment method, or other savings
Since all Plan G policies provide identical core benefits, these additional factors become the differentiators. NerdWallet’s comprehensive overview emphasizes the importance of comparing multiple carriers.
Rate Increase History
Medicare part g coverage premiums typically increase over time. Reviewing an insurer's historical rate increases provides insight into future cost trends.
Questions to ask insurers:
- What were the premium increases for this plan over the past five years?
- How do your rate increases compare to the industry average?
- What factors drive your rate adjustments?
Insurers with consistently moderate rate increases often provide better long-term value than those with volatile pricing, even if their initial premiums are slightly higher.
Medical Underwriting and Health Considerations
Outside the guaranteed issue periods, obtaining medicare part g coverage may require medical underwriting. Understanding this process helps you prepare for enrollment.
What Insurers Evaluate
When medical underwriting applies, insurance companies assess your health history to determine eligibility and pricing. They typically review:
- Current medications and dosages
- Recent surgeries or hospitalizations
- Chronic conditions (diabetes, heart disease, COPD, etc.)
- Cancer history
- Mental health conditions
- Body mass index and lifestyle factors
Some conditions may result in coverage denial or higher premiums. Medical News Today’s analysis outlines common health conditions that affect Medigap eligibility.
Strategies for Health Challenges
If you have health conditions that might affect medicare part g coverage approval, consider these approaches:
Work with an experienced agent – Independent agents like Moser Insurance Group Inc know which insurers have more lenient underwriting for specific conditions.
Apply to multiple carriers – Different insurers evaluate health risks differently. One company might approve coverage that another denies.
Consider Plan N or other alternatives – Some plans may have less strict underwriting standards.
Time your application strategically – If you're managing a condition that's improving, waiting a few months might result in better underwriting outcomes.
State Variations in Medicare Part G Coverage
While medicare part g coverage benefits are standardized federally, state regulations create some variations in availability and rules.
States With Modified Medigap Rules
Three states – Massachusetts, Minnesota, and Wisconsin – don't follow the standard Medigap plan structure. These states have their own Medigap systems that differ from the lettered plans used elsewhere.
Additionally, some states provide extra protections:
- Guaranteed issue rights for younger Medicare beneficiaries
- Birthday rules allowing annual plan changes without underwriting
- Extended open enrollment periods
State-Specific Consumer Protections
Many states offer additional protections beyond federal requirements. These may include:
- Rate review processes that scrutinize premium increases
- Loss ratio requirements ensuring benefits paid meet minimum thresholds
- Extended trial periods for new policies
- Prohibitions on certain underwriting practices
Residents of Greensboro, Kernersville, High Point, Winston Salem, and throughout North Carolina benefit from state insurance department oversight that ensures fair practices.
Switching Medicare Supplement Plans
After enrolling in medicare part g coverage, you retain the right to switch to a different plan, though the process differs from initial enrollment.
When Switching Makes Sense
Consider changing your medicare part g coverage to another plan when:
Your health has improved significantly – You might qualify for better rates through a new application
Premium increases exceed industry averages – Shopping for competitive rates can reduce costs
You're moving to a different area – Geographic pricing differences may create savings opportunities
You want different coverage levels – Switching to Plan N might reduce premiums if you're willing to accept copays
The Switching Process
Changing from medicare part g coverage to another Medigap plan requires applying to a new insurer. Outside guaranteed issue periods, this application will include medical underwriting in most states.
Steps for switching:
- Research new plan options and get quotes
- Apply to the new insurer
- Wait for approval before canceling current coverage
- Ensure new coverage is in effect before terminating old policy
- Cancel previous medicare part g coverage only after new policy starts
Never cancel existing coverage before securing new approval. A gap in coverage could leave you financially vulnerable to healthcare costs.
Medicare Part G Coverage for Specific Health Situations
Understanding how medicare part g coverage works for common health scenarios helps you evaluate its value for your specific circumstances.
Chronic Condition Management
For beneficiaries managing chronic conditions like diabetes, heart disease, or arthritis, medicare part g coverage provides predictable costs. The plan's comprehensive coverage means routine specialist visits, testing, and monitoring incur minimal out-of-pocket expenses after meeting the Part B deductible.
Cost predictability for chronic conditions:
- No copays for specialist visits after Part B deductible
- Full coverage of Part B coinsurance for tests and procedures
- No prior authorization requirements (since you're using Original Medicare providers)
- Freedom to see any Medicare-accepting provider
Cancer Treatment Coverage
Medicare part g coverage offers substantial financial protection for cancer patients. Chemotherapy, radiation, surgical procedures, and follow-up care all fall under Medicare-approved services that Plan G helps cover.
The plan covers Part B coinsurance for outpatient treatments and the Part A deductible plus coinsurance for hospital stays related to cancer treatment. This comprehensive coverage eliminates most out-of-pocket costs beyond premiums and the initial Part B deductible.
Emergency and Hospital Care
For emergency situations and hospitalizations, medicare part g coverage provides maximum financial protection. The plan covers the Part A hospital deductible ($1,676 in 2026), subsequent coinsurance, and even provides limited emergency coverage for foreign travel.
This coverage proves especially valuable for beneficiaries who travel frequently or have conditions that might require sudden hospitalization.
Provider Networks and Medicare Part G Coverage
One significant advantage of medicare part g coverage is the absence of network restrictions. Since the plan works with Original Medicare, you have extensive provider access.
Any Medicare Provider Accepted
With medicare part g coverage, you can visit any doctor, specialist, or hospital that accepts Medicare assignment. This includes approximately 95% of healthcare providers nationwide.
Provider flexibility benefits:
- No referrals needed for specialists
- No in-network vs. out-of-network considerations
- Freedom to see providers anywhere in the United States
- Ability to switch doctors without changing insurance
- Access to top-rated hospitals and medical centers
This contrasts sharply with Medicare Advantage plans, which typically require you to use network providers. For residents across Greensboro, Kernersville, High Point, Winston Salem, and the entire Triad Area, this flexibility means accessing care throughout North Carolina and beyond.
Traveling With Medicare Part G Coverage
Medicare part g coverage travels with you throughout the United States. Your benefits remain consistent whether you're home or visiting another state.
Additionally, Plan G includes foreign travel emergency coverage. The plan pays 80% of emergency care costs during the first 60 days of a trip, after a $250 deductible, up to a $50,000 lifetime limit. This benefit provides valuable protection for international travelers.
Comparing Medicare Part G Coverage to Medicare Advantage
Many beneficiaries compare medicare part g coverage to Medicare Advantage plans when choosing coverage beyond Original Medicare. These options represent fundamentally different approaches to Medicare coverage.
Coverage Structure Differences
| Aspect | Medicare Part G | Medicare Advantage |
|---|---|---|
| Provider networks | Any Medicare provider | Typically network-restricted |
| Out-of-pocket maximum | None needed (minimal costs) | Annual maximum ($8,850 in 2026) |
| Prescription coverage | Separate Part D needed | Often included |
| Monthly premiums | Higher ($140-$250+) | Often $0-$50 |
| Predictability | Very predictable | Less predictable |
| Extra benefits | Few | Dental, vision, hearing often included |
When Medicare Part G Makes More Sense
Medicare part g coverage typically works better for beneficiaries who:
- Want maximum flexibility in choosing providers
- Travel frequently or spend time in multiple locations
- Have chronic conditions requiring regular specialist care
- Prefer predictable costs over lower premiums
- Can afford higher monthly premiums for comprehensive coverage
- Want to keep their current doctors regardless of network changes
For individuals who value having complete control over their healthcare choices and minimal out-of-pocket costs at the point of service, medicare part g coverage often proves worth the higher premiums. Moser Insurance Group Inc helps clients in the Triad Area evaluate whether Medicare Supplement plans or Medicare Advantage options better suit their individual circumstances.
Future Considerations for Medicare Part G Coverage
Understanding potential future changes to medicare part g coverage helps you make decisions that remain sound over time.
Legislative and Regulatory Changes
Medicare supplement plans face occasional legislative adjustments. While Plan G benefits are currently standardized, Congress could modify Medigap rules, as it did when eliminating first-dollar coverage for new enrollees after 2020.
Potential future changes might include:
- New standardized plan options
- Modifications to existing plan benefits
- Changes to enrollment rules or underwriting requirements
- Premium regulation adjustments
Existing policyholders typically maintain their current benefits even when rules change, making timely enrollment important.
Premium Trends and Projections
Medicare part g coverage premiums have historically increased 3-5% annually on average, though individual insurers vary. These increases reflect rising healthcare costs, beneficiary aging, and insurer claims experience.
Planning for future premium increases helps ensure long-term affordability. Budget for annual increases when evaluating whether medicare part g coverage fits your financial situation long-term. Some beneficiaries find value in choosing slightly higher initial premiums from insurers with historically moderate rate increase patterns.
Medicare Part G coverage provides comprehensive protection against the gaps in Original Medicare, offering predictable costs and extensive provider flexibility for beneficiaries throughout their retirement years. Whether you're approaching 65, already enrolled in Medicare, or helping a family member navigate coverage options, understanding the benefits, costs, and enrollment considerations of Plan G helps you make confident insurance decisions. Moser Insurance Group Inc specializes in helping individuals and families throughout Greensboro, Kernersville, High Point, Winston Salem, and the Triad Area understand their Medicare options with clear guidance and personalized support. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your Medicare supplement needs and find the coverage that fits your healthcare and financial goals.
Recent Comments