

Understanding the medicare open enrollment period is essential for every Medicare beneficiary who wants to optimize their healthcare coverage. Each fall, millions of Americans have a limited window to review their current plans, explore new options, and make changes that will affect their healthcare for the entire following year. Whether you're already enrolled in Medicare or approaching eligibility, knowing how this annual period works can save you money and ensure you have the coverage you need. This guide explains everything you need to know about making informed decisions during this critical time frame, with specific attention to the 2026 enrollment season.
What Is the Medicare Open Enrollment Period
The medicare open enrollment period, officially known as the Annual Enrollment Period (AEP), runs from October 15 through December 7 every year. During these seven weeks, Medicare beneficiaries can make significant changes to their coverage without needing a qualifying life event or special circumstance.
Coverage Changes You Can Make
During this window, you have broad flexibility to adjust your Medicare coverage:
- Switch from Original Medicare (Parts A and B) to a Medicare Advantage plan
- Move from a Medicare Advantage plan back to Original Medicare
- Switch from one Medicare Advantage plan to another
- Join, drop, or switch Medicare Part D prescription drug plans
- Add or drop a Medicare Supplement plan when moving between Original Medicare and Medicare Advantage
Any changes you make during the enrollment period take effect on January 1, 2027. The official Medicare enrollment guidance provides comprehensive details about the specific plan changes allowed during this timeframe.
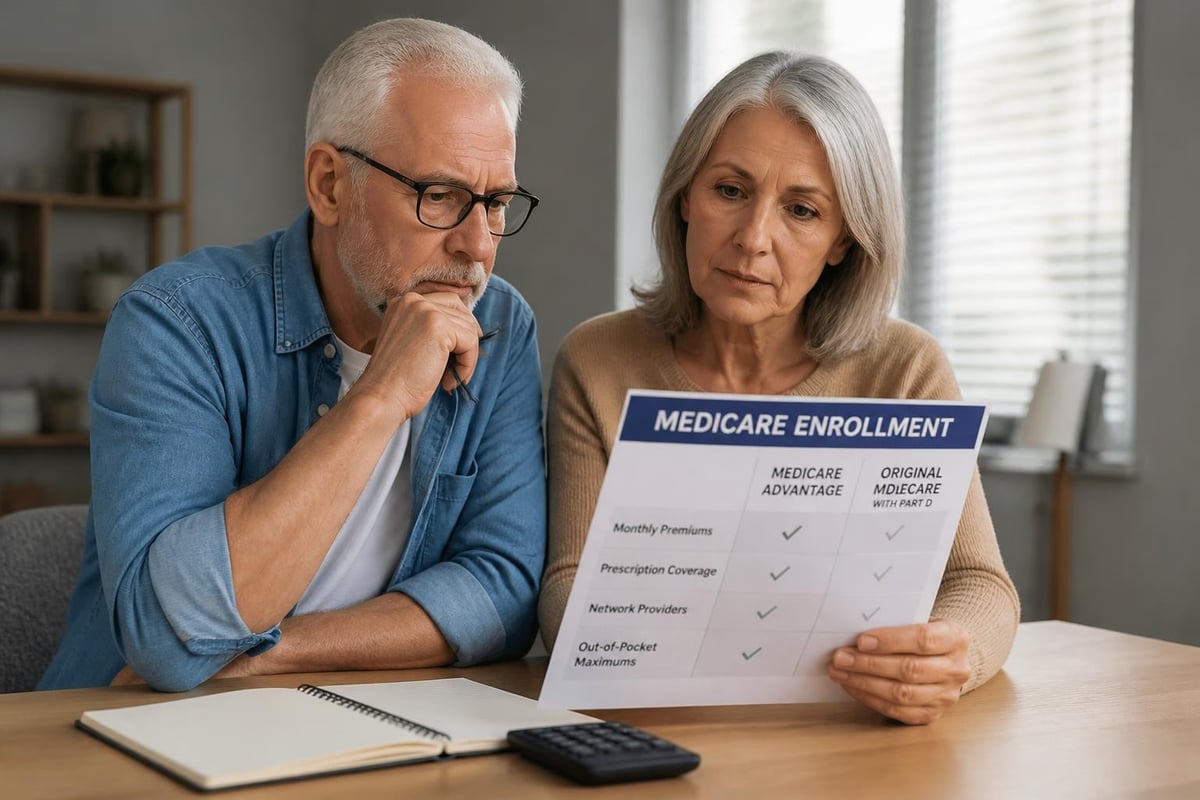
Why the Medicare Open Enrollment Period Matters
Healthcare needs evolve. The medications you took last year might change. Your preferred doctors could join or leave certain networks. Plan benefits and costs are adjusted annually. That's why the medicare open enrollment period exists as a safeguard against being locked into outdated coverage.
Plans change their benefits every year. Insurance companies regularly adjust:
- Monthly premiums
- Deductibles and copayments
- Prescription drug formularies
- Provider networks
- Coverage rules and restrictions
Your current plan might have been perfect in 2026, but those same benefits aren't guaranteed for 2027. Reviewing your coverage each fall ensures you're not caught off guard by unexpected changes.
Financial Implications
Staying in a plan without reviewing alternatives can cost you hundreds or even thousands of dollars annually. A plan that covered your medications with low copays this year might move those same drugs to a higher tier next year, dramatically increasing your costs.
Similarly, provider networks shift. Your longtime physician could be out-of-network come January if you don't verify their participation during the enrollment period.
Medicare Advantage vs. Original Medicare Decisions
One of the most significant choices during the medicare open enrollment period is deciding between Medicare Advantage (Part C) and Original Medicare with or without a Part D plan.
Medicare Advantage Plan Features
| Feature | Typical Benefits | Considerations |
|---|---|---|
| All-in-one coverage | Medical and often prescription coverage combined | Must use network providers except emergencies |
| Extra benefits | Vision, dental, hearing, fitness | Benefits vary widely by plan and location |
| Out-of-pocket maximum | Annual cap on your costs | Can still be several thousand dollars |
| Premiums | Often $0 monthly (plus Part B premium) | May have higher copays per service |
Medicare Advantage plans bundle hospital, medical, and often prescription coverage into one plan offered by private insurance companies. Many plans in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, offer additional perks like gym memberships and over-the-counter allowances.
Original Medicare Characteristics
Original Medicare provides coverage through the federal government with Parts A (hospital) and B (medical). It offers nationwide provider acceptance and predictable coverage rules, but it leaves gaps.
Coverage gaps in Original Medicare:
- No out-of-pocket maximum
- 20% coinsurance on Part B services with no cap
- Hospital deductibles that reset per benefit period
- No prescription drug coverage (requires separate Part D plan)
Many beneficiaries pair Original Medicare with a Medicare Supplement plan to cover deductibles and coinsurance. During open enrollment, you can add or switch Part D prescription coverage, though Medigap enrollment has different rules outside your initial enrollment window.
Evaluating Your Prescription Drug Coverage
Part D prescription coverage deserves special attention during the medicare open enrollment period. Drug costs represent a substantial portion of healthcare spending for most Medicare beneficiaries, and formularies change significantly year to year.
Steps to Review Your Drug Coverage
- List all your current medications including dosages and quantities
- Check your plan's 2027 formulary to see if your drugs are still covered
- Note any tier changes that would increase your copays
- Verify your preferred pharmacy remains in-network
- Calculate total annual costs including premiums, deductibles, and copays
The Medicare Plan Finder tool at Medicare.gov allows you to enter your specific medications and compare actual costs across all available plans in your area. This personalized comparison reveals which plans offer the best value for your unique prescription needs.
Understanding Formulary Tiers
Most Part D plans organize medications into five or six tiers, with lower tiers having lower copays:
- Tier 1: Preferred generic drugs (lowest cost)
- Tier 2: Generic drugs
- Tier 3: Preferred brand-name drugs
- Tier 4: Non-preferred brand-name drugs
- Tier 5: Specialty drugs (highest cost)
A medication that was Tier 2 this year might move to Tier 4 next year, tripling your copay. Checking these details during the enrollment period prevents costly surprises in January.
How to Compare Medicare Plans Effectively
With dozens of plan options available in most areas, comparison shopping can feel overwhelming. A systematic approach helps you identify the best coverage for your circumstances.
Key Comparison Factors
| Factor | What to Examine | Why It Matters |
|---|---|---|
| Total annual cost | Premiums + deductibles + expected copays | Lowest premium doesn't mean lowest total cost |
| Provider network | Your doctors, specialists, hospitals | Out-of-network care costs significantly more |
| Prescription coverage | Formulary, tiers, pharmacy network | Drug costs often exceed medical costs |
| Extra benefits | Dental, vision, hearing coverage | Can save hundreds on routine care |
| Quality ratings | Star ratings from CMS | Higher-rated plans typically provide better service |
The CMS Star Ratings system evaluates plans on quality of care, member satisfaction, and customer service. Plans with 4 or 5 stars generally deliver superior performance.
For residents in the Triad Area, Greensboro, Kernersville, High Point, and Winston Salem, local provider availability varies significantly between plans. Confirming your preferred doctors participate in a plan's network before enrolling prevents disruption to established care relationships.
Getting Personalized Assistance
Free, unbiased help is available through your State Health Insurance Assistance Program (SHIP), which provides local counseling during the medicare open enrollment period. These trained volunteers can help you understand plan differences and compare options based on your specific healthcare needs.
You can also work with an independent insurance agent who represents multiple carriers. This approach gives you access to plan expertise without the pressure of captive agents who sell only one company's products. At Moser Insurance Group Inc, we help clients throughout the enrollment process by explaining plan differences clearly and answering questions without sales pressure. Contact us at 336-862-1763 or moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com.
Special Enrollment Periods Beyond Open Enrollment
While the medicare open enrollment period offers the broadest opportunity to change coverage, certain life events trigger Special Enrollment Periods (SEPs) that allow changes outside the annual window.
Common qualifying events include:
- Moving to a new address outside your plan's service area
- Losing other creditable coverage (employer insurance, Medicaid)
- Moving into or out of a skilled nursing facility
- Qualifying for both Medicare and Medicaid
- Losing Extra Help with prescription costs
- Plan contract termination by Medicare
Special Enrollment Periods typically last for two to three months surrounding the qualifying event. The detailed enrollment regulations outline specific timeframes and documentation requirements for each circumstance.
Medicare Advantage Open Enrollment Period
There's also a separate Medicare Advantage Open Enrollment Period from January 1 through March 31 each year. During this window, people already enrolled in Medicare Advantage can:
- Switch to a different Medicare Advantage plan
- Drop their Medicare Advantage plan and return to Original Medicare
- Join a Part D plan if returning to Original Medicare
This period provides a safety net if you discover your new coverage isn't working as expected after the medicare open enrollment period ends.
Financial Assistance Programs During Enrollment
Many Medicare beneficiaries qualify for programs that reduce their healthcare costs but aren't aware these benefits exist. The medicare open enrollment period is an excellent time to explore whether you're eligible for assistance.
Medicare Savings Programs
If your income falls below certain thresholds, your state may pay some or all of your Medicare premiums, deductibles, and coinsurance through Medicare Savings Programs.
Four programs offer different levels of help:
- Qualified Medicare Beneficiary (QMB): Pays Part A and B premiums, deductibles, and coinsurance
- Specified Low-Income Medicare Beneficiary (SLMB): Pays Part B premiums only
- Qualifying Individual (QI): Pays Part B premiums with limited funding
- Qualified Disabled & Working Individuals (QDWI): Pays Part A premiums for working disabled individuals
Eligibility varies by state and income level. In 2026, individuals earning less than approximately $1,549 monthly may qualify for QMB benefits (exact amounts vary by state and are updated annually).
Extra Help with Prescription Costs
The Extra Help program (also called the Low-Income Subsidy) assists with Part D prescription drug costs. Benefits include reduced or eliminated premiums, no coverage gap, and lower copays.
Income and asset limits apply, but millions of beneficiaries qualify without realizing it. Applications can be submitted anytime, not just during the medicare open enrollment period.
Common Mistakes to Avoid During Enrollment
Even experienced Medicare beneficiaries make errors during the annual enrollment period that lead to coverage gaps or unexpected costs.
Costly Enrollment Errors
Assuming your plan stays the same. Failing to review your Annual Notice of Change (ANOC), which arrives in September, means missing important updates about your plan's 2027 benefits, costs, and coverage rules.
Focusing only on premium costs. A plan with a $0 monthly premium might cost more overall if it has high deductibles, expensive copays, or doesn't cover your medications affordably.
Not checking provider networks annually. Doctor and hospital participation changes yearly. Your primary care physician or specialist might leave the network, forcing you to switch providers or pay out-of-network rates.
Ignoring the coverage gap. Understanding how the Part D donut hole works and whether your plan offers gap coverage affects your medication costs once you reach the initial coverage limit.
Missing the deadline. Procrastinating until early December risks missing the December 7 deadline if you need time to research options or gather information.
Proactive Enrollment Strategies
Set aside time in October to review your options rather than waiting until November or December. Start by gathering your current plan documents, medication list, and provider information.
Compare at least three plans even if you're satisfied with your current coverage. Market competition means new plans with better benefits may have entered your area.
Document your decision-making process. Note which plans you compared, what factors were most important, and why you chose your final selection. This record helps next year's review process.
Resources for Medicare Open Enrollment Period Support
Navigating the medicare open enrollment period doesn't have to be a solo endeavor. Multiple resources exist to help beneficiaries make informed decisions.
Official Medicare Resources
Medicare.gov provides comprehensive tools including:
- Medicare Plan Finder for personalized plan comparisons
- Drug formulary searches
- Provider directory lookups
- Cost calculators
- Educational materials about coverage options
The official site also offers chat support and a helpline at 1-800-MEDICARE (1-800-633-4227) with customer service representatives available 24/7.
Independent Counseling and Education
Medicare Rights Center resources offer unbiased information about enrollment choices and beneficiary protections. As a nonprofit organization, they provide education without selling insurance products.
Local SHIP counselors offer free, in-person assistance with plan comparisons and enrollment decisions. These trained volunteers understand regional plan availability and can help you navigate the medicare open enrollment period with personalized guidance.
Professional Insurance Assistance
Working with an independent insurance professional provides access to expert knowledge about plan details, coverage nuances, and local provider networks. Unlike captive agents tied to a single company, independent agents can compare offerings from multiple carriers to find the best fit.
The Kaiser Family Foundation’s detailed Q&A guide answers common questions about the enrollment period with evidence-based information, helping beneficiaries understand their options.
Making Your Final Decision
After researching plan options and comparing coverage, it's time to enroll in your selected plan before the December 7 deadline.
Enrollment Methods
You can complete your enrollment through several channels:
- Online through Medicare.gov or the insurance company's website
- By phone by calling the plan directly or 1-800-MEDICARE
- In person with a licensed insurance agent
- By mail using the plan's enrollment form
Most people find online enrollment fastest and most convenient, with confirmation typically provided immediately. Phone enrollment offers the benefit of asking questions during the process.
Confirmation and Verification
After enrolling, you should receive confirmation from your new plan within 10 business days. This confirmation includes:
- Your plan name and contract number
- Coverage effective date (January 1, 2027)
- Your member ID number
- Information about accessing plan benefits
If you're switching plans, you'll also receive a disenrollment notice from your old plan. Keep all documentation for your records.
Important: If you don't receive confirmation within two weeks, contact the plan immediately to verify your enrollment was processed. Missing enrollment confirmation could mean you won't have coverage on January 1.
Plan Changes Throughout the Year
Understanding when you can and cannot make changes helps you plan for the medicare open enrollment period more strategically.
Limited Mid-Year Options
Outside enrollment periods, you generally cannot switch plans unless you qualify for a Special Enrollment Period. This restriction underscores why the annual enrollment window is so critical.
The exception is the Medicare Advantage Open Enrollment Period (January 1 – March 31), which allows one plan change for those already in Medicare Advantage plans.
Preparing for Next Year
After completing your 2027 enrollment, start a file for next year's medicare open enrollment period. Throughout 2027, note:
- Changes in your medication needs
- Any issues with provider network access
- Unexpected out-of-pocket costs
- Services you wish were covered
- Questions about plan rules or benefits
This running list makes next October's review process much more focused and efficient. You'll remember what worked well and what needs improvement when comparing 2028 coverage options.
The medicare open enrollment period represents your annual opportunity to ensure your healthcare coverage aligns with your needs and budget for the coming year. Taking time to review plans, compare options, and understand changes can save you money while improving your access to quality care. Moser Insurance Group Inc specializes in helping individuals and families throughout the Triad Area-including Greensboro, Kernersville, High Point, and Winston Salem-navigate Medicare decisions with clear explanations and personalized support, so you can choose coverage with confidence. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to get started with your enrollment review today.
Recent Comments