
Searching for "medicare insurance near me" often signals an important transition in your healthcare journey. Whether you're approaching 65, recently retired, or helping a family member navigate Medicare, finding local expertise makes a significant difference in understanding your coverage options. The Medicare landscape includes multiple plan types, enrollment periods, and cost structures that benefit from personalized guidance. In the Triad Area of North Carolina-including Greensboro, Winston-Salem, High Point, and Kernersville-local resources can help you make informed decisions about your healthcare coverage.
Understanding Medicare Insurance Options in Your Area
Medicare provides health insurance coverage for Americans aged 65 and older, as well as certain younger individuals with disabilities. The program consists of several parts that work together to provide comprehensive healthcare coverage.
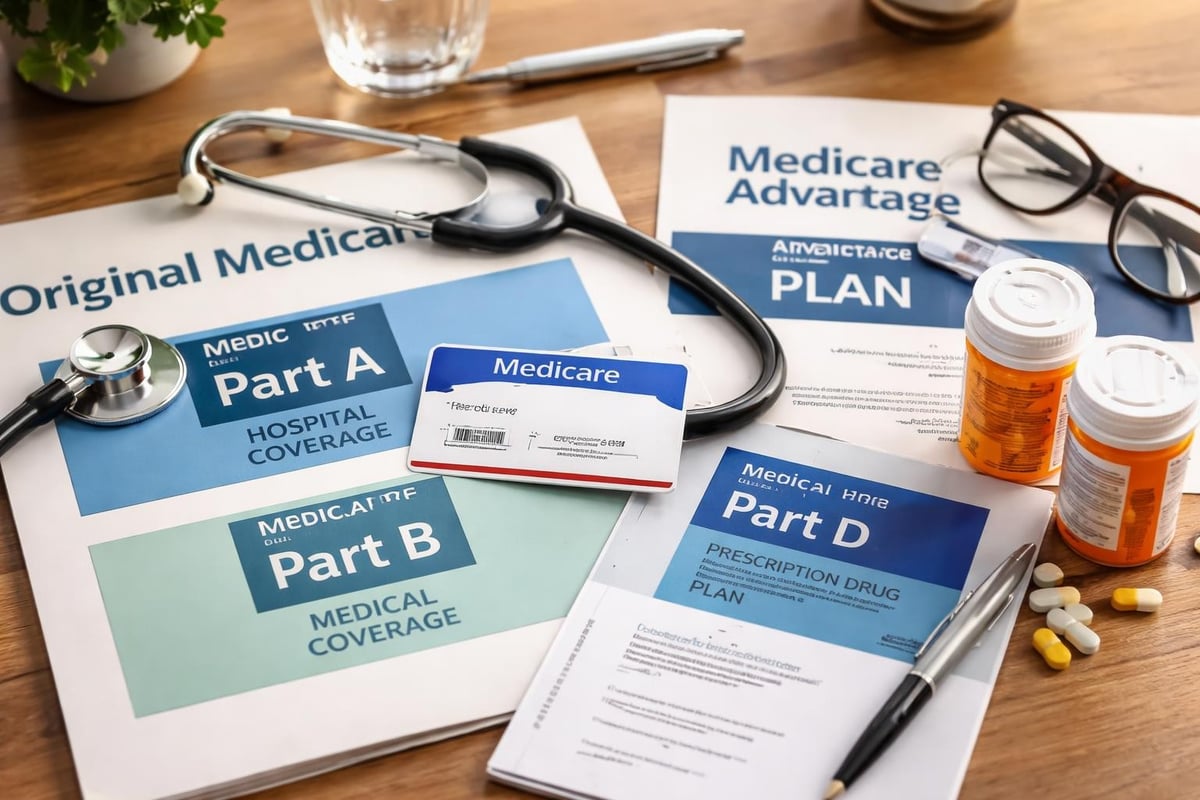
Original Medicare includes Part A (hospital insurance) and Part B (medical insurance). Part A covers inpatient hospital stays, skilled nursing facility care, hospice care, and some home health services. Part B covers doctor visits, outpatient care, preventive services, and durable medical equipment.
The Four Parts of Medicare
Understanding the basic structure helps you search effectively for medicare insurance near me:
- Part A (Hospital Insurance): Covers inpatient hospital care, skilled nursing facilities, hospice, and limited home health services
- Part B (Medical Insurance): Covers doctor visits, outpatient services, preventive care, and medical equipment
- Part C (Medicare Advantage): Private insurance plans that combine Parts A and B, often including prescription drug coverage
- Part D (Prescription Drug Coverage): Standalone plans that cover prescription medications when paired with Original Medicare
The comprehensive A-Z index on Medicare.gov provides detailed information about each component, helping you understand what coverage you need based on your health situation.
Evaluating Medicare Supplement Plans Versus Medicare Advantage
One of the most important decisions when researching medicare insurance near me involves choosing between Medicare Supplement plans (Medigap) and Medicare Advantage plans. Each approach offers distinct advantages depending on your healthcare needs, budget, and preferences.
| Feature | Medicare Supplement | Medicare Advantage |
|---|---|---|
| Coverage Structure | Works with Original Medicare | Replaces Original Medicare |
| Provider Network | Any doctor accepting Medicare | Usually network-based (HMO, PPO) |
| Out-of-Pocket Costs | Predictable, lower copays | Variable, may have higher maximums |
| Additional Benefits | None beyond basic coverage | Often includes dental, vision, hearing |
| Prescription Coverage | Requires separate Part D | Often built-in |
| Travel Coverage | Nationwide acceptance | May require prior authorization |
Medicare Supplement plans help cover the gaps in Original Medicare, such as deductibles, copayments, and coinsurance. These standardized plans (labeled A through N) offer predictable costs and the freedom to see any healthcare provider who accepts Medicare nationwide.
Medicare Advantage plans provide an alternative way to receive Medicare benefits through private insurance companies. These plans must cover everything Original Medicare covers but often include additional benefits like dental, vision, and prescription drug coverage. Many residents in Greensboro, Winston-Salem, High Point, and Kernersville choose Medicare Advantage for the convenience of bundled coverage.
Which Plan Type Fits Your Situation
Consider your healthcare usage patterns and financial priorities. If you travel frequently between North Carolina and other states, value provider flexibility, or prefer predictable healthcare costs, Medicare Supplement plans typically offer greater peace of mind.
Conversely, if you stay primarily in the Triad Area, want additional benefits beyond basic Medicare, or prefer lower monthly premiums with the understanding of network restrictions, Medicare Advantage might suit your needs better. The Kaiser Family Foundation’s Medicare overview provides detailed analysis of how different plan types compare in real-world scenarios.
Finding Local Medicare Resources in the Triad Area
When you search for medicare insurance near me, you're looking for more than just information-you need accessible, local expertise. The Triad Area of North Carolina offers numerous resources for Medicare beneficiaries in Greensboro, Winston-Salem, High Point, and Kernersville.
Local Insurance Agencies and Brokers
Independent insurance agencies provide valuable assistance because they work with multiple insurance carriers. This means they can compare plans from different companies to find options that match your specific healthcare needs and budget.
Working with a local agent offers several advantages:
- Face-to-face consultations to discuss your unique health situation
- Personalized plan comparisons based on your doctors, medications, and health conditions
- Ongoing support for claims questions, plan changes, and annual enrollment
- No additional cost since Medicare plan pricing remains the same regardless of whether you enroll directly or through an agent
Contact Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com to schedule a consultation. You can also visit moserinsurancegroup.com to learn more about available coverage options in the Triad Area.
State Health Insurance Assistance Program (SHIP)
North Carolina offers free, unbiased Medicare counseling through its SHIIP (Seniors' Health Insurance Information Program). Trained volunteers help you understand medicare insurance near me options without selling specific plans.
Timing Your Medicare Enrollment Correctly
Understanding when to enroll prevents costly penalties and coverage gaps. Medicare has specific enrollment windows that determine when you can sign up for coverage or make changes to existing plans.
Initial Enrollment Period (IEP)
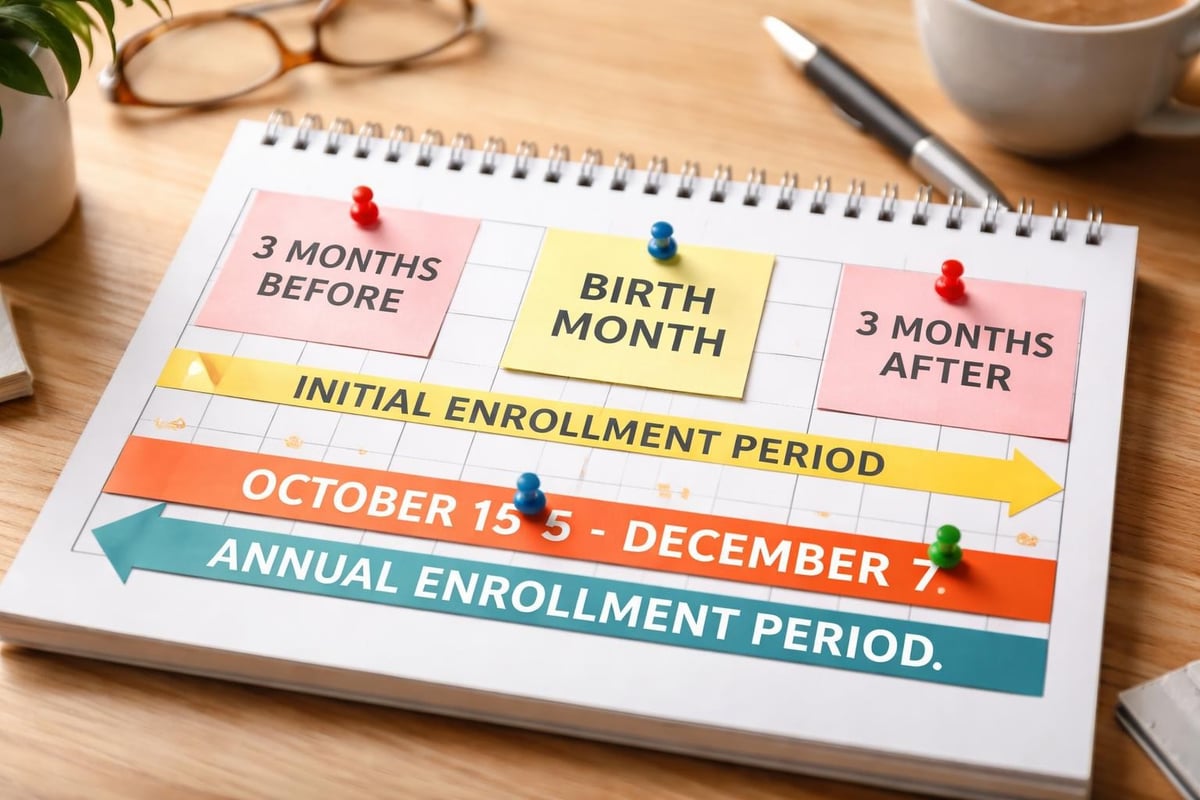
Your Initial Enrollment Period spans seven months:
- Three months before your 65th birthday month
- Your birthday month
- Three months after your birthday month
Critical timing consideration: If you enroll during the three months before your birthday month, coverage typically begins on the first day of your birthday month. Waiting until your birthday month or after may delay your coverage start date.
Special Enrollment Periods
Certain life events trigger Special Enrollment Periods that allow you to enroll outside your Initial Enrollment Period without penalties:
- Losing employer health coverage (yours or a spouse's)
- Moving outside your plan's service area
- Qualifying for Extra Help with prescription drug costs
- Moving into or out of a nursing home
- Gaining or losing Medicaid eligibility
Document these qualifying events carefully, as you typically have 63 days to enroll after the event occurs.
Annual Enrollment Period (AEP)
Every year from October 15 through December 7, all Medicare beneficiaries can review and change their coverage. During this window, you can:
- Switch from Original Medicare to Medicare Advantage (or vice versa)
- Change from one Medicare Advantage plan to another
- Add, drop, or change prescription drug coverage
- Switch between Medicare Supplement plans in some cases
Changes made during Annual Enrollment Period take effect January 1 of the following year. This represents your primary opportunity to ensure your medicare insurance near me still meets your evolving healthcare needs.
Comparing Prescription Drug Coverage Options
Prescription drug costs represent a significant healthcare expense for many Medicare beneficiaries. Understanding your medication coverage options helps you budget accurately and access necessary medications.
Standalone Part D Plans
If you maintain Original Medicare with or without a Medicare Supplement plan, you'll need a standalone Part D prescription drug plan. These plans vary significantly in several areas:
| Plan Feature | What to Compare |
|---|---|
| Monthly Premium | Ranges from $0 to $100+ per month |
| Annual Deductible | $0 to $590 in 2026 |
| Formulary | Which medications are covered |
| Pharmacy Network | Which pharmacies you can use |
| Coverage Gap | How the plan handles the "donut hole" |
| Prior Authorization | Requirements for certain medications |
Enter your specific medications into the Medicare Plan Finder to see which plans in Greensboro, Winston-Salem, High Point, and Kernersville offer the best coverage for your prescriptions.
Prescription Coverage in Medicare Advantage
Most Medicare Advantage plans include prescription drug coverage (MA-PD plans). This integration simplifies your coverage but requires you to change your entire plan if you're unhappy with prescription benefits.
Review your top Medicare Advantage plans annually to ensure they still cover your medications at preferred pharmacies. Formularies change yearly, and a medication covered this year might move to a different tier or require prior authorization next year.
Evaluating Plan Costs Beyond Monthly Premiums
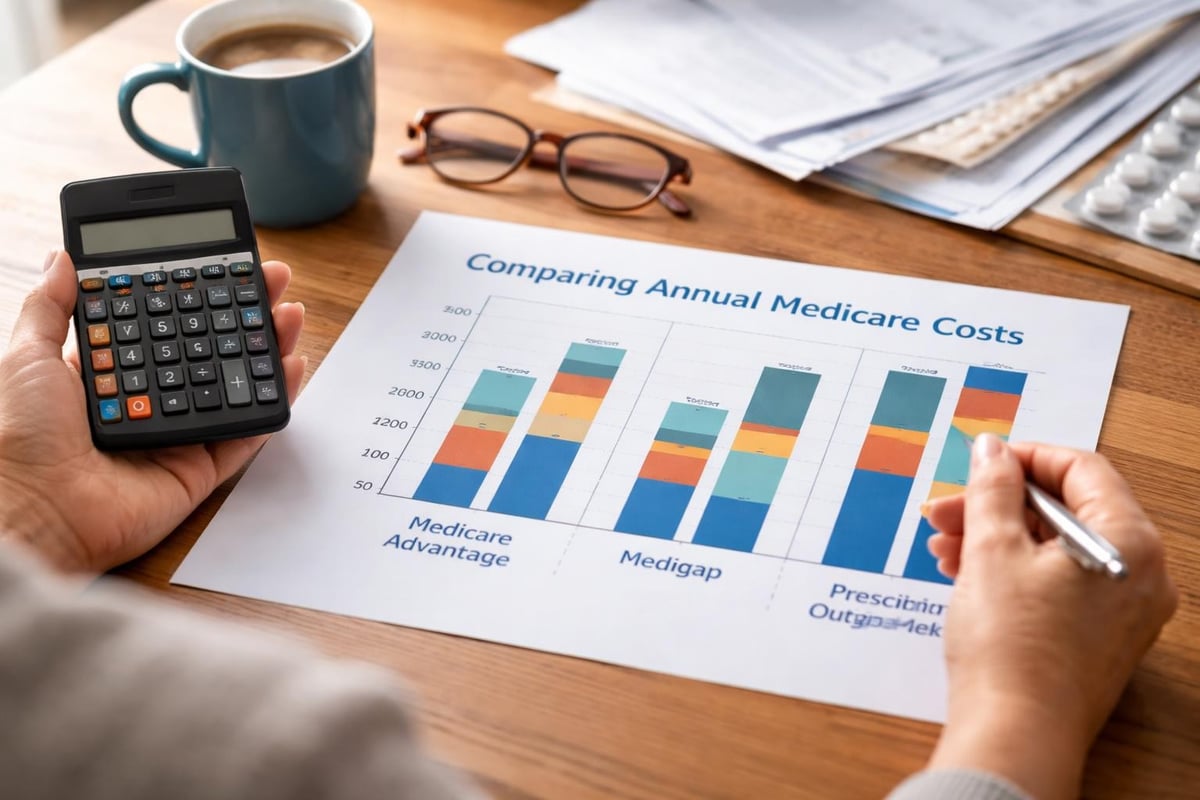
When comparing medicare insurance near me, looking solely at monthly premiums provides an incomplete financial picture. Total healthcare costs include multiple components that affect your annual spending.
Understanding True Out-of-Pocket Costs
Deductibles: The amount you pay before coverage begins. Original Medicare Part A has a $1,676 deductible per benefit period in 2026, while Part B has a $257 annual deductible.
Copayments: Fixed amounts you pay for services (such as $30 for a specialist visit).
Coinsurance: Percentage of costs you pay (such as 20% of the Medicare-approved amount for Part B services).
Maximum Out-of-Pocket (MOOP): Medicare Advantage plans must include an annual limit on your out-of-pocket costs, typically ranging from $3,000 to $8,000 depending on the plan.
Creating a Healthcare Budget
Calculate your expected annual costs by considering:
- Monthly premiums for all coverage (Part B, Part D, Supplement or Advantage plan)
- Expected copays based on your typical healthcare usage
- Prescription medication costs throughout the year
- Potential deductibles if you require hospital care
The National Academy of Social Insurance’s Medicare guide explains how these cost structures work together and affect different income levels.
Protecting Your Coverage Rights
Medicare beneficiaries have specific rights and protections that ensure fair treatment and access to appeals processes when coverage disputes arise.
Guaranteed Issue Rights for Medicare Supplements
You have a guaranteed right to buy any Medicare Supplement plan sold in your state during your Medigap Open Enrollment Period-a six-month window that begins when you're both 65 or older and enrolled in Medicare Part B.
During this period, insurance companies cannot:
- Deny you coverage based on health conditions
- Charge you more due to health problems
- Make you wait for coverage to start due to pre-existing conditions
Outside this window, you may face medical underwriting (health questions) when applying for Medicare Supplement coverage. Some states offer additional guaranteed issue situations, so understanding your rights prevents costly mistakes.
Appeals and Grievances
If Medicare or your Medicare plan denies coverage for a service you believe should be covered, you have the right to appeal. The appeals process includes five levels:
- Redetermination by your plan or Medicare contractor
- Reconsideration by an independent reviewer
- Hearing before an Administrative Law Judge
- Review by the Medicare Appeals Council
- Judicial review in federal court
Most coverage disputes resolve at the first or second level. Document all communications, keep copies of denial letters, and understand your deadlines-typically 60 days to file at each level.
Coordinating Medicare with Other Insurance
Many people searching for medicare insurance near me have additional coverage that works alongside Medicare. Understanding coordination of benefits prevents confusion and maximizes your coverage.
Employer or Union Coverage
If you or your spouse still work and have employer health insurance, you face an important decision: when to enroll in Medicare Part B.
For employers with 20+ employees: Employer coverage typically pays primary, and Medicare pays secondary. You can delay Part B enrollment without penalties.
For employers with fewer than 20 employees: Medicare pays primary, so you should enroll in Part B when eligible to avoid gaps.
The Kiplinger guide to Medicare provides detailed scenarios for coordinating employer coverage with Medicare enrollment.
Veterans Benefits and TRICARE
VA benefits and TRICARE for Life coordinate with Medicare in specific ways:
- VA benefits are not health insurance and don't satisfy Medicare requirements
- TRICARE for Life requires you to have both Medicare Part A and Part B
- Some veterans qualify for both VA care and Medicare, using each for different services
Discuss your VA benefits with your healthcare providers to understand which services you can access through the VA and which require Medicare coverage. This coordination affects your decisions when searching for medicare insurance near me.
Avoiding Common Medicare Enrollment Mistakes
Understanding frequent pitfalls helps you navigate the Medicare system more successfully and avoid costly errors that affect your coverage or finances.
Late Enrollment Penalties
Missing enrollment deadlines can result in permanent premium penalties. The Part B late enrollment penalty equals 10% of the standard premium for each 12-month period you were eligible but didn't enroll. This penalty continues for as long as you have Part B.
The Part D late enrollment penalty calculates as 1% of the national base beneficiary premium times the number of months you went without creditable drug coverage. In 2026, this penalty adds approximately $0.35 per month for each month of delayed enrollment.
Not Reviewing Coverage Annually
Your healthcare needs change, and so do Medicare plans. Insurance companies can modify:
- Networks of doctors and hospitals
- Prescription drug formularies
- Copayments and coinsurance amounts
- Additional benefits like dental or vision coverage
Set a reminder each October to review your coverage during the Annual Enrollment Period. Even if you were satisfied with your plan this year, changes might make a different plan more suitable for next year.
Choosing Based Only on Price
The lowest premium doesn't always mean the lowest total cost. Consider a hypothetical comparison:
Plan A: $0 premium, $8,000 maximum out-of-pocket, limited pharmacy network
Plan B: $45 monthly premium ($540 annually), $3,000 maximum out-of-pocket, broad pharmacy network
If you have a hospital stay, Plan B could save you thousands despite the higher premium. Evaluate your likely healthcare usage, not just the monthly cost.
Ignoring Provider Networks
Medicare Advantage plans typically use networks (HMO, PPO, or regional PPO structures). Verify that your current doctors, specialists, and preferred hospitals participate in any plan you're considering.
Call your doctors' offices directly-don't rely solely on online directories, which may be outdated. Ask specifically: "Do you accept [Plan Name] for Medicare Advantage patients?" This simple verification prevents surprises after enrollment.
Getting Personalized Medicare Guidance
While online resources provide valuable information, personalized guidance helps you apply general Medicare knowledge to your specific situation. Your health conditions, medications, preferred providers, and financial circumstances create a unique context for decision-making.
Questions to Ask During Consultations
When meeting with a local Medicare advisor in Greensboro, Winston-Salem, High Point, or Kernersville, prepare these essential questions:
- Which plans include my current doctors and specialists in-network?
- How much will my specific prescriptions cost under different plans?
- What are the total estimated annual costs for each plan type?
- Can I keep this plan if I travel or spend time in another state?
- What happens if I need specialized care not available locally?
- How does this plan handle prior authorizations for treatments?
- What dental, vision, or hearing benefits are included?
Bringing the Right Information
Maximize the value of your consultation by bringing:
- List of current medications (with dosages)
- Names and contact information for your doctors and specialists
- Summary of your typical healthcare usage (annual doctor visits, any upcoming procedures)
- Current Medicare card and any existing insurance cards
- Questions about specific health concerns or anticipated medical needs
This preparation allows your advisor to provide accurate plan comparisons specific to your situation rather than general information.
Exploring Additional Coverage Options
Beyond basic Medicare, supplemental coverage addresses specific needs that arise as your healthcare requirements evolve.
Hospital Indemnity Plans
A hospital indemnity plan provides cash payments when you're hospitalized, regardless of what your Medicare coverage pays. These supplemental policies pay benefits directly to you based on:
- Per-day hospitalization (often $100-$300 per day)
- Admission benefit (lump sum when admitted)
- ICU stays (higher daily benefit)
You can use these cash benefits however you choose-deductibles, copayments, household bills during recovery, or transportation costs. Hospital indemnity plans complement Medicare coverage by addressing indirect costs of hospitalization.
Dental, Vision, and Hearing Coverage
Original Medicare provides limited coverage for dental, vision, and hearing services. Most coverage for these services requires either:
- A Medicare Advantage plan with built-in benefits
- Standalone dental or vision insurance
- Discount programs that reduce out-of-pocket costs
Dental coverage becomes increasingly important for overall health, as oral health connects directly to cardiovascular health, diabetes management, and nutrition. Budget for these expenses in your healthcare planning even if they're not covered by your primary Medicare insurance.
Staying Informed About Medicare Changes
Medicare rules, costs, and coverage options change annually. Staying informed ensures you continue receiving optimal coverage as the program evolves.
Annual Changes to Watch
Each fall, the Centers for Medicare & Medicaid Services announces changes effective the following January:
- Part B premium and deductible amounts: The standard Part B premium increases most years
- Part D coverage gap (donut hole): The coverage gap closed in 2020, but the catastrophic threshold continues adjusting
- Medicare Advantage plan modifications: Plans can change networks, benefits, and cost-sharing annually
- Preventive services additions: New preventive screenings may become covered
The official Medicare publications page provides updated handbooks and guides reflecting current-year information.
Following Reputable Information Sources
Rely on authoritative sources for Medicare information:
- Medicare.gov: The official Medicare website with plan comparison tools and enrollment information
- 1-800-MEDICARE (1-800-633-4227): 24/7 help line for Medicare beneficiaries
- State Health Insurance Assistance Program: Free, unbiased counseling specific to North Carolina
- Local independent insurance agents: Licensed professionals who understand regional plan options
Avoid making decisions based solely on television commercials or unsolicited phone calls about Medicare plans. These marketing efforts may promote specific plans without presenting the full range of options available in your area.
Finding the right medicare insurance near me requires understanding your options, comparing plans based on your specific needs, and enrolling during the correct time periods. Whether you're new to Medicare or reviewing your current coverage, local expertise makes this complex decision more manageable. Moser Insurance Group Inc provides personalized Medicare guidance to residents throughout the Triad Area, helping you understand Medicare Supplement plans, Medicare Advantage options, and prescription drug coverage without pressure. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to schedule your consultation and explore which Medicare options work best for your situation.
Recent Comments