

Medicare C coverage, officially known as Medicare Advantage, represents a comprehensive alternative to Original Medicare that bundles hospital insurance, medical coverage, and often prescription drug benefits into a single plan. As residents in Greensboro, Kernersville, High Point, Winston Salem, and throughout the Triad Area approach their Medicare eligibility, understanding how Medicare Advantage plans work becomes essential for making informed healthcare decisions. These plans have grown significantly in popularity, with millions of beneficiaries choosing them for their all-in-one convenience and additional benefits beyond what Original Medicare provides.
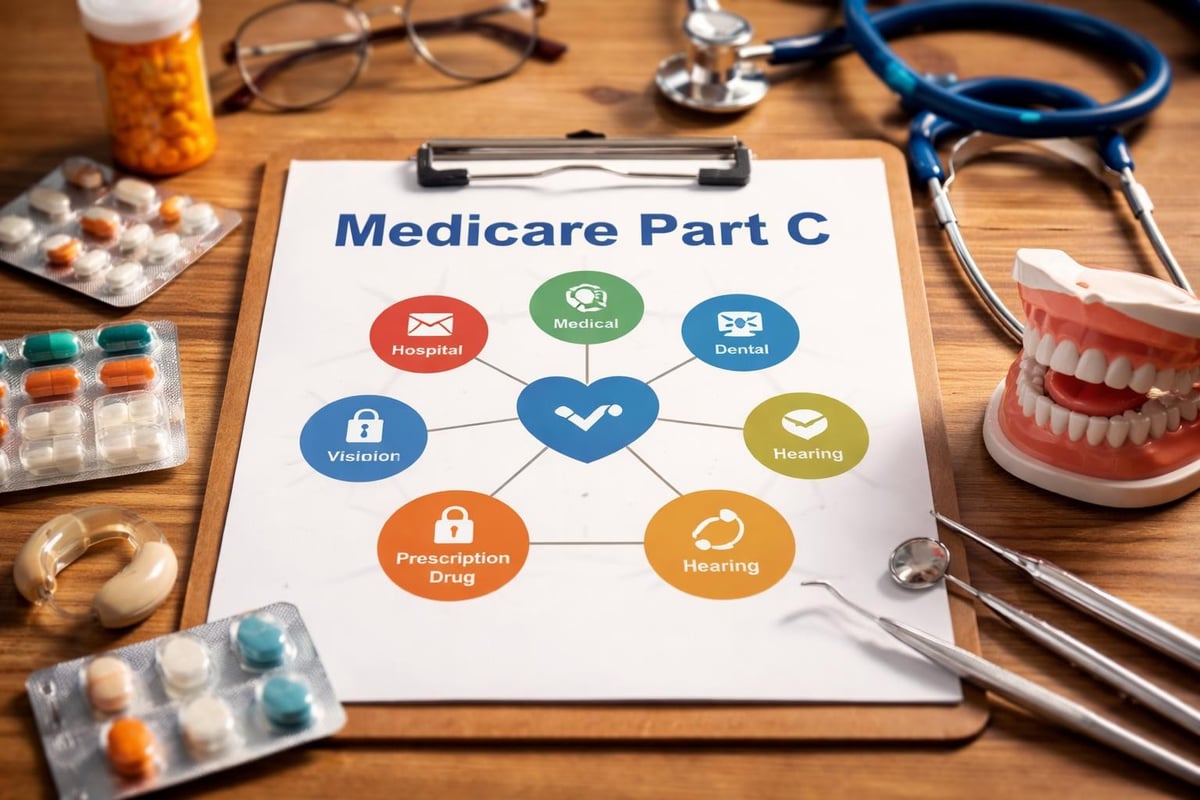
What Medicare C Coverage Includes
Medicare C coverage combines all the benefits of Medicare Part A (hospital insurance) and Part B (medical insurance) while frequently adding extra services that Original Medicare doesn't cover. Most Medicare Advantage plans include prescription drug coverage, eliminating the need for a separate Part D plan.
Core Benefits and Additional Services
The foundation of medicare c coverage mirrors Original Medicare, but private insurance companies approved by Medicare deliver these benefits. This structure allows plans to customize their offerings while meeting federal requirements.
Standard Coverage Components:
- Inpatient hospital care and skilled nursing facility services
- Doctor visits, outpatient care, and preventive services
- Emergency and urgent care, both domestically and internationally
- Medical equipment, laboratory tests, and diagnostic services
Many plans extend beyond these basics to include vision, dental, and hearing services. These additional benefits address common healthcare needs that Original Medicare leaves as out-of-pocket expenses. According to data on Medicare beneficiaries’ coverage sources, Medicare Advantage enrollment continues to rise as beneficiaries seek comprehensive coverage.
Prescription Drug Integration
Most Medicare Advantage plans incorporate prescription drug coverage (Part D) directly into the plan structure. This integration simplifies medication management and coordination of benefits, creating a streamlined experience for members who need regular prescriptions.
| Benefit Category | Original Medicare | Typical Medicare C Coverage |
|---|---|---|
| Hospital Care | Covered | Covered |
| Doctor Visits | Covered | Covered |
| Prescription Drugs | Requires Part D | Usually Included |
| Dental Services | Not Covered | Often Included |
| Vision Care | Limited | Usually Included |
| Hearing Aids | Not Covered | Often Included |
| Fitness Programs | Not Covered | Frequently Included |
Types of Medicare Advantage Plans
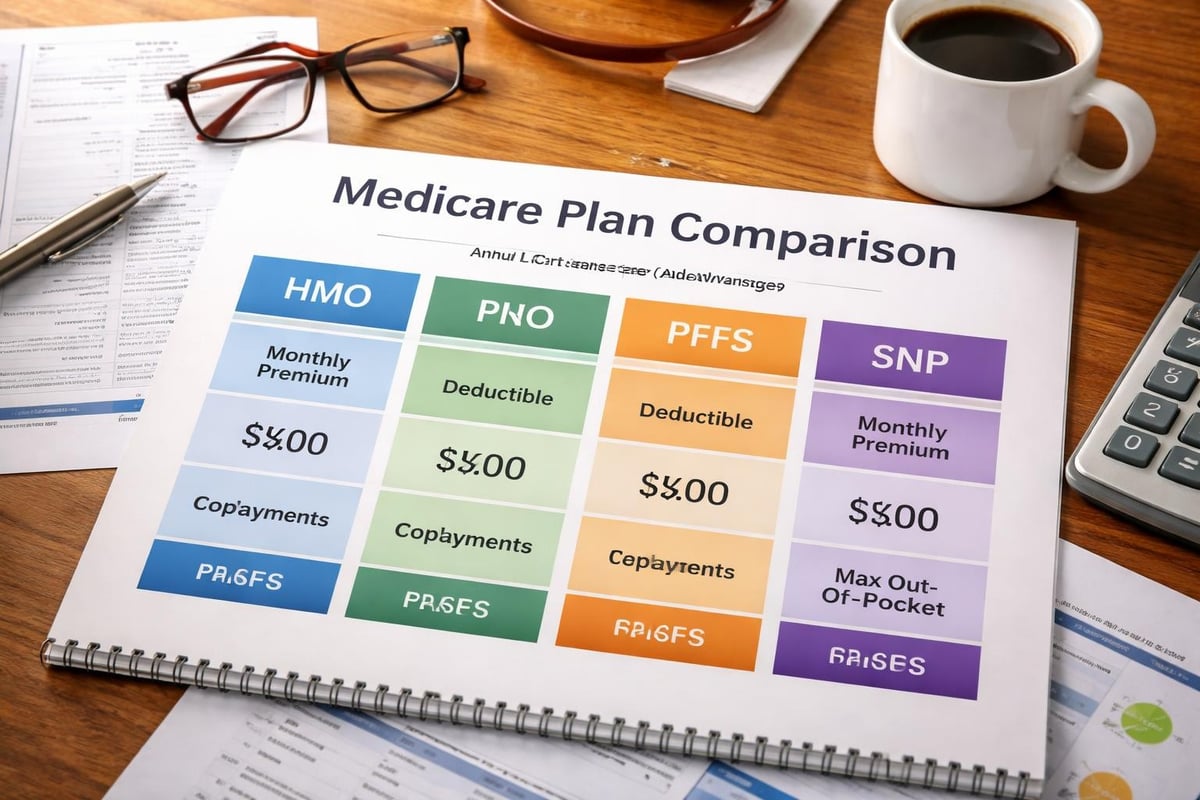
Medicare c coverage comes in several distinct plan structures, each with different network requirements and cost-sharing arrangements. Understanding these variations helps beneficiaries select plans that match their healthcare preferences and financial situations.
Health Maintenance Organization (HMO) Plans
HMO plans require members to use network providers except in emergencies. These plans typically mandate selecting a primary care physician who coordinates care and provides referrals to specialists. The American Academy of Family Physicians discusses Medicare coverage, emphasizing how primary care coordination benefits comprehensive patient management.
HMO Plan Characteristics:
- Lower monthly premiums compared to other plan types
- Coordinated care through primary care physician
- Limited coverage for out-of-network services
- Predictable cost structure with set copayments
- Strong focus on preventive care management
Preferred Provider Organization (PPO) Plans
PPO plans offer greater flexibility by allowing members to see any Medicare-approved provider without referrals. While using in-network providers costs less, these plans provide partial coverage for out-of-network care, making them attractive for beneficiaries who travel frequently or want provider choice.
The trade-off for this flexibility typically involves higher monthly premiums and potentially higher out-of-pocket costs. For residents in the Triad Area who split time between locations or have established relationships with specific specialists, PPO plans may justify the additional expense.
Special Needs Plans (SNPs)
Special Needs Plans target specific populations with tailored benefits. These medicare c coverage options serve beneficiaries with chronic conditions, those eligible for both Medicare and Medicaid, or individuals requiring institutional-level care.
Cost Considerations for Medicare C Coverage
Understanding the financial aspects of Medicare Advantage plans requires examining multiple cost components beyond the monthly premium. These plans structure expenses differently than Original Medicare, creating both opportunities for savings and potential financial considerations.
Premium and Out-of-Pocket Expenses
Many Medicare Advantage plans charge zero or low monthly premiums, but members must continue paying their Part B premium to Medicare. The 2024 Medicare Advantage and Part D Final Rule outlines regulatory changes affecting plan costs and coverage requirements.
Cost Elements to Evaluate:
- Monthly plan premium (in addition to Part B premium)
- Annual deductible amounts for medical and prescription services
- Copayments for doctor visits, specialists, and procedures
- Maximum out-of-pocket limits that cap annual expenses
- Prescription drug tier pricing and coverage gaps
| Cost Component | Typical Range | What It Covers |
|---|---|---|
| Monthly Premium | $0 – $200 | Plan membership fee |
| Medical Deductible | $0 – $500 | Before plan pays for services |
| Doctor Visit Copay | $0 – $50 | Primary care appointments |
| Specialist Copay | $20 – $75 | Specialist consultations |
| Maximum Out-of-Pocket | $3,000 – $8,850 | Annual spending limit |
Comparing Total Annual Costs
Smart medicare c coverage selection requires projecting total annual healthcare expenses rather than focusing solely on monthly premiums. A plan with zero premium might have higher copayments that ultimately cost more for someone with frequent medical needs.
For personalized guidance on comparing costs specific to your situation in Greensboro, Kernersville, High Point, or Winston Salem, contact Moser Insurance Group Inc at 336-862-1763 or visit moserinsurancegroup.com.
Network Restrictions and Provider Access
Medicare Advantage plans operate through contracted provider networks, which fundamentally changes how beneficiaries access healthcare compared to Original Medicare. Understanding network structures prevents surprise bills and ensures access to preferred doctors and hospitals.
Finding In-Network Providers
Each plan maintains a directory of participating physicians, specialists, hospitals, and other healthcare facilities. Before enrolling in medicare c coverage, beneficiaries should verify that their current providers accept the plan they're considering.
The networks can vary significantly even within the same geographic area. Two Medicare Advantage plans available in the Triad Area might have completely different hospital and physician networks despite similar benefit structures.
Coverage During Travel
Travel considerations matter for beneficiaries who spend time outside their plan's service area. Most Medicare Advantage plans provide emergency coverage nationwide, but routine care typically requires staying within the network geography.
Some plans offer nationwide networks or special travel benefits. Snowbirds who split time between North Carolina and other states should prioritize plans with appropriate geographic coverage or consider switching plans during Annual Enrollment Period.
Enrollment Periods and Eligibility Requirements
Medicare c coverage enrollment follows specific timeframes established by federal regulations. Missing these windows can delay coverage or limit plan choices, making it essential to understand when and how to enroll.
Initial Enrollment Period
New Medicare beneficiaries can choose Medicare Advantage during their Initial Enrollment Period, which spans seven months around their 65th birthday or qualifying event. This window begins three months before the eligibility month and extends three months after.
Enrollment Timeline:
- Research available plans two to three months before eligibility
- Compare benefits, costs, and networks across options
- Verify provider participation in preferred plans
- Submit enrollment application during the seven-month window
- Receive coverage effective the first day of eligibility month
For help understanding when you become eligible for Medicare, attending a local seminar can provide valuable insights into the enrollment process.
Annual Enrollment Period
The Annual Enrollment Period (AEP) runs from October 15 through December 7 each year, allowing current Medicare beneficiaries to switch from Original Medicare to Medicare Advantage, change between Medicare Advantage plans, or return to Original Medicare. Coverage changes take effect January 1 of the following year.
This period generates significant activity as plans announce benefit changes for the upcoming year. AARP’s Medicare overview provides detailed information about enrollment rights and options during these periods.
Special Enrollment Periods
Certain qualifying events trigger Special Enrollment Periods outside the standard timeframes. These include moving outside your plan's service area, losing other creditable coverage, qualifying for Medicaid, or moving into a nursing home.
Plan Selection Strategy
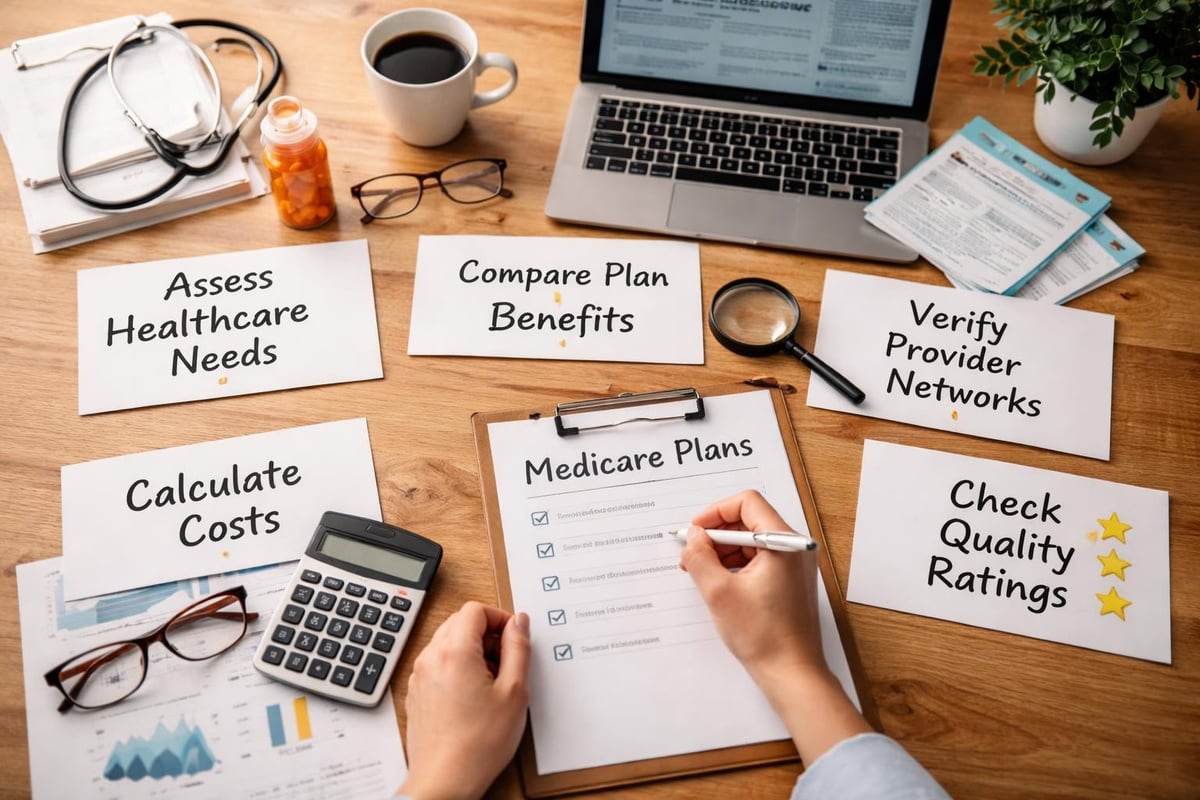
Choosing the right medicare c coverage requires systematic evaluation of personal healthcare needs, financial circumstances, and lifestyle factors. A methodical approach prevents costly mistakes and ensures the selected plan aligns with individual priorities.
Assessing Your Healthcare Needs
Begin by inventorying current healthcare utilization and anticipated future needs. List all regular medications, specialist relationships, planned procedures, and chronic condition management requirements.
Healthcare Inventory Checklist:
- Current prescription medications and monthly costs
- Physicians and specialists you visit regularly
- Planned surgeries or procedures for the upcoming year
- Chronic conditions requiring ongoing management
- Preferred hospitals and medical facilities
- Vision, dental, and hearing care needs
This assessment creates the foundation for comparing how different plans cover your specific situation. A plan offering excellent benefits that don't match your needs provides limited value.
Evaluating Plan Quality Ratings
Medicare assigns star ratings to Medicare Advantage plans based on quality and performance measures. These ratings range from one to five stars, with higher ratings indicating better plan performance in areas like customer service, health screenings, and chronic disease management.
Plans with higher star ratings may offer additional benefits or lower costs due to quality bonus payments from Medicare. Reviewing these ratings adds an objective quality measure to the selection process.
Understanding Prior Authorization Requirements
Many Medicare Advantage plans require prior authorization for certain services, procedures, or medications before providing coverage. This administrative process can affect access to care and requires understanding to navigate effectively. The HHS OIG report on prior authorization in Medicare Advantage plans examines how these requirements impact beneficiary care access.
How Prior Authorization Works
When your doctor recommends a service requiring prior authorization, they submit a request to your Medicare c coverage plan explaining why the service is medically necessary. The plan reviews this request against coverage criteria before approving or denying the service.
This process typically takes several days but can be expedited for urgent situations. Understanding which services require prior authorization helps set appropriate expectations and allows for advance planning when scheduling elective procedures.
Managing Denials and Appeals
If a prior authorization request is denied, beneficiaries have the right to appeal the decision. The appeals process follows specific steps with defined timeframes, and many denials are overturned when additional medical documentation supports the necessity of the requested service.
Supplemental Benefits and Wellness Programs
Modern medicare c coverage extends well beyond traditional medical services, incorporating benefits that support overall health and quality of life. These supplemental offerings differentiate plans and provide tangible value for beneficiaries focused on preventive care and healthy aging.
Fitness and Wellness Memberships
Many plans include fitness program memberships at no additional cost, providing access to gyms, fitness classes, and wellness centers throughout their service area. These programs combat sedentary lifestyles and support chronic condition management through structured physical activity.
Some plans offer home-based fitness solutions for members with mobility limitations or those who prefer exercising at home. These alternatives ensure all members can benefit from fitness resources regardless of physical capability.
Transportation Services
Non-emergency medical transportation helps members attend doctor appointments, pick up prescriptions, and access preventive care services. This benefit particularly supports members who no longer drive or lack reliable transportation options.
Common Supplemental Benefits:
- Routine vision exams and eyewear allowances
- Comprehensive dental services including cleanings and restorations
- Hearing exams and hearing aid coverage
- Over-the-counter medication allowances
- Meal delivery after hospital discharge
- In-home support services for daily living activities
Geographic Availability in North Carolina
Medicare Advantage plan availability varies by location, with different insurers offering plans in different counties and regions. The Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, has robust plan availability, but specific options differ between adjacent counties.
Regional Plan Variations
Insurance companies design plan networks around local healthcare infrastructure and provider relationships. A plan available in Greensboro might not be offered in neighboring counties, or it might have different provider networks even when the same plan name appears in multiple locations.
This geographic variation makes it essential to verify plan availability using your specific ZIP code. National plan names don't guarantee identical benefits or networks across different regions.
For personalized assistance comparing medicare c coverage options available in your specific Triad Area location, email moserinsurancegroup@gmail.com or attend one of our educational Medicare seminars.
Regulatory Framework and Consumer Protections
Federal regulations govern Medicare Advantage plans, establishing minimum coverage standards, financial protections, and beneficiary rights. Understanding these regulatory protections empowers beneficiaries to advocate for appropriate care and appeal unfavorable decisions. Resources on federal laws governing Medicare Parts C and D provide deeper insight into the legal framework.
Coverage Requirements and Standards
All Medicare Advantage plans must cover everything Original Medicare covers at a minimum. Plans cannot charge more than Original Medicare for certain services like chemotherapy or dialysis, and they must limit annual out-of-pocket expenses to federally established maximums.
These protections ensure that choosing medicare c coverage doesn't result in coverage gaps for essential services. Plans can offer additional benefits but cannot reduce the baseline coverage that Original Medicare provides.
Grievance and Appeals Rights
Beneficiaries dissatisfied with plan decisions have multiple levels of appeal rights. The process begins with the plan's internal review and can escalate to independent review entities and administrative law judges if initial appeals are unsuccessful.
Understanding these rights ensures members can challenge inappropriate coverage denials or advocate for necessary care when plans make unfavorable determinations.
Coordination with Other Insurance Coverage
Some Medicare beneficiaries maintain additional insurance coverage from employers, unions, or other sources. Understanding how medicare c coverage coordinates with these other policies prevents coverage gaps and optimizes benefit utilization.
Employer Group Coverage
Beneficiaries with employer coverage must evaluate whether keeping that coverage makes sense alongside Medicare. In some cases, employer coverage works as primary insurance with Medicare as secondary. In other situations, choosing Medicare Advantage makes more financial sense than maintaining employer coverage.
The coordination rules depend on employer size, coverage type, and specific plan provisions. This complexity makes professional guidance valuable for beneficiaries navigating multiple coverage options.
Veterans Benefits Coordination
Veterans with VA healthcare benefits can enroll in Medicare Advantage, though they cannot use both simultaneously for the same service. Understanding how these programs interact helps veterans maximize available benefits without creating conflicts or duplicate coverage.
Making the Switch from Original Medicare
Beneficiaries currently enrolled in Original Medicare with a Medigap policy face specific considerations when contemplating a switch to medicare c coverage. The decision requires careful evaluation of current coverage satisfaction, future healthcare needs, and the difficulty of potentially returning to Medigap coverage later.
Evaluating Current Coverage Gaps
Original Medicare with Medigap provides predictable costs and unlimited provider choice but typically requires a separate Part D plan and doesn't include many supplemental benefits. Medicare Advantage consolidates coverage but introduces network restrictions.
| Consideration | Original Medicare + Medigap | Medicare Advantage |
|---|---|---|
| Provider Choice | Any Medicare provider | Network restrictions |
| Prescription Drugs | Requires separate Part D | Usually included |
| Dental/Vision/Hearing | Not covered | Often included |
| Travel Coverage | Extensive | Emergency only |
| Cost Predictability | High | Variable by plan |
| Referral Requirements | None | Depends on plan type |
Understanding Medigap Protections
When switching from Medigap to Medicare Advantage, beneficiaries generally lose their guaranteed Medigap enrollment rights. If they later want to return to Medigap, insurance companies can deny coverage or charge higher premiums based on health status.
This one-way door makes the decision to leave Medigap coverage particularly significant. The Medicare Managed Care Manual details rules and regulations governing these transitions and protections.
Plan Changes and Coverage Transitions
Medicare c coverage evolves annually as plans modify benefits, adjust costs, and revise provider networks. Staying informed about these changes ensures continued coverage alignment with healthcare needs and prevents unpleasant surprises.
Annual Notice of Change
Plans must send beneficiaries an Annual Notice of Change (ANOC) by September 30 each year, detailing any modifications taking effect January 1. This document compares current year benefits to upcoming year changes, highlighting cost adjustments, benefit modifications, and network updates.
Reviewing this notice carefully allows members to determine whether their current plan still meets their needs or whether switching during the Annual Enrollment Period makes sense.
Evidence of Coverage Review
The Evidence of Coverage (EOC) document provides comprehensive details about plan benefits, costs, coverage rules, and member rights. This lengthy document serves as the definitive reference for understanding exactly what the plan covers and how it works.
While detailed, the EOC answers specific coverage questions and clarifies ambiguous situations. Keeping this document accessible facilitates informed healthcare decisions throughout the year.
Understanding medicare c coverage empowers Triad Area residents to make confident decisions about their healthcare future. Whether you're approaching Medicare eligibility or reconsidering your current coverage during Annual Enrollment, comprehensive knowledge of plan types, costs, benefits, and protections creates the foundation for selecting coverage that truly meets your needs. Moser Insurance Group Inc provides personalized guidance to individuals and families in Greensboro, Kernersville, High Point, Winston Salem, and throughout the region, helping you navigate Medicare options without pressure or confusion. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to receive clear, educational support for your Medicare decisions.
Recent Comments