

Navigating the healthcare landscape as you approach or enter retirement requires understanding how medicare and supplemental insurance work together to protect your financial security. Original Medicare (Part A and Part B) provides essential hospital and medical coverage, but it leaves significant gaps in the form of deductibles, copayments, and coinsurance that can add up quickly. This is where supplemental insurance enters the picture, offering additional protection that can make healthcare costs more predictable and manageable. Whether you live in the Triad Area, Greensboro, Kernersville, High Point, or Winston Salem, understanding your options helps you make confident decisions about your healthcare future.
Understanding the Relationship Between Medicare and Supplemental Insurance
Medicare and supplemental insurance function as complementary layers of protection. Original Medicare covers approximately 80% of your healthcare costs after you meet specific deductibles, leaving you responsible for the remaining 20% plus other out-of-pocket expenses. Without supplemental coverage, these gaps can create financial uncertainty, particularly if you face serious illness or require frequent medical care.
Medicare Supplement Insurance (Medigap) is the most common form of supplemental coverage designed specifically to work alongside Original Medicare. Private insurance companies sell these standardized policies, which are regulated by both federal and state authorities to ensure consistency and consumer protection.
What Original Medicare Covers and Doesn't Cover
Original Medicare consists of two parts that work together:
Part A (Hospital Insurance) covers:
- Inpatient hospital stays
- Skilled nursing facility care (limited conditions)
- Hospice care
- Home health care (limited)
Part B (Medical Insurance) covers:
- Doctor visits and outpatient care
- Preventive services
- Medical equipment
- Lab tests and X-rays
What Medicare doesn't cover creates the need for supplemental insurance:
- Part A deductible ($1,676 in 2026)
- Part B deductible ($257 in 2026)
- 20% coinsurance for most Part B services
- Excess charges when doctors charge more than Medicare-approved amounts
- Foreign travel emergency care
- Long-term care
Types of Medicare Supplemental Insurance Plans
The term "medicare and supplemental insurance" most commonly refers to Medigap policies, which are labeled with letters (Plan A, Plan B, Plan C, etc.) through Plan N. Each plan type offers a different combination of benefits, with some providing more comprehensive coverage than others.
Standardized Medigap Plan Options
| Plan Type | Part A Deductible | Part B Deductible | Part B Excess Charges | Foreign Travel Emergency |
|---|---|---|---|---|
| Plan A | No | No | No | No |
| Plan B | Yes | No | No | No |
| Plan D | Yes | No | No | Yes (80%) |
| Plan G | Yes | No | Yes | Yes (80%) |
| Plan K | 50% | No | No | No |
| Plan L | 75% | No | No | No |
| Plan M | 50% | No | No | Yes (80%) |
| Plan N | Yes | No | No | Yes (80%) |
Plan F, historically the most comprehensive option, is no longer available to those newly eligible for Medicare after January 1, 2020, though current enrollees can keep their existing plans. Plan G has emerged as the most popular choice for new Medicare beneficiaries because it covers nearly everything except the Part B deductible.
High-Deductible Options
Some plans offer high-deductible versions that feature lower monthly premiums in exchange for higher out-of-pocket costs before coverage begins. In 2026, the high-deductible threshold is $2,800. These plans work well for generally healthy individuals who want catastrophic protection without paying higher monthly premiums.
Enrollment Timing and Guaranteed Issue Rights
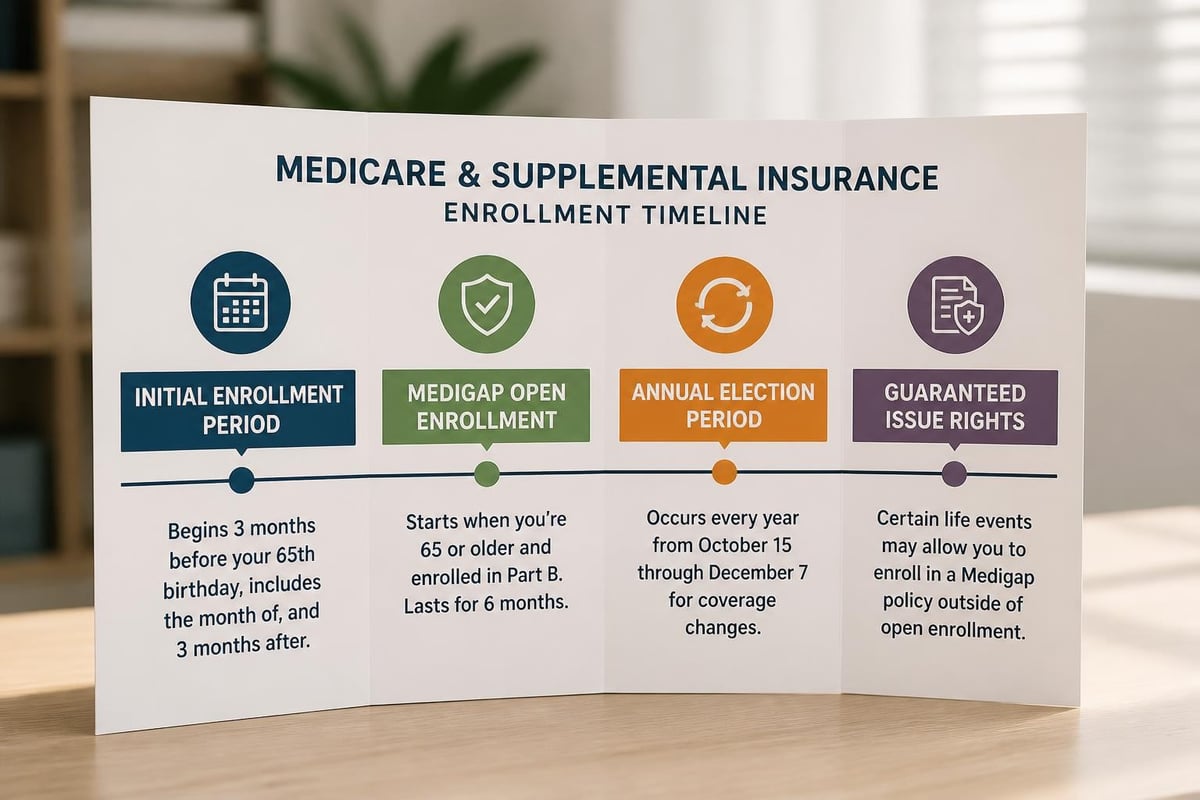
Understanding when you can enroll in medicare and supplemental insurance is crucial because timing affects your rights and premium costs. The six-month Medigap Open Enrollment Period begins the month you turn 65 and are enrolled in Medicare Part B. During this window, insurance companies cannot deny you coverage or charge higher premiums based on pre-existing health conditions.
Critical Enrollment Windows
Medigap Open Enrollment Period (most important):
- Starts the first day of the month you turn 65 and have Part B
- Lasts for six months
- Guaranteed issue rights protect you
- Cannot be denied or charged more for health conditions
- Best time to shop for competitive rates
Missing this window doesn't mean you can't get supplemental insurance later, but companies can review your medical history, charge higher premiums, or deny coverage altogether in most states. According to Medicare’s official Medigap guide, this open enrollment period represents your strongest consumer protection.
Guaranteed Issue Rights in Special Situations
Beyond the initial enrollment period, certain life events trigger guaranteed issue rights that allow you to purchase Medigap without medical underwriting:
- Your Medicare Advantage plan is leaving your area or stops providing coverage
- You move out of your plan's service area
- Your Medigap company goes bankrupt
- You were misled about your coverage
For residents in the Triad Area, Greensboro, Kernersville, High Point, and Winston Salem, understanding North Carolina's specific rules around guaranteed issue rights helps protect your ability to obtain supplemental coverage when circumstances change.
How Medicare Advantage Differs From Supplemental Insurance
When discussing medicare and supplemental insurance, it's essential to understand that Medicare Advantage (Part C) is not the same as Medigap, even though both provide additional coverage beyond Original Medicare. These are alternative approaches, and you cannot have both simultaneously.
Medicare Advantage plans are "all-in-one" alternatives to Original Medicare offered by private insurance companies. They include Part A, Part B, and usually Part D prescription drug coverage, often with additional benefits like dental, vision, and hearing coverage. Medicare Supplement or Medicare Advantage plans each have distinct advantages depending on your healthcare needs, budget, and preferences.
Key Differences at a Glance
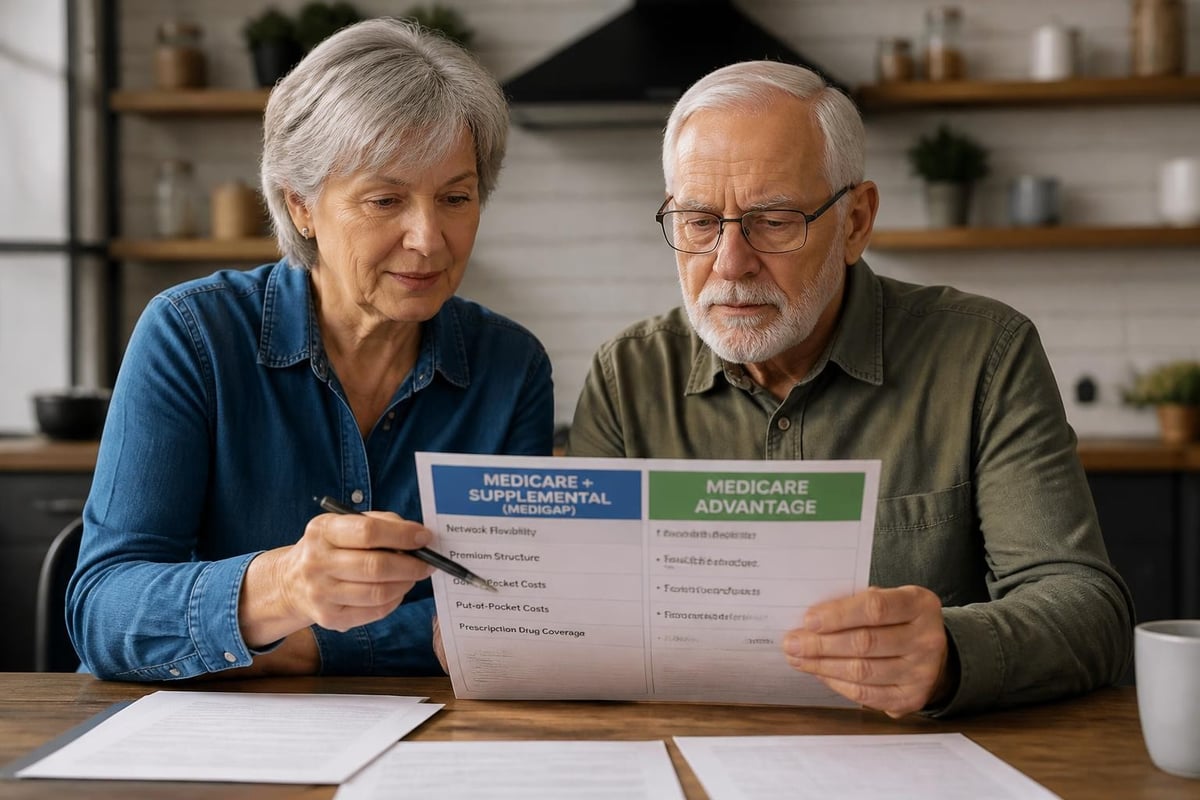
- Network restrictions: Medicare Advantage typically requires you to use specific doctors and hospitals; Medigap works with any provider accepting Medicare
- Out-of-pocket maximums: Medicare Advantage plans have yearly limits on your costs; Original Medicare with Medigap has no such cap but may have lower overall costs
- Premium structure: Medicare Advantage often has lower monthly premiums but higher costs when you use services; Medigap has higher premiums but more predictable costs
- Prescription coverage: Medicare Advantage usually includes drug coverage; with Medigap you need separate Part D
- Geographic flexibility: Medigap provides better coverage when traveling; Medicare Advantage networks are typically local
The AARP comparison of Medigap versus Medicare Advantage offers additional consumer-facing perspectives on making this choice, highlighting that neither option is universally better-the right choice depends on your individual circumstances.
Cost Considerations for Supplemental Insurance
Premium costs for medicare and supplemental insurance vary significantly based on multiple factors. Understanding these variables helps you budget appropriately and compare options effectively.
Factors That Affect Your Premiums
Age: Insurance companies use three pricing methods:
- Community-rated: Everyone pays the same regardless of age
- Issue-age-rated: Premium based on your age when you buy the policy, doesn't increase with age
- Attained-age-rated: Premium increases as you get older
Most insurers in North Carolina use attained-age rating, meaning your premiums will rise annually as you age, in addition to general cost-of-living increases.
Location: Where you live significantly impacts costs. Premiums in the Triad Area might differ from other regions of North Carolina due to local healthcare costs, competition among insurers, and demographic factors.
Tobacco use: Smokers typically pay 15-20% more for Medigap coverage compared to non-smokers.
Plan type: More comprehensive plans cost more. Plan G typically has higher premiums than Plan N, which in turn costs more than Plan K or L.
Average Cost Ranges in 2026
According to NAIC industry analysis, average monthly Medigap premiums for a 65-year-old range from approximately $140 for Plan N to $220 for Plan G, though individual quotes vary considerably based on the factors mentioned above.
When budgeting for medicare and supplemental insurance, remember to include:
- Monthly Medigap premium
- Monthly Part B premium ($185 in 2026 for most people)
- Part D prescription drug plan premium (if not enrolled in Medicare Advantage)
- Any remaining deductibles your Medigap plan doesn't cover
Choosing the Right Supplemental Coverage
Selecting appropriate supplemental insurance requires evaluating your healthcare needs, financial situation, and personal preferences. No single plan fits everyone, which is why understanding your options matters.
Questions to Guide Your Decision
Healthcare utilization:
- How often do you visit doctors?
- Do you have chronic conditions requiring regular care?
- Do you prefer the freedom to see any Medicare provider?
- Do you travel frequently and need coverage outside your home area?
Financial factors:
- Can you afford higher monthly premiums for more comprehensive coverage?
- Would you prefer lower premiums with higher out-of-pocket costs when you need care?
- Do you have savings to cover unexpected medical expenses?
Personal preferences:
- Do you value predictable costs or lower monthly bills?
- Are you comfortable managing referrals and network restrictions?
- How important is coverage for services beyond what Medicare covers?
Popular Plan Choices and Why
Plan G remains the top choice for most new Medicare beneficiaries because it offers comprehensive coverage with only the Part B deductible as an out-of-pocket cost. The predictability appeals to those who want minimal financial uncertainty.
Plan N attracts budget-conscious individuals who don't mind small copayments ($20 for office visits, $50 for emergency room visits that don't result in admission) in exchange for lower monthly premiums.
High-deductible Plan G suits healthy individuals who want catastrophic protection without paying high monthly premiums, understanding they'll cover routine costs out-of-pocket until reaching the deductible.
The State Health Insurance Assistance Program (SHIP) provides free, unbiased counseling to help North Carolina residents compare medicare and supplemental insurance options. These state-based resources can be invaluable when evaluating plans specific to your local area.
Common Mistakes to Avoid
Many Medicare beneficiaries make preventable errors when selecting supplemental coverage. Awareness of these pitfalls helps you navigate the process successfully.
Waiting Too Long to Enroll
The single biggest mistake is missing your Medigap Open Enrollment Period. Once this six-month window closes, you lose guaranteed issue rights in most circumstances. Medical underwriting can result in coverage denial or premiums two to three times higher than standard rates if you have health conditions.
Choosing Based Solely on Price
While cost matters, selecting the cheapest plan without considering coverage adequacy can be penny-wise and pound-foolish. A plan with a $30 lower monthly premium might cost you thousands more in out-of-pocket expenses if you face serious illness.
Not Understanding Plan Differences
All Plan G policies, for example, offer identical benefits regardless of which insurance company sells them. The only differences are price and customer service. Shopping around among insurers for the same plan type can save hundreds of dollars annually.
Overlooking Household Discount Opportunities
Some insurers offer household discounts when spouses both purchase Medigap policies from the same company. These savings can be substantial over time but require asking specifically about available discounts.
Failing to Review Coverage Annually
Your health needs and financial situation change over time. While you can't switch Medigap plans without medical underwriting outside your initial enrollment period in most states, reviewing your coverage ensures it still meets your needs. During your annual review, prepare for Medicare considerations including whether your current supplemental approach remains optimal.
Working With Insurance Professionals
Navigating medicare and supplemental insurance can feel overwhelming given the numerous plan options, timing considerations, and regulatory details. Working with experienced insurance professionals who specialize in Medicare can simplify the process and help you avoid costly mistakes.
What to Look for in a Medicare Insurance Advisor
Knowledge and expertise: Look for professionals who focus specifically on Medicare rather than generalists who handle all insurance types. Medicare rules, plan options, and enrollment periods require specialized knowledge.
Educational approach: The best advisors take time to explain your options without pressure, ensuring you understand the differences between plans and how they align with your needs. You should never feel rushed into a decision.
Local market understanding: Someone familiar with your area's healthcare providers, hospital systems, and insurance company options can offer more relevant guidance. An advisor serving the Triad Area, Greensboro, Kernersville, High Point, and Winston Salem understands North Carolina-specific considerations.
Transparency about compensation: Reputable Medicare advisors explain how they're compensated and ensure you understand there's no cost to you for their assistance-insurance companies pay commissions, not consumers.
Questions to Ask Potential Advisors
- How long have you specialized in Medicare insurance?
- Which insurance companies do you work with?
- Can you explain the differences between Medigap and Medicare Advantage for my situation?
- What happens if I need help with a claim or coverage question after I enroll?
- Do you provide ongoing service, or is your involvement limited to the initial enrollment?
According to CMS state-by-state data, the Medicare insurance landscape varies significantly by location, reinforcing the value of working with someone who understands your local market dynamics.
The Future of Medicare and Supplemental Insurance
The medicare and supplemental insurance landscape continues to evolve as healthcare costs rise, demographics shift, and policy changes occur. Understanding current trends helps you anticipate potential changes that might affect your coverage decisions.
Recent and Upcoming Changes
The elimination of first-dollar coverage plans (Plan C and Plan F) for new Medicare beneficiaries reflects legislative efforts to encourage more cost-conscious healthcare utilization. This shift has positioned Plan G as the new standard for comprehensive coverage.
Premium trends show consistent increases averaging 4-6% annually, driven by rising healthcare costs and increased utilization as the Medicare population grows. The MedPAC Report to Congress analyzes these market dynamics and projects continued pressure on supplemental insurance premiums.
Policy Discussions Affecting Supplemental Coverage
Ongoing debates in Congress about Medicare reform could impact supplemental insurance in various ways:
- Proposals to add dental, vision, and hearing benefits to Original Medicare might reduce the value proposition of Medicare Advantage plans
- Discussions about out-of-pocket caps for Original Medicare could change the role of Medigap
- Potential modifications to Medigap standardization could create new plan options or eliminate existing ones
While predicting specific changes is impossible, staying informed about policy developments helps you make better long-term decisions about your coverage.
State-Specific Considerations in North Carolina
Medicare is a federal program, but supplemental insurance includes state-level variations that affect residents of North Carolina differently than beneficiaries in other states.
North Carolina Medigap Regulations
North Carolina does not require insurers to offer birthday rules or annual open enrollment periods for Medigap, unlike some states that provide additional consumer protections. This makes your initial six-month Medigap Open Enrollment Period even more critical for North Carolina residents.
The state does regulate rate increases and requires insurers to justify premium changes, providing some consumer protection against excessive cost growth. North Carolina's Department of Insurance oversees Medigap policies sold in the state, handling complaints and ensuring companies comply with federal and state regulations.
Regional Healthcare Considerations
The Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, features numerous Medicare-accepting healthcare providers and hospital systems. The density of healthcare options in this region generally means competitive insurance markets and good access to care regardless of whether you choose Medigap or Medicare Advantage.
However, if you travel frequently or spend significant time outside North Carolina, Medigap's nationwide provider access becomes particularly valuable. Medicare Advantage networks are typically regional, potentially limiting your coverage when away from home.
Getting Personalized Guidance
Understanding medicare and supplemental insurance in general terms provides a foundation, but your specific situation requires personalized analysis. Your health history, budget, healthcare preferences, and future plans all factor into determining the best coverage approach.
For local support, you can reach out directly at 336-862-1763 or via email at moserinsurancegroup@gmail.com. Having someone explain your options in plain language, without pressure or confusing jargon, makes the entire process more manageable.
The website moserinsurancegroup.com offers additional resources for those beginning their Medicare journey or reconsidering their current coverage. Taking time to understand your options before enrolling helps ensure you make confident decisions that serve your long-term healthcare and financial needs.
Making Your Decision
Ultimately, choosing between medicare and supplemental insurance options involves balancing multiple factors:
- Coverage comprehensiveness: How much protection do you want against out-of-pocket costs?
- Premium affordability: What monthly payment fits comfortably in your budget?
- Provider flexibility: How important is the ability to see any Medicare-accepting doctor?
- Predictability: Do you prefer stable, predictable costs or variable expenses based on usage?
- Health status: Are you generally healthy or do you have conditions requiring frequent care?
There's no universal "best" answer because individual circumstances vary widely. The right choice for your neighbor might not be right for you, which is why personalized guidance from knowledgeable professionals makes such a difference.
Resources for Ongoing Education
Medicare rules change periodically, new supplemental insurance options emerge, and your own health and financial situation evolves. Staying informed helps you make adjustments when necessary and ensures you're maximizing your coverage value.
Government resources, including Medicare.gov, provide official information about coverage rules and enrollment periods. Independent analyses from organizations like KFF offer data-driven perspectives on market trends and policy implications. State-based SHIP programs provide free counseling to help you navigate local options.
Combining these educational resources with professional guidance creates the strongest foundation for making informed medicare and supplemental insurance decisions that protect both your health and financial security.
Understanding medicare and supplemental insurance requires sorting through numerous plan options, enrollment rules, and cost considerations-but you don't have to navigate this complex landscape alone. Whether you're approaching Medicare eligibility for the first time or reconsidering your current coverage, Moser Insurance Group Inc provides clear guidance and personalized support to help individuals and families in the Triad Area make confident insurance decisions. Contact Moser Insurance Group Inc to explore your medicare and supplemental insurance options with an advisor who prioritizes education over pressure, ensuring you choose coverage that truly fits your needs.
Recent Comments