
Understanding the relationship between medicare and life insurance represents a critical step in comprehensive financial planning for retirement. While these two insurance types often get mentioned together, they serve distinctly different purposes in protecting your health and your family's financial future. Medicare provides essential health coverage for those 65 and older, while life insurance ensures your loved ones receive financial support after you pass away. Throughout the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, families are discovering how to coordinate these coverage types effectively to build complete protection strategies.
Understanding the Core Differences Between Medicare and Life Insurance
Medicare functions as health insurance designed specifically for individuals aged 65 and older, along with certain younger people with disabilities. Medicare does not provide life insurance or death benefits, which surprises many people who assume comprehensive Medicare coverage includes end-of-life financial protection. The program focuses exclusively on medical care, including hospital visits, doctor appointments, prescription drugs, and preventive services.
Life insurance operates on an entirely different principle. These policies provide a death benefit to your designated beneficiaries when you pass away, creating financial security for spouses, children, or other dependents who rely on your income or need funds to cover final expenses.
Key Distinctions That Matter
The fundamental differences between medicare and life insurance extend beyond their basic definitions:
- Purpose: Medicare covers healthcare costs during your lifetime, while life insurance provides financial protection after death
- Beneficiaries: Medicare benefits you directly as the policyholder, while life insurance benefits your named survivors
- Cost structure: Medicare premiums support ongoing medical coverage, whereas life insurance premiums secure a future lump-sum payment
- Eligibility requirements: Medicare enrollment typically begins at 65, while life insurance can be purchased at virtually any age
- Coverage duration: Medicare continues as long as you maintain eligibility and pay premiums, while life insurance terms vary based on policy type
Understanding these distinctions helps residents of Greensboro, High Point, Winston Salem, and Kernersville make informed decisions about their insurance portfolios.
Medicare Coverage Options and Their Limitations
Original Medicare consists of Part A (hospital insurance) and Part B (medical insurance), providing foundational coverage for hospital stays, outpatient care, and doctor visits. However, many beneficiaries discover gaps in this coverage that necessitate additional planning. Medigap policies help cover out-of-pocket costs that Original Medicare doesn't pay, including copayments, coinsurance, and deductibles.
Medicare Advantage plans (Part C) offer an alternative to Original Medicare by bundling hospital and medical coverage, often including prescription drug coverage and additional benefits. In 2026, beneficiaries should be aware that insurers are scaling back Medicare Advantage and Part D plans due to financial pressures, affecting available coverage options.
| Medicare Part | What It Covers | What It Doesn't Cover |
|---|---|---|
| Part A | Hospital stays, skilled nursing facility care, hospice, home health | Long-term care, dental, vision, hearing aids |
| Part B | Doctor visits, outpatient care, preventive services | Life insurance, most dental, routine vision exams |
| Part C | All Part A and Part B benefits plus extra coverage | Varies by plan; never includes life insurance |
| Part D | Prescription medications | Over-the-counter drugs (most), life insurance |
What Medicare Does Cover at End of Life
While medicare and life insurance serve different functions, Medicare does provide some end-of-life benefits. The program covers hospice care for terminally ill beneficiaries, including medical equipment, nursing care, and counseling services. However, this coverage addresses comfort and medical needs during final months-it doesn't provide cash benefits to surviving family members.
Medicare also covers advance care planning discussions with your doctor, allowing you to establish living wills and healthcare directives without cost. These services help ensure your medical wishes are honored but don't replace the financial security life insurance provides.
For those exploring differences in Medicare plans, understanding these coverage limitations clarifies why separate life insurance remains essential for comprehensive family protection.
Life Insurance Options for Medicare Beneficiaries
Obtaining life insurance becomes more challenging as you age, but Medicare beneficiaries still have several viable options. The connection between medicare and life insurance lies in coordinating coverage to address both current healthcare needs and future family financial security.
Term Life Insurance for Seniors
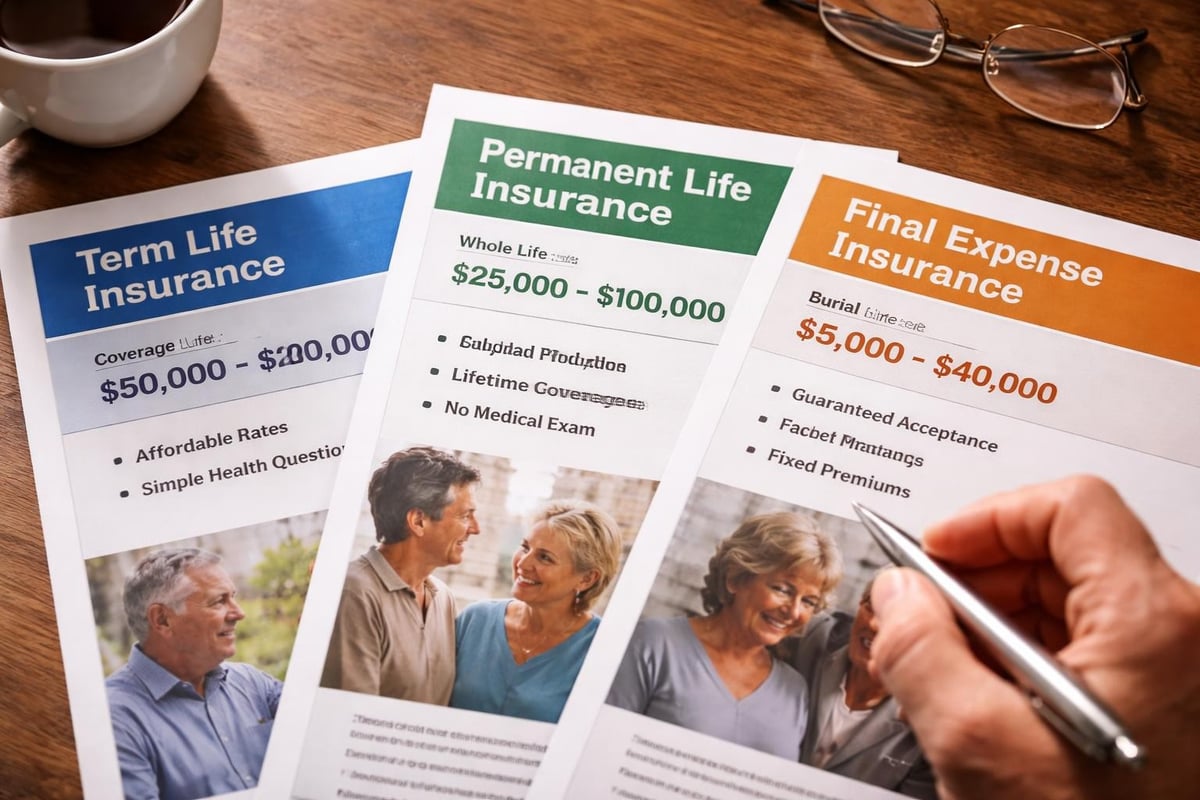
Term life insurance provides coverage for a specific period, typically 10, 15, or 20 years. While premiums increase significantly for older applicants, term policies offer straightforward death benefit protection without cash value accumulation. Some insurers offer term policies to applicants up to age 80, though medical underwriting becomes more stringent.
Residents of the Triad Area seeking term coverage should compare multiple carriers, as pricing varies considerably based on health status, coverage amount, and policy length.
Permanent Life Insurance Solutions
Permanent life insurance policies-including whole life, universal life, and guaranteed universal life-provide lifelong coverage as long as premiums are paid. These policies build cash value over time, which policyholders can access through loans or withdrawals.
For Medicare beneficiaries concerned about legacy planning, permanent policies offer several advantages:
- Guaranteed death benefit regardless of when death occurs
- Fixed premiums that don't increase with age (for whole life)
- Cash value accumulation that can supplement retirement income
- Estate planning benefits for heirs and charitable giving
Those interested in learning more about available options can review information about top life insurance companies to compare rates and coverage features.
Final Expense and Burial Insurance
Final expense insurance, sometimes called burial insurance, specifically targets the costs associated with death-funeral services, cremation or burial, outstanding medical bills, and other immediate expenses. These policies typically offer coverage amounts between $5,000 and $25,000, with simplified underwriting that makes qualification easier for seniors with health issues.
The relationship between medicare and life insurance becomes particularly clear with final expense coverage. While Medicare covers hospice care during your final days, it doesn't pay for funeral costs, cemetery plots, or memorial services. Burial insurance for seniors fills this specific gap, preventing families from facing sudden financial burdens during grief.
Strategic Considerations for Coordinating Coverage
Effectively managing medicare and life insurance requires strategic thinking about your overall financial picture. Many beneficiaries in Winston Salem, Greensboro, High Point, and Kernersville discover that their insurance needs evolve as they transition into retirement.
Assessing Your Life Insurance Needs During Medicare Years
Calculate your life insurance needs by considering several factors:
- Outstanding debts: Mortgages, car loans, or credit card balances that would burden survivors
- Income replacement: Funds your spouse needs to maintain their lifestyle without your Social Security or pension income
- Final expenses: Funeral costs averaging $7,000-$12,000 in North Carolina
- Legacy goals: Money you want to leave children, grandchildren, or charitable organizations
- Estate taxes: Federal or state tax obligations your estate might face
Many retirees overestimate how much life insurance they need, while others underestimate their spouse's future financial requirements. Working with an independent insurance professional helps clarify these calculations.
Timing Your Applications Strategically
The intersection of medicare and life insurance creates important timing considerations. Many people wait until after enrolling in Medicare to purchase life insurance, missing opportunities for better rates available when they're younger and healthier.
Consider these timing strategies:
- Apply for life insurance before Medicare eligibility if you're in good health
- Purchase coverage during Medicare Open Enrollment when you're already reviewing insurance needs
- Lock in rates early if you anticipate health declines
- Reassess coverage needs annually alongside your Medicare plan review
Premium Payment Management
Coordinating premium payments for medicare and life insurance prevents lapses in coverage that could prove costly. Set up automatic payments for both Medicare Part B premiums and life insurance policies to ensure continuous protection.
| Payment Strategy | Medicare Premiums | Life Insurance Premiums |
|---|---|---|
| Automatic deduction | From Social Security benefits | From bank account monthly |
| Annual payment | Not available for Part B | Often includes discount |
| Quarterly payment | Available upon request | Sometimes available |
| Premium assistance | Medicare Savings Programs for qualified individuals | None available |
Common Misconceptions About Medicare and Life Insurance
Misunderstandings about medicare and life insurance lead many people to make coverage mistakes that affect their families. Clarifying these misconceptions supports better decision-making across the Triad Area and beyond.
Myth: Medicare Includes Life Insurance Benefits
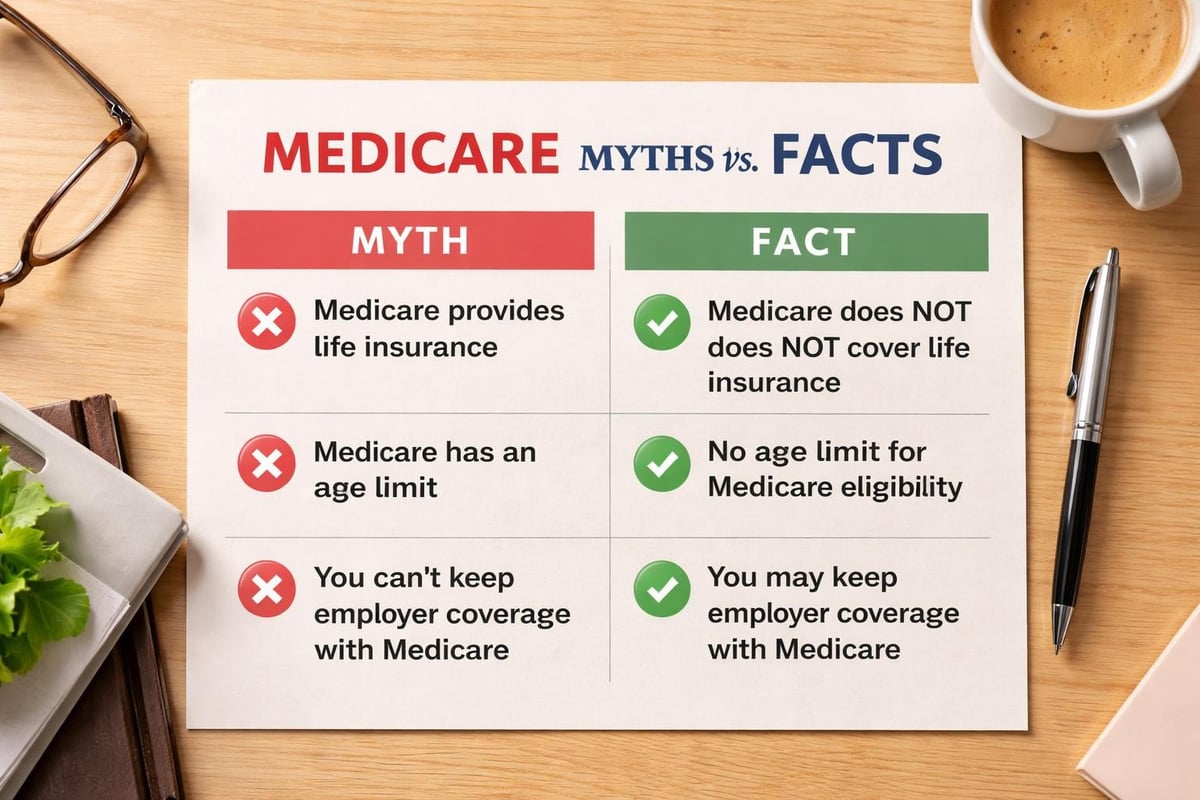
Medicare does not offer life insurance despite being comprehensive health coverage. This misconception stems from confusion about Medicare's hospice benefits, which support end-of-life medical care but provide no cash payments to survivors. Families expecting Medicare to cover funeral expenses or provide survivor income face unfortunate surprises without separate life insurance.
Myth: You Can't Get Life Insurance After 65
While life insurance becomes more expensive and potentially harder to obtain after 65, it's far from impossible. Many carriers specialize in senior life insurance with guaranteed issue policies that require no medical exam. These policies typically feature graded death benefits, meaning full coverage doesn't activate until two or three years after purchase, but they provide options when traditional underwriting presents obstacles.
Myth: Employer Coverage Continues After Medicare Enrollment
Many workers assume their employer-provided life insurance continues seamlessly alongside Medicare coverage. In reality, most group life insurance policies reduce benefits significantly at retirement or age 65, sometimes dropping from multiple times your salary to a flat $10,000 or $25,000. This reduction creates gaps precisely when many people stop thinking about life insurance needs.
Working with Independent Insurance Professionals
Navigating medicare and life insurance decisions becomes significantly easier with expert guidance. Independent insurance agents offer distinct advantages over captive agents who represent single companies.
Benefits of Independent Representation
Independent agents access multiple insurance carriers, comparing policies to find optimal matches for your specific situation. This approach proves especially valuable for Medicare beneficiaries seeking life insurance, as health conditions and age factors create varying responses from different insurers. Independent life insurance agents shop your application to multiple companies simultaneously, identifying the best rates and terms.
In Greensboro, Winston Salem, High Point, and Kernersville, working with local professionals who understand North Carolina's insurance landscape provides additional advantages. They know which carriers offer competitive rates in the region and which underwriters take favorable views of specific health conditions common among Medicare beneficiaries.
Questions to Ask Your Insurance Advisor
When consulting about medicare and life insurance coordination, prepare these questions:
- How much life insurance do I realistically need given my Medicare coverage and retirement income?
- Which type of life insurance makes most sense for someone my age with my health profile?
- Can I qualify for coverage without a medical exam, and what would that cost compared to fully underwritten policies?
- How do my current Medicare Supplement or Medicare Advantage benefits affect my overall insurance needs?
- What happens to my life insurance if I need long-term care in the future?
Professional guidance helps identify solutions that align your healthcare coverage with family protection goals, creating integrated insurance strategies rather than disconnected policies.
Medicare Supplement Plans and Life Insurance Coordination
For those with Medicare Supplement plans, understanding how these policies work alongside life insurance creates comprehensive coverage. Medigap policies reduce out-of-pocket healthcare costs, potentially freeing up budget for life insurance premiums that protect your family's future.
How Medigap Affects Your Insurance Budget
Medicare Supplement plans standardize across lettered plans (Plan A through Plan N), with each offering specific coverage benefits. Higher-coverage plans like Plan F or Plan G carry larger premiums but minimize surprise medical bills. This predictability helps budget for life insurance premiums without worrying about unexpected healthcare costs depleting savings.
Conversely, choosing a lower-premium Medigap plan or Medicare Advantage option might free up funds for higher life insurance coverage amounts. This trade-off requires careful analysis of your health status, risk tolerance, and family protection priorities.
Medicare Advantage Plans and Life Insurance Considerations
Medicare Advantage plans bundle coverage differently than Original Medicare with Medigap, affecting how you think about medicare and life insurance coordination. Many Medicare Advantage plans include extra benefits like dental, vision, and hearing coverage, potentially reducing out-of-pocket spending and creating room in your budget for life insurance.
Impact of Medicare Advantage Networks
Medicare Advantage plans typically use network restrictions, requiring you to see specific doctors and use particular hospitals except in emergencies. This limitation doesn't directly affect life insurance but influences your overall financial planning. If network restrictions lead to unexpected out-of-network costs, you might face bills that deplete savings you'd otherwise use to maintain life insurance coverage.
Similarly, understanding Medicare Advantage out-of-pocket maximums helps determine how much emergency fund you need, which in turn affects how much life insurance you should carry to ensure family financial security.
Life Insurance During Medicare Open Enrollment
The annual Medicare Open Enrollment period from October 15 to December 7 presents an ideal opportunity to review all insurance coverage, including the relationship between medicare and life insurance. During this window, you can change Medicare Advantage plans, switch to Original Medicare plus Medigap, or modify Part D prescription coverage.
Comprehensive Insurance Review Strategy
Use Open Enrollment to conduct a complete insurance audit:
- Review Medicare coverage changes for the upcoming year, including premium adjustments and benefit modifications
- Assess prescription drug needs under current Part D plans versus alternatives
- Evaluate life insurance adequacy based on changed circumstances, new debts, or family situations
- Compare premium costs across all insurance types to optimize your budget
- Update beneficiaries on both Medicare and life insurance policies to reflect current wishes
This holistic approach ensures your healthcare coverage and family financial protection work together effectively rather than competing for limited premium dollars.
Special Considerations for Specific Situations
Certain circumstances create unique intersections between medicare and life insurance that deserve careful attention. Families throughout the Triad Area face these situations regularly, requiring customized solutions.
Supporting a Spouse with Different Medicare Status
When spouses have different Medicare eligibility dates-due to age gaps or disability status-life insurance needs become more complex. The younger spouse might still work and carry employer coverage while the older spouse transitions to Medicare. This period requires careful coordination to ensure continuous protection for both individuals.
Consider maintaining higher life insurance coverage on the younger, working spouse since that person's death would eliminate both income and employer health benefits. Meanwhile, the Medicare-enrolled spouse might carry a smaller final expense policy adequate for burial costs and immediate bills.
Managing Chronic Conditions Under Medicare
Medicare beneficiaries with chronic conditions like diabetes, heart disease, or COPD face higher life insurance premiums but still have coverage options. Some insurers specialize in "impaired risk" underwriting, offering competitive rates for applicants with specific health issues when those conditions are well-managed.
Your Medicare claims history doesn't directly affect life insurance applications-insurers conduct separate medical underwriting. However, demonstrating good health management through Medicare Advantage wellness programs or Medicare Supplement preventive care can provide evidence of responsible health practices that some underwriters view favorably.
Contact Information and Local Resources
For personalized guidance on coordinating medicare and life insurance coverage in North Carolina, Moser Insurance Group Inc serves clients throughout the Triad Area with individualized support. Reach us at 336-862-1763 or email moserinsurancegroup@gmail.com to discuss your specific situation. Our website moserinsurancegroup.com provides additional resources and information about coverage options.
We help residents of Greensboro, Winston Salem, High Point, and Kernersville understand their insurance choices without pressure, focusing on education that empowers confident decision-making. Whether you're approaching Medicare eligibility or reassessing your current coverage, local expertise makes the process clearer and more effective.
Understanding medicare and life insurance as complementary but distinct forms of protection enables better planning for your healthcare needs and your family's financial future. These coverage types work together to create comprehensive security-Medicare addresses medical costs during your lifetime, while life insurance provides for loved ones after you're gone. Moser Insurance Group Inc helps individuals and families throughout the Triad Area navigate these decisions with clear explanations and personalized support. Contact us at 336-862-1763 to explore how coordinating your Medicare and life insurance coverage creates the protection strategy your family deserves.
Recent Comments