

Navigating the world of medical insurance can feel overwhelming, especially when you're trying to understand the different coverage options available in 2026. Whether you're approaching retirement age, helping a family member explore their options, or simply seeking better coverage, understanding medical insurance fundamentals is essential for making informed decisions. For residents in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, having access to knowledgeable guidance makes all the difference when evaluating your healthcare coverage needs.
Understanding Medical Insurance Fundamentals
Medical insurance serves as a financial protection mechanism that helps individuals and families manage healthcare costs. Rather than paying the full price for doctor visits, hospital stays, prescriptions, and preventive care, policyholders pay premiums in exchange for coverage that reduces out-of-pocket expenses.
The structure of medical insurance typically includes several key components:
- Premiums: The monthly amount you pay to maintain coverage
- Deductibles: The amount you pay before insurance begins covering costs
- Copayments: Fixed amounts paid for specific services
- Coinsurance: The percentage of costs you share with your insurer after meeting your deductible
- Out-of-pocket maximums: The yearly limit on what you'll pay for covered services
According to data from the U.S. Census Bureau, millions of Americans rely on various forms of medical insurance to access healthcare services. Understanding these basic elements helps you compare plans effectively and choose coverage that aligns with your healthcare needs and budget.
Types of Medical Insurance Coverage
Medical insurance comes in multiple forms, each designed to serve different populations and needs. Employer-sponsored plans remain the most common type of coverage for working-age Americans, offering group rates and often including employer contributions toward premiums.
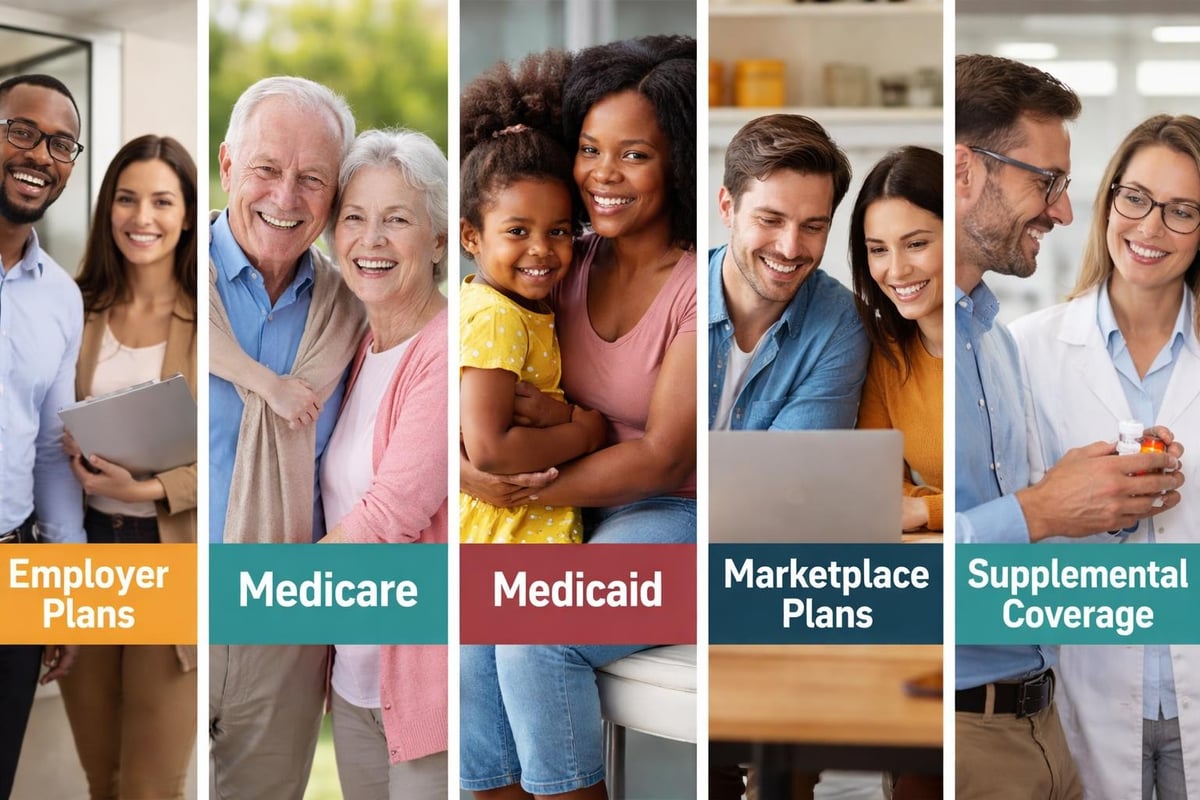
Individual marketplace plans, available through Health Insurance Marketplaces overseen by CCIIO, provide coverage for those who don't have access to employer plans. These plans must meet Affordable Care Act standards and offer essential health benefits.
Medicare represents a crucial category for individuals aged 65 and older, as well as younger people with certain disabilities. If you're turning 65 in Kernersville or surrounding areas, understanding Medicare becomes particularly important. This federal program includes:
- Part A: Hospital insurance coverage
- Part B: Medical insurance for doctor visits and outpatient care
- Part C: Medicare Advantage plans offered by private insurers
- Part D: Prescription drug coverage
For personalized guidance on Medicare insurance for seniors, working with an experienced agent helps clarify which options best match your specific health needs and budget.
Evaluating Medical Insurance Plan Options
Choosing the right medical insurance plan requires careful consideration of multiple factors. Network restrictions, coverage breadth, and cost-sharing structures vary significantly between plans, making comparison essential.
Network Considerations and Provider Access
Medical insurance plans typically organize healthcare providers into networks. Understanding these network structures directly impacts your access to doctors and hospitals:
| Network Type | Provider Freedom | Cost Structure | Best For |
|---|---|---|---|
| HMO | Primary care physician required; referrals needed | Lower premiums, lower out-of-pocket | Those wanting coordinated care |
| PPO | Any provider; no referrals | Higher premiums, moderate out-of-pocket | Those wanting flexibility |
| EPO | Network only; no referrals | Moderate premiums | Balance of cost and choice |
| POS | PCP required; some out-of-network | Variable costs | Mixed needs |
HMO plans offer structured care coordination through a primary care physician who manages referrals to specialists. While this approach limits spontaneous specialist access, it often results in lower overall costs and better care coordination.
If you frequently travel or want the flexibility to see specialists without referrals, PPO plans provide broader access but typically come with higher premiums. For residents of Greensboro, High Point, Winston Salem, and Kernersville, evaluating local provider networks ensures your preferred doctors participate in your chosen plan.
Prescription Drug Coverage Analysis
Prescription medication costs represent a significant healthcare expense for many individuals. Medical insurance plans vary considerably in their pharmacy benefits, making this a critical comparison point.
Medicare beneficiaries should pay particular attention to Medicare Part D prescription plans, which provide coverage for medications. These standalone plans supplement Original Medicare and help manage prescription costs.
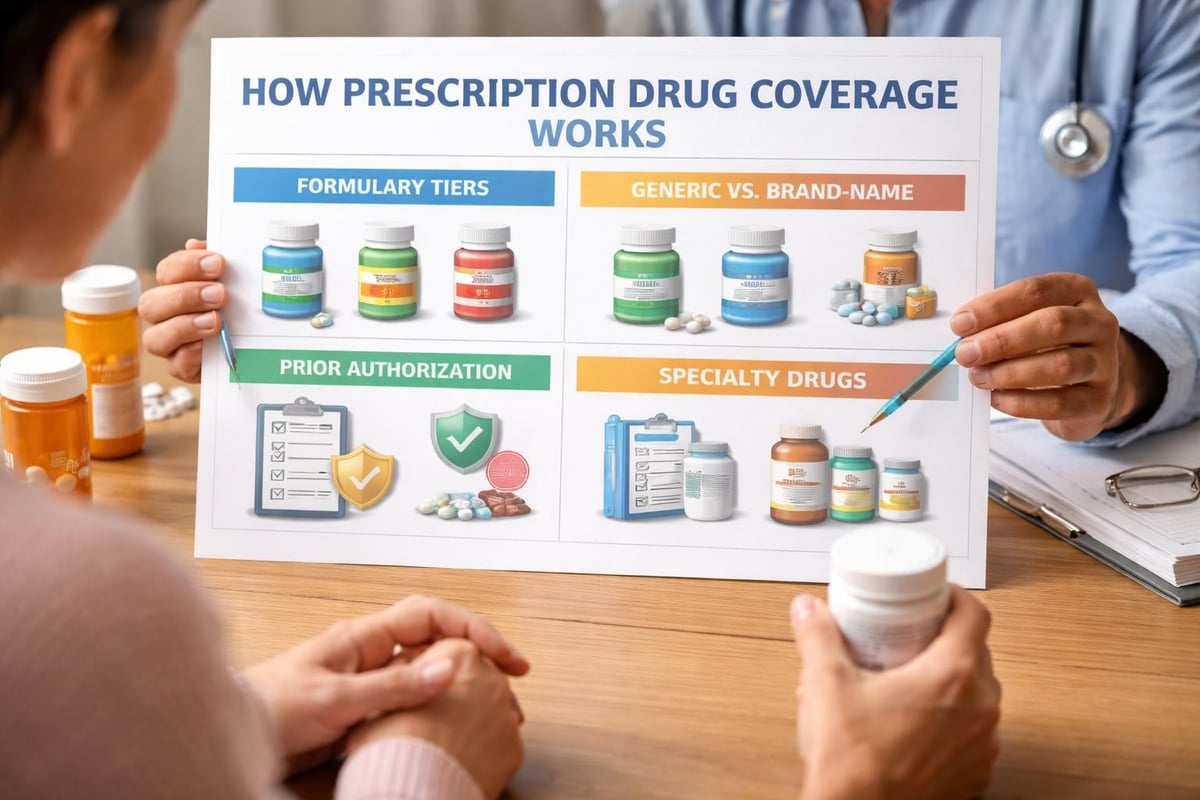
Key prescription coverage elements include:
- Formularies (lists of covered medications)
- Tier structures that determine copayment amounts
- Prior authorization requirements for certain drugs
- Mail-order pharmacy options for maintenance medications
- Coverage gaps and out-of-pocket thresholds
Understanding the Medicare Part D coverage gap, often called the "donut hole," helps Medicare beneficiaries plan for potential out-of-pocket costs during the year. Changes to this coverage gap in recent years have reduced the financial burden for many seniors.
Medical Insurance Costs and Value Assessment
Understanding the true cost of medical insurance extends beyond monthly premiums. A comprehensive cost analysis considers all potential expenses and weighs them against the value of coverage received.
Premium Versus Out-of-Pocket Balance
The relationship between premiums and out-of-pocket costs creates a fundamental trade-off in medical insurance selection. Plans with lower monthly premiums typically feature higher deductibles and coinsurance percentages, while higher-premium plans often provide more generous cost-sharing.
For individuals with predictable healthcare needs, running cost projections helps identify the optimal balance:
- Calculate annual premiums for each plan option
- Estimate expected healthcare utilization (doctor visits, prescriptions, procedures)
- Add projected deductibles, copayments, and coinsurance
- Compare total estimated annual costs across plans
- Consider the out-of-pocket maximum as worst-case scenario protection
This analytical approach, supported by research from AHRQ on health insurance, helps you make evidence-based decisions rather than selecting solely based on monthly premium affordability.
Working with knowledgeable insurance agents for health insurance provides valuable perspective during this evaluation process. Experienced agents understand how different medical conditions and medication needs interact with plan structures.
Supplemental Coverage Considerations
Medical insurance gaps can leave policyholders exposed to significant costs. Supplemental coverage options help fill these gaps and provide additional financial protection.
Medicare Supplement Insurance, also known as Medigap, works alongside Original Medicare to cover costs that Medicare Parts A and B don't fully pay. Understanding Medicare supplemental policy options becomes crucial for those who want comprehensive coverage without the network restrictions of Medicare Advantage plans.
The standardized Medigap plans offer different levels of coverage:
| Plan Type | Part A Coinsurance | Part B Coinsurance | Part B Excess Charges | Foreign Travel Emergency |
|---|---|---|---|---|
| Plan G | Yes | Yes | No | Yes |
| Plan N | Yes | Partial | No | Yes |
| Plan F* | Yes | Yes | Yes | Yes |
*Only available to those eligible for Medicare before 2020
For comprehensive protection, some individuals combine medical insurance with health and life insurance coverage, ensuring both healthcare costs and family financial security receive attention.
Enrollment Periods and Timing Considerations
Medical insurance enrollment follows specific timeframes that determine when you can obtain or change coverage. Missing these windows can result in coverage gaps or limited options.
Annual Enrollment Opportunities
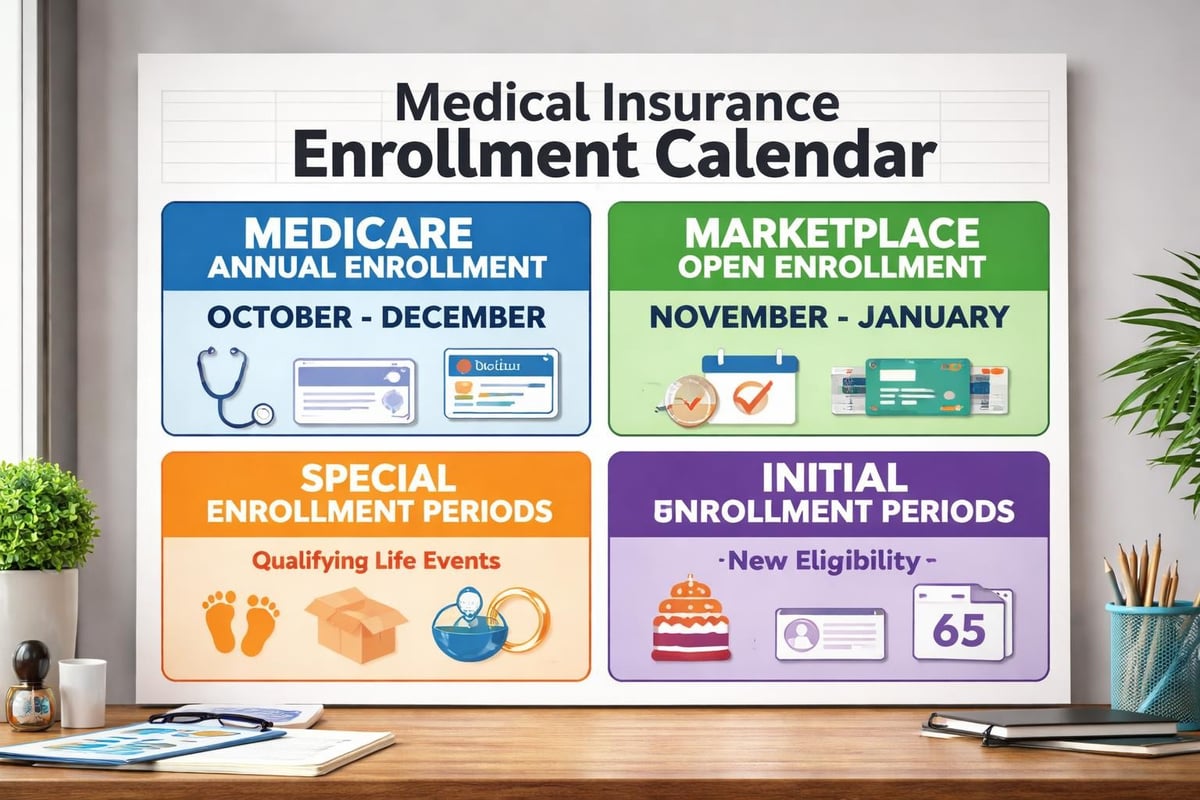
The Annual Enrollment Period (AEP) for Medicare runs from October 15 through December 7 each year. During this window, Medicare beneficiaries can:
- Switch from Original Medicare to Medicare Advantage or vice versa
- Change Medicare Advantage plans
- Add, drop, or switch Medicare Part D prescription drug coverage
- Add or drop Medicare supplemental coverage in some circumstances
For marketplace plans, the Open Enrollment Period typically runs from November 1 through January 15, though dates can vary slightly by state. Taking advantage of these enrollment windows ensures you can adjust coverage as your healthcare needs evolve.
Special Enrollment Triggers
Certain life events create Special Enrollment Periods that allow coverage changes outside the standard enrollment windows:
- Loss of existing health coverage
- Marriage, divorce, or legal separation
- Birth or adoption of a child
- Permanent relocation to a new service area
- Changes in income affecting subsidy eligibility
- Gaining citizenship or lawful presence
Understanding these triggers helps you respond appropriately when circumstances change. For instance, if you're relocating to the Triad Area from another region, this move may qualify you for a Special Enrollment Period to select new coverage with local provider networks.
Comparing Medical Insurance Plans Strategically
Effective plan comparison requires a systematic approach that considers your unique healthcare situation. Rather than focusing exclusively on premium costs, comprehensive evaluation examines total value.
Creating Your Personal Healthcare Profile
Before comparing medical insurance options, document your healthcare needs and preferences:
Current Healthcare Utilization:
- Frequency of doctor visits
- Specialist care requirements
- Ongoing prescriptions and monthly costs
- Anticipated procedures or treatments
- Preferred hospitals and physicians
Financial Considerations:
- Available budget for monthly premiums
- Ability to handle higher out-of-pocket costs
- Health Savings Account (HSA) eligibility and interest
- Tax implications of different plan structures
Lifestyle Factors:
- Travel frequency and duration
- Location flexibility needs
- Importance of specific providers
- Preference for care coordination versus flexibility
This profile serves as your foundation for evaluating whether a plan truly meets your needs. For detailed guidance, requesting a health insurance quotation from a knowledgeable broker provides personalized comparisons based on your specific situation.
Working with Insurance Professionals
The complexity of medical insurance makes professional guidance valuable, particularly when navigating Medicare options or comparing multiple plan types. Regulations from the National Association of Insurance Commissioners ensure licensed agents meet professional standards and provide ethical guidance.
A qualified health plan broker offers several advantages:
- Access to multiple insurance carriers and plan options
- Expertise in plan features, networks, and cost structures
- Assistance with enrollment and paperwork
- Ongoing support for claims issues or coverage questions
- Annual review opportunities to ensure continued plan suitability
For those exploring top Medicare Advantage plans in the Triad Area, local expertise proves particularly valuable. Agents familiar with provider networks in Greensboro, Kernersville, High Point, and Winston Salem can confirm your preferred doctors participate in plans under consideration.
Medicare Medical Insurance Considerations
Medicare represents a specialized category of medical insurance that serves approximately 65 million Americans. Understanding Medicare's structure helps ensure you maximize benefits while minimizing costs.
Coordinating Medicare Parts
Medicare A and B coverage forms the foundation of Original Medicare, but these parts don't cover everything. Part A handles hospital stays, skilled nursing facility care, hospice, and some home health services. Part B covers doctor visits, outpatient care, preventive services, and durable medical equipment.
Important gaps in Original Medicare include:
- Most prescription drug costs
- Dental care
- Vision care (except for certain conditions)
- Hearing aids
- Long-term care
Understanding Social Security and Medicare coordination helps you time enrollment correctly and avoid late enrollment penalties. If you're already receiving Social Security benefits when you turn 65, you'll automatically enroll in Medicare Parts A and B.
Medicare Advantage Versus Original Medicare Plus Supplements
Choosing between Medicare Advantage and Original Medicare with supplemental coverage represents one of the most significant medical insurance decisions for those over 65.
| Feature | Medicare Advantage | Original Medicare + Supplement |
|---|---|---|
| Monthly Costs | Often $0-$50 beyond Part B premium | Part B premium + supplement premium |
| Provider Networks | Usually restricted to network | Any Medicare-accepting provider |
| Extra Benefits | Often includes dental, vision, hearing | Generally not included |
| Prescription Coverage | Usually integrated | Requires separate Part D plan |
| Out-of-Pocket Maximum | Yes, federally mandated | No limit unless supplement covers |
| Travel Coverage | May be limited | Generally works nationwide |
For comprehensive information about Medicare health care plans, working with specialists who focus on Medicare helps you understand the nuances of each approach and how they align with your specific needs.
Many beneficiaries appreciate Medicare Advantage plans for their integrated approach and extra benefits like Medicare and dental coverage. Others prefer the flexibility of Original Medicare combined with a supplement policy.
Maximizing Medical Insurance Benefits
Once you've selected medical insurance coverage, understanding how to maximize your benefits ensures you receive full value from your plan.
Preventive Care Utilization
Most medical insurance plans, including Medicare, cover preventive services at no cost when you use in-network providers. Taking advantage of these benefits supports your health while avoiding unnecessary expenses:
- Annual wellness visits and health risk assessments
- Screening tests for various cancers and chronic conditions
- Vaccinations and immunizations
- Counseling services for tobacco cessation, obesity, and alcohol misuse
- Cardiovascular disease and diabetes screening
These preventive services help identify health issues early when they're most treatable, potentially avoiding more expensive interventions later.
Understanding Prior Authorization Processes
Some medical insurance plans require prior authorization before covering certain services, procedures, or medications. Understanding this process prevents unexpected denials and billing issues:
- Check requirements: Review your plan documents or call member services to confirm which services need authorization
- Allow adequate time: Submit authorization requests well before scheduled procedures
- Provide complete information: Include all necessary medical records and physician recommendations
- Follow up: Confirm authorization approval before receiving services
- Document everything: Keep records of authorization numbers and approval dates
Working with your healthcare providers' offices, who handle many authorization requests routinely, streamlines this process. Most medical offices have dedicated staff who manage insurance requirements.
Managing Claims and Appeals
Despite careful planning, claim denials occasionally occur. Understanding your appeal rights protects your interests:
Common denial reasons include:
- Services deemed not medically necessary
- Out-of-network provider usage without authorization
- Incomplete or incorrect claim information
- Coverage exclusions or limitations
- Pre-existing condition clauses (for grandfathered plans)
Most medical insurance plans have structured appeal processes with specific timeframes. Acting promptly when you receive a denial increases your chances of successful resolution. For complex situations, working with Medicare Advantage insurance agents provides advocacy and expertise in navigating the appeals process.
Understanding medical insurance options, from enrollment periods to coverage structures, empowers you to make informed decisions about your healthcare protection. Whether you're exploring Medicare coverage, comparing marketplace plans, or evaluating supplemental options, having clear guidance makes the process manageable. For personalized assistance navigating medical insurance choices in Greensboro, Kernersville, High Point, Winston Salem, and throughout the Triad Area, contact Moser Insurance Group Inc at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your specific needs and receive expert recommendations tailored to your situation.
Recent Comments