
Choosing the right Medicare coverage can feel overwhelming, especially when you're trying to understand how different insurance companies and their Medicare Supplement plans compare. Manhattan Life has been offering Medicare Supplement insurance for decades, serving beneficiaries across North Carolina and throughout the United States. For residents in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, understanding what a manhattan life medicare supplement offers and how it compares to other carriers can help you make a confident decision about your healthcare coverage. This comprehensive guide examines Manhattan Life's Medicare Supplement offerings, their pricing structure, benefits, and whether they might be the right fit for your healthcare needs.
Understanding Manhattan Life as a Medicare Supplement Carrier
Manhattan Life Insurance Company, also known as ManhattanLife, operates as a specialized insurance carrier focusing primarily on Medicare-related products. The company has established itself in the Medicare Supplement market by offering standardized Medigap plans that help fill the coverage gaps left by Original Medicare.
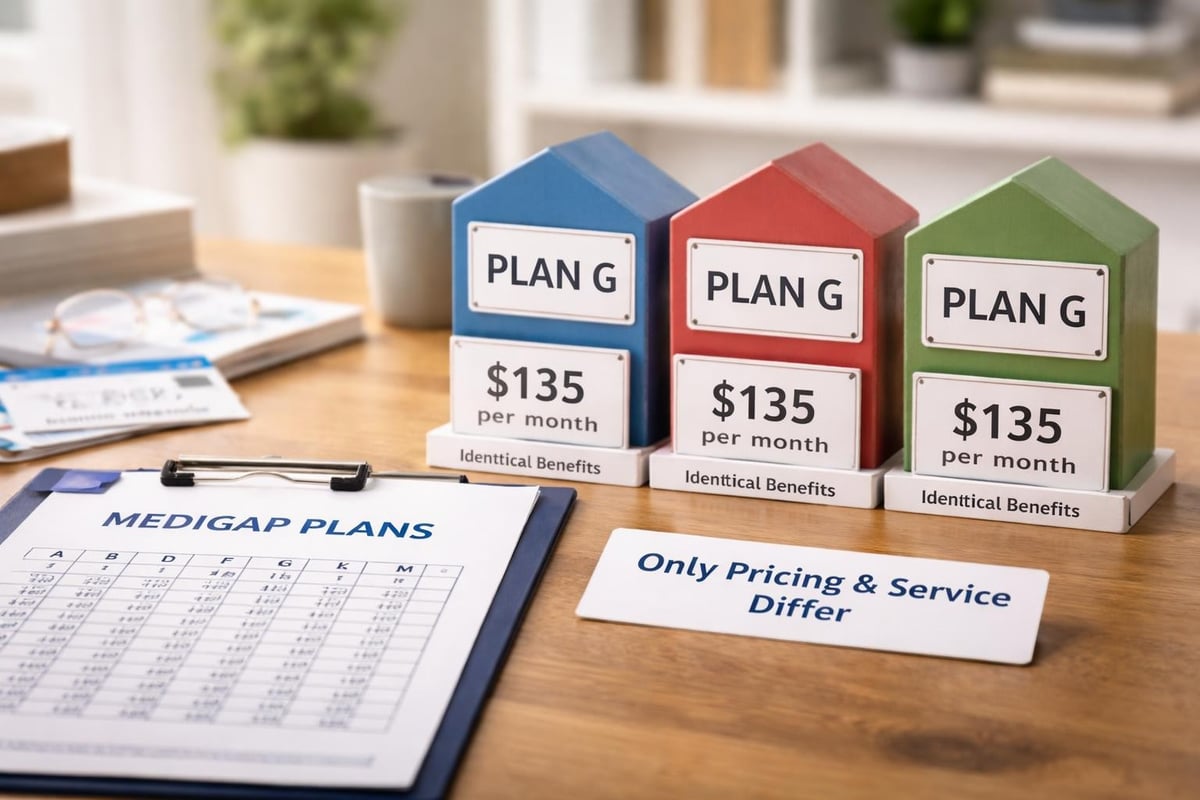
When evaluating a manhattan life medicare supplement policy, it's essential to understand that the company itself doesn't create unique plan designs. Like all Medicare Supplement carriers, Manhattan Life offers standardized Medigap plans that are regulated by federal and state governments. This standardization means a Plan G from Manhattan Life provides the same core benefits as a Plan G from any other carrier.
Company Background and Reputation
Manhattan Life has been in the insurance business since 1850, giving them more than 175 years of experience. This longevity provides some assurance of financial stability and operational expertise. The company specializes in supplemental health insurance products, with Medicare Supplement plans forming a significant portion of their business model.
Customer reviews and satisfaction ratings offer valuable insight into any insurance carrier's performance. According to customer feedback on Trustpilot, experiences with Manhattan Life vary, as they do with most insurance companies. Some policyholders appreciate their straightforward claims process and customer service, while others have reported challenges with premium increases or service responsiveness.
Available Manhattan Life Medicare Supplement Plans
A manhattan life medicare supplement is available in several standardized plan options. As of 2026, Manhattan Life typically offers the most popular Medigap plans, though availability may vary by state and region.
Most Common Plan Options
Manhattan Life generally provides these Medicare Supplement plans:
- Plan G: The most popular choice for new Medicare beneficiaries, covering all gaps except the Part B deductible
- Plan N: A cost-effective option with small copays for doctor visits and emergency room visits
- Plan F: Available only to those who became Medicare-eligible before January 1, 2020
- High Deductible Plan G: A lower-premium option with a higher annual deductible
Each of these plans follows the standard Medigap benefit structure established by Medicare regulations. The coverage remains identical regardless of which insurance company you choose, but premiums can differ significantly.
| Plan Type | Monthly Premium Range | Best For | Key Features |
|---|---|---|---|
| Plan G | $125-$185 | Comprehensive coverage seekers | Covers everything except Part B deductible |
| Plan N | $95-$145 | Budget-conscious beneficiaries | Lower premiums with small copays |
| High Deductible Plan G | $40-$65 | Healthy individuals | Lowest premiums, $2,870 deductible in 2026 |
Note: Premium ranges are estimates and vary by location, age, and other factors.
Coverage Comparison
Understanding what your manhattan life medicare supplement covers requires looking at the specific plan letter you select. Plan G, for instance, covers Medicare Part A coinsurance and hospital costs, Part B coinsurance or copayment, blood transfusions, Part A hospice care coinsurance, skilled nursing facility care coinsurance, Part A deductible, and foreign travel emergency care.
Plan N provides similar coverage but requires copayments of up to $20 for office visits and up to $50 for emergency room visits that don't result in admission. These small cost-sharing requirements make Plan N premiums more affordable while still providing substantial coverage.
Pricing Structure and Rate Increases
One of the most critical factors when evaluating a manhattan life medicare supplement is understanding how the company prices its policies and handles rate increases over time. Manhattan Life uses specific pricing methodologies that affect what you pay both initially and in future years.
Community-Rated vs. Attained-Age Pricing
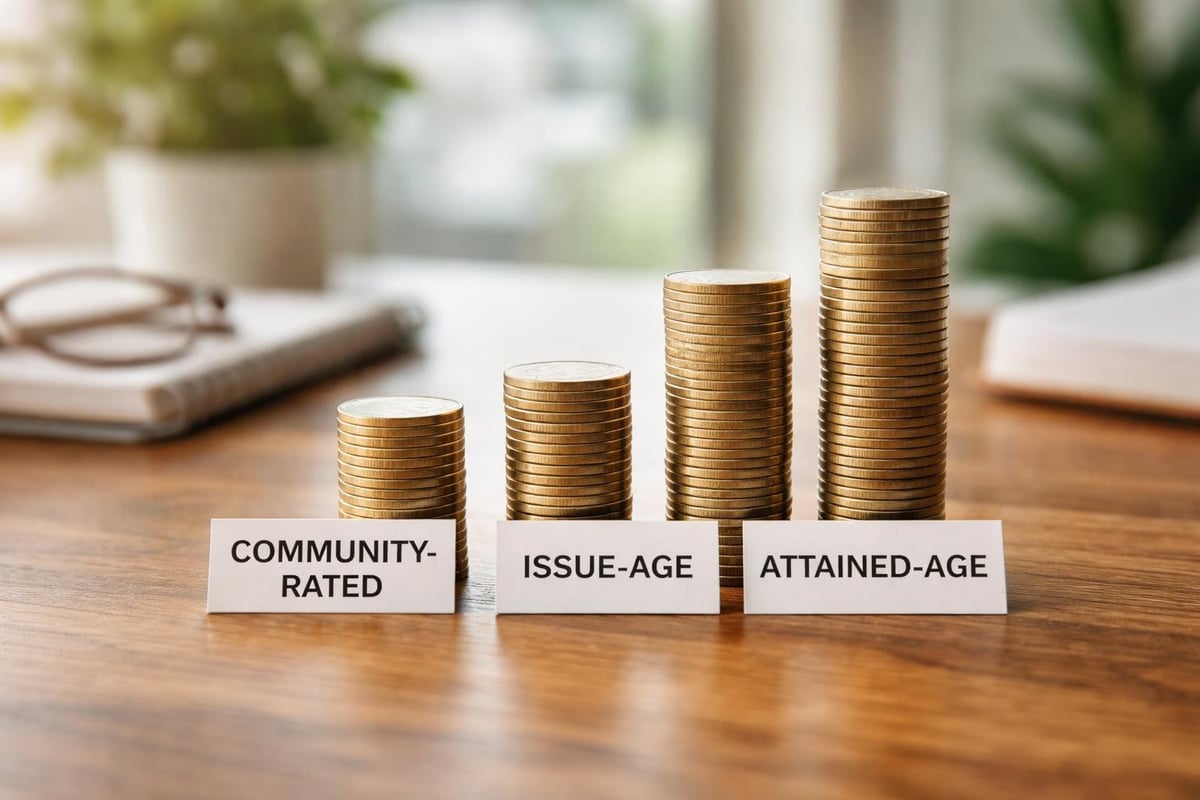
Manhattan Life typically uses attained-age rating for most of their Medicare Supplement plans. This pricing method means your premium increases as you get older, regardless of when you first purchased the policy. While this approach often results in lower initial premiums for younger beneficiaries, costs typically rise more substantially over time compared to community-rated policies.
Some key considerations about Manhattan Life's pricing include:
- Initial premiums may be competitive for those newly eligible for Medicare
- Annual rate increases typically occur due to both aging and general inflation
- Geographic location significantly impacts premium costs
- Household discounts may be available when multiple people in the same home have policies
The projected Medicare costs for 2026 continue to rise, making it important to factor in not just current premiums but likely future increases when selecting a carrier.
Discount Opportunities
Manhattan Life offers household discounts that can reduce premiums for policyholders. When two individuals living at the same address both have Manhattan Life Medicare Supplement policies, they may qualify for discounted rates. This benefit can provide meaningful savings for married couples or others sharing a household.
According to The Senior List’s review, these household discounts typically range from 5% to 12%, depending on the state and specific plan selected. It's worth asking about all available discounts when obtaining quotes.
Enrollment Requirements and Eligibility
Enrolling in a manhattan life medicare supplement follows the same general rules that apply to all Medigap policies. Understanding these enrollment periods and requirements helps ensure you get the best rates and avoid potential coverage issues.
Medicare Supplement Open Enrollment Period
The optimal time to purchase any Medicare Supplement plan, including those from Manhattan Life, is during your Medigap Open Enrollment Period. This six-month window begins on the first day of the month in which you're both 65 or older and enrolled in Medicare Part B.
During this guaranteed issue period:
- Insurance companies cannot deny you coverage based on health conditions
- They cannot charge you higher premiums due to pre-existing conditions
- You have access to all available plan options
- No medical underwriting is required
If you're approaching Medicare age, planning ahead for this enrollment period is crucial. Missing this window can result in higher premiums or even coverage denial if you have significant health issues.
Special Enrollment Situations
Beyond the initial open enrollment period, certain circumstances create guaranteed issue rights for Medicare Supplement insurance. These situations include losing employer coverage, moving out of a Medicare Advantage plan's service area, or having your current Medigap carrier discontinue coverage.
Manhattan Life, like all Medicare Supplement carriers, must honor these guaranteed issue rights when applicable. Understanding your rights in these situations ensures you maintain continuous coverage without gaps.
Comparing Manhattan Life to Other Carriers in North Carolina
For residents throughout the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, comparing a manhattan life medicare supplement to other available options is essential for finding the best value.
Competitive Positioning
Manhattan Life positions itself in the middle tier of Medicare Supplement carriers in terms of pricing. They're typically not the least expensive option available, but they also don't command premium prices like some larger, more well-known insurance companies.
When comparing carriers in North Carolina, consider these factors:
- Premium competitiveness: How Manhattan Life's rates compare to other carriers for the same plan
- Financial strength ratings: The company's ability to pay claims over the long term
- Customer service quality: Responsiveness and ease of working with the company
- Rate increase history: How aggressively the company has raised rates in recent years
Alternative Carriers to Consider
North Carolina residents have access to numerous Medicare Supplement carriers beyond Manhattan Life. Companies like Blue Cross Blue Shield of North Carolina, United American, Mutual of Omaha, and Aetna all compete in this market. Each carrier has different premium structures, customer service approaches, and rate increase histories.
A comprehensive comparison of Medicare Supplement plans from various carriers can reveal significant premium differences for identical coverage. Since the benefits are standardized, choosing based on price, financial strength, and service quality makes practical sense.
Claims Processing and Customer Service Experience
The daily experience of having a manhattan life medicare supplement extends beyond just premium costs. How the company handles claims, responds to questions, and supports policyholders matters significantly, especially as healthcare needs increase with age.
Claims Submission and Payment
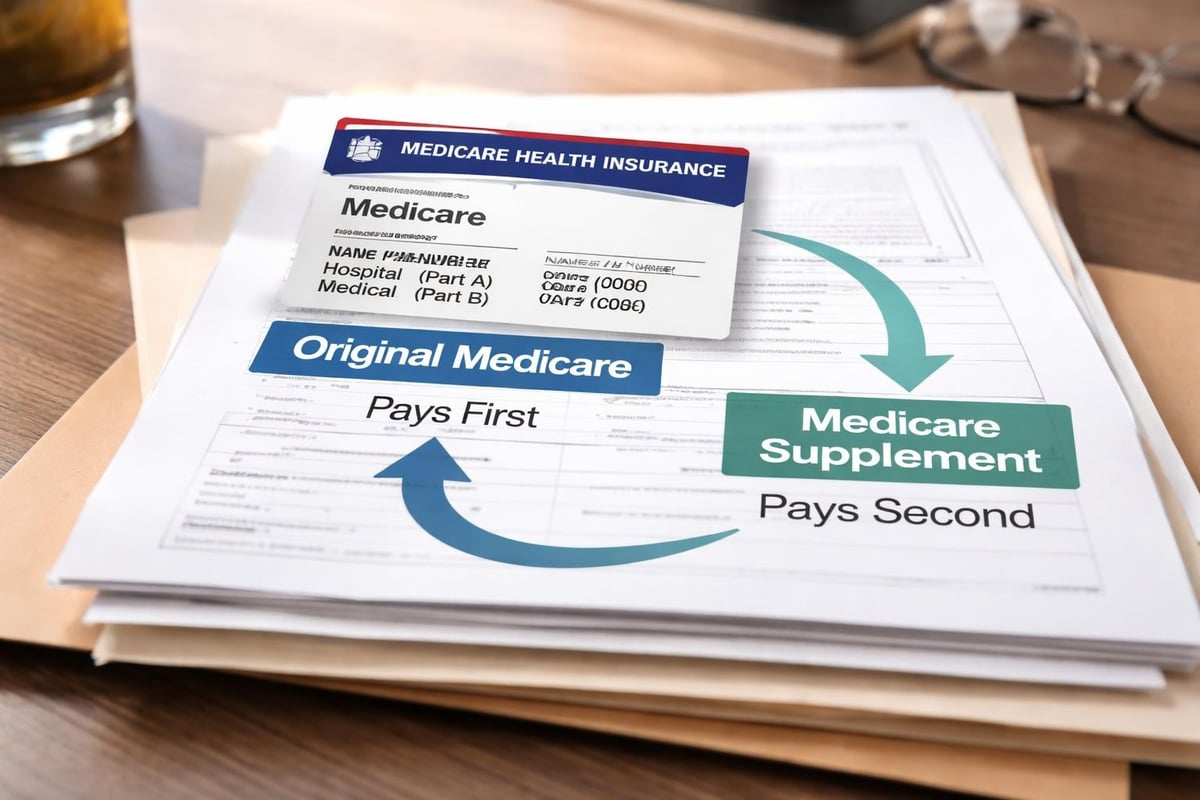
Medicare Supplement insurance operates through a coordination of benefits system. Original Medicare pays first as the primary payer, then your Manhattan Life policy pays the supplemental amounts according to your plan's coverage schedule. In most cases, this happens automatically through Medicare's crossover system, meaning you don't need to submit claims manually.
For services covered by Medicare, the process typically works like this:
- Your healthcare provider submits the claim to Medicare
- Medicare processes the claim and pays its portion
- The claim automatically crosses over to Manhattan Life
- Manhattan Life pays the supplemental amount directly to the provider
- You receive an Explanation of Benefits showing what was paid
This automated system works efficiently for most services, though occasional issues may require policyholder involvement to resolve billing questions.
Customer Service Accessibility
Manhattan Life provides customer service through multiple channels, including phone support, written correspondence, and online account management. The quality and responsiveness of customer service can vary based on individual experiences and the complexity of the issue being addressed.
When evaluating customer service, consider:
- Phone wait times: How long it takes to reach a representative
- Representative knowledge: Whether staff can answer questions accurately
- Issue resolution speed: How quickly problems get solved
- Online tools: Availability of self-service options for account management
Making an Informed Decision About Manhattan Life
Deciding whether a manhattan life medicare supplement is right for you requires careful consideration of multiple factors specific to your situation. The standardization of Medigap plans simplifies comparison in some ways while placing greater emphasis on carrier-specific factors like pricing and service.
Key Decision Factors
Financial Considerations: Compare Manhattan Life's premiums not just for the current year but project potential increases over the next 5-10 years. Attained-age pricing means premiums will rise as you age, so understanding the long-term cost trajectory matters more than just the initial premium.
Company Stability: Review Manhattan Life's financial strength ratings from agencies like A.M. Best or Standard & Poor's. These ratings indicate the company's ability to pay claims and remain solvent over time. A financially strong carrier provides peace of mind that your coverage will be there when you need it.
Local Support: While Manhattan Life operates nationwide, having access to local Medicare insurance guidance in areas like Greensboro, Kernersville, High Point, and Winston Salem can make a significant difference. Working with an independent agent who represents multiple carriers ensures you're comparing Manhattan Life against all available options objectively.
Questions to Ask Before Enrolling
Before purchasing a manhattan life medicare supplement, gather answers to these essential questions:
- What is my current premium, and how has Manhattan Life's pricing changed historically in my area?
- What discounts am I eligible for, including household discounts?
- How does this premium compare to at least three other carriers for the same plan?
- What is Manhattan Life's process for rate increases, and how much notice do they provide?
- Are there any exclusions or limitations specific to my situation?
Taking time to understand Medicare Supplement options thoroughly prevents costly mistakes and ensures you select coverage that meets your needs both now and in the future.
Working with an Independent Insurance Agent
Navigating Medicare Supplement options, including manhattan life medicare supplement plans, becomes significantly easier when working with an experienced independent insurance agent. Unlike captive agents who represent only one company, independent agents can compare multiple carriers to find the best fit for your specific situation.
Benefits of Independent Representation
An independent agent brings several advantages to your Medicare Supplement shopping experience:
Objective Comparison: Independent agents can quote Manhattan Life alongside competitors, providing unbiased recommendations based on your priorities rather than company loyalty.
Ongoing Support: A good agent doesn't just help you enroll and disappear. They remain available to answer questions, help resolve billing issues, and assist with future coverage needs.
Local Expertise: Agents familiar with the North Carolina market understand regional pricing variations and can identify carriers with the most competitive rates in areas like the Triad Area, Greensboro, Kernersville, High Point, and Winston Salem.
No Additional Cost: Medicare Supplement commissions are built into premiums whether you work with an agent or enroll directly. Using an agent's expertise costs nothing extra while providing valuable guidance.
Getting Personalized Assistance
For personalized help comparing Manhattan Life Medicare Supplement plans with other carriers available in North Carolina, contact Moser Insurance Group Inc at 336-862-1763 or email moserinsurancegroup@gmail.com. Our team provides clear, pressure-free guidance to help you understand all your options and make confident insurance decisions.
We also offer Medicare education seminars throughout the Triad Area where you can learn about Medicare Supplement insurance, Medicare Advantage plans, and prescription drug coverage in a comfortable group setting.
Premium Payment Options and Policy Management
Once you've enrolled in a manhattan life medicare supplement, understanding how to manage your policy, pay premiums, and access policy information helps ensure smooth ongoing coverage.
Payment Methods
Manhattan Life offers several convenient premium payment options:
- Automatic bank draft: Premiums deducted automatically from your checking or savings account
- Credit card: Monthly charges to a credit or debit card
- Direct billing: Paper invoices sent to your home with payment coupons
- Annual payment: Option to pay the full year upfront, sometimes with a small discount
Setting up automatic payments eliminates the risk of missed payments and potential coverage lapses. Most policyholders find this the most convenient option, though traditional paper billing remains available for those who prefer it.
Policy Changes and Cancellations
Life circumstances change, and you may need to modify or cancel your Manhattan Life Medicare Supplement coverage. Common reasons include switching to a different carrier, enrolling in a Medicare Advantage plan, or moving to a location where Manhattan Life doesn't operate.
Understanding your rights regarding policy changes includes:
- You can cancel your Medigap policy at any time without penalty
- Premium refunds for the unused portion of prepaid coverage should be processed within 30 days
- Switching to another Medicare Supplement carrier requires new underwriting unless you have guaranteed issue rights
- Moving from Medigap to Medicare Advantage provides a trial right to return to Medicare Supplement coverage within 12 months
Regional Considerations for North Carolina Residents
Medicare Supplement pricing and availability can vary significantly by geographic location. For those living in the Triad Area, understanding how manhattan life medicare supplement rates compare locally provides more relevant information than national averages.
Triad Area Pricing Factors
Several factors influence Medicare Supplement premiums specifically in Greensboro, Kernersville, High Point, and Winston Salem:
Healthcare Costs: Regional medical costs affect insurance premiums. The Triad Area's healthcare market influences what carriers charge for coverage.
Competition: The number of insurance carriers actively marketing in a region impacts pricing. More competition generally results in better rates for consumers.
Demographics: The age distribution and health characteristics of the local population affect risk pools and pricing.
State Regulations: North Carolina's insurance regulations govern aspects of Medicare Supplement insurance, including rate filing requirements and consumer protections.
Finding the Best Local Rates
Working with a local insurance professional who understands the Triad Area market helps identify the most competitive manhattan life medicare supplement rates alongside other carrier options. Premiums for the same plan can vary by hundreds of dollars annually between carriers, making thorough comparison essential.
Visit moserinsurancegroup.com or call 336-862-1763 to request personalized quotes that reflect current pricing for your specific location and situation.
Long-Term Value Considerations
While initial premiums matter, evaluating the long-term value of a manhattan life medicare supplement requires looking beyond just the first year's cost. Medicare Supplement insurance is typically a long-term commitment, with many policyholders maintaining the same coverage for decades.
Projecting Future Costs
Attained-age pricing means your Manhattan Life premiums will increase annually as you age. While specific future increases are impossible to predict, examining the carrier's historical rate increase patterns provides some insight into what you might expect.
Consider these long-term cost factors:
- Annual aging increases: Automatic premium increases tied to your birthday
- Inflation adjustments: General rate increases applied to all policyholders regardless of age
- Health care cost trends: Rising medical costs that affect insurance premiums industry-wide
- Carrier-specific factors: Manhattan Life's claims experience and business decisions that influence rates
Switching Carriers Later
If Manhattan Life's rates become uncompetitive over time, switching to another carrier is possible but may be challenging. After your initial Medigap Open Enrollment Period, insurance companies can use medical underwriting to determine whether to accept you and what premium to charge.
This reality makes your initial carrier choice important. Selecting a company with a history of moderate rate increases can save significant money over the long term, even if their initial premium isn't the absolute lowest available.
Additional Benefits and Riders
While Medicare Supplement plans are standardized, some carriers offer additional benefits or optional riders. Understanding what manhattan life medicare supplement policies include beyond the core benefits helps you evaluate the complete value proposition.
Supplemental Benefits
Manhattan Life's policies focus primarily on the standard Medigap benefits without extensive additional perks. Unlike some carriers that bundle vision, dental, or fitness benefits, Manhattan Life generally adheres to the core Medicare Supplement coverage.
For comprehensive dental, vision, and prescription drug coverage, you'll need separate policies. Medicare Supplement plans do not include prescription drug coverage, so most beneficiaries also need a standalone Part D plan. Information about additional coverage options from Anthem demonstrates how some carriers market supplemental benefits alongside Medigap plans.
Foreign Travel Emergency Coverage
Most Medicare Supplement plans, including those from Manhattan Life, include foreign travel emergency coverage as part of the standard benefits. This coverage provides up to $50,000 per lifetime for emergency care received outside the United States after a $250 deductible.
This benefit offers valuable protection for retirees who travel internationally, covering emergency medical care that Medicare doesn't pay for outside the U.S. and its territories.
Selecting the right Medicare Supplement coverage requires understanding both the standardized benefits that all carriers provide and the carrier-specific factors that differentiate options like Manhattan Life. By comparing premiums, evaluating financial strength, and considering long-term value, you can make an informed decision that protects your health and finances. At Moser Insurance Group Inc, we help individuals and families in Greensboro, Kernersville, High Point, Winston Salem, and throughout the Triad Area understand their Medicare options with clear guidance and personalized support. Contact us at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your Medicare Supplement needs without pressure or obligation.
Recent Comments