
Finding affordable life insurance protection shouldn't require weeks of waiting, multiple doctor visits, or invasive medical testing. For many individuals and families across the Triad Area-including Greensboro, Kernersville, High Point, and Winston Salem-life insurance without medical exam offers a faster, more convenient path to securing financial protection for loved ones. These policies have evolved significantly in 2026, providing competitive coverage options with streamlined applications that can be completed in minutes rather than weeks. Understanding how no-exam policies work, who they benefit most, and what trade-offs you might face helps you make an informed decision about your family's financial future.
Understanding No-Exam Life Insurance Policies
Life insurance without medical exam allows applicants to obtain coverage without undergoing traditional medical underwriting procedures like blood tests, urine samples, or comprehensive physical examinations. Instead, insurers evaluate risk through simplified health questionnaires, prescription drug databases, and sometimes accelerated underwriting technology that analyzes existing medical records electronically.
Two primary categories dominate the no-exam market:
- Simplified issue policies require applicants to answer health questions but skip the medical exam
- Guaranteed issue policies accept all applicants regardless of health status with minimal or no health questions
- Accelerated underwriting uses algorithms and data sources to make instant decisions for healthy applicants
The application process typically takes 15 to 30 minutes for simplified issue coverage, with approval decisions arriving within hours or days. Guaranteed issue policies offer the fastest route to coverage but come with higher premiums and lower maximum benefit amounts.
How Insurers Assess Risk Without Exams
Modern insurance companies leverage sophisticated data analytics to evaluate applicants without traditional medical testing. They access prescription history databases, motor vehicle records, credit information, and even social media activity in some cases. This technology has improved dramatically since 2024, allowing insurers to price policies more accurately while reducing underwriting time by up to 90%.
The process works through risk stratification models that predict mortality risk based on hundreds of data points. Younger applicants with clean health histories often receive the same rates they would through traditional underwriting, while older applicants or those with health concerns pay premiums reflecting elevated risk.
Types of Life Insurance Without Medical Exam
Simplified Issue Life Insurance
Simplified issue represents the most popular form of no-exam coverage for healthy to moderately healthy individuals. Applicants answer 5 to 15 health questions covering major conditions like heart disease, cancer, diabetes, and stroke history. Questions also address lifestyle factors including tobacco use, occupation hazards, and recent hospitalizations.
Coverage characteristics include:
- Death benefit amounts ranging from $25,000 to $1,000,000
- Term lengths of 10, 20, or 30 years for term policies
- Permanent options including whole life and universal life variants
- Approval rates of 60-80% for applicants under age 50
Premiums for simplified issue policies typically run 15% to 40% higher than fully underwritten coverage, though the gap narrows for younger, healthier applicants. According to MoneyGeek’s 2026 analysis, a healthy 35-year-old can secure $500,000 in 20-year term coverage for $30-45 monthly through simplified issue versus $25-35 through traditional underwriting.
Guaranteed Issue Life Insurance
Guaranteed issue policies provide coverage to anyone who applies within the eligible age range, typically 45 to 85 years old. These policies ask no health questions beyond basic identification and beneficiary information. The trade-off comes through significantly higher premiums and reduced benefits during the initial policy years.
| Feature | Simplified Issue | Guaranteed Issue |
|---|---|---|
| Health questions | 5-15 questions | None or minimal |
| Maximum coverage | Up to $1,000,000 | $10,000-$50,000 |
| Graded death benefit | Rare | First 2-3 years |
| Premium cost | Moderate | Highest |
| Approval speed | 1-3 days | Immediate |
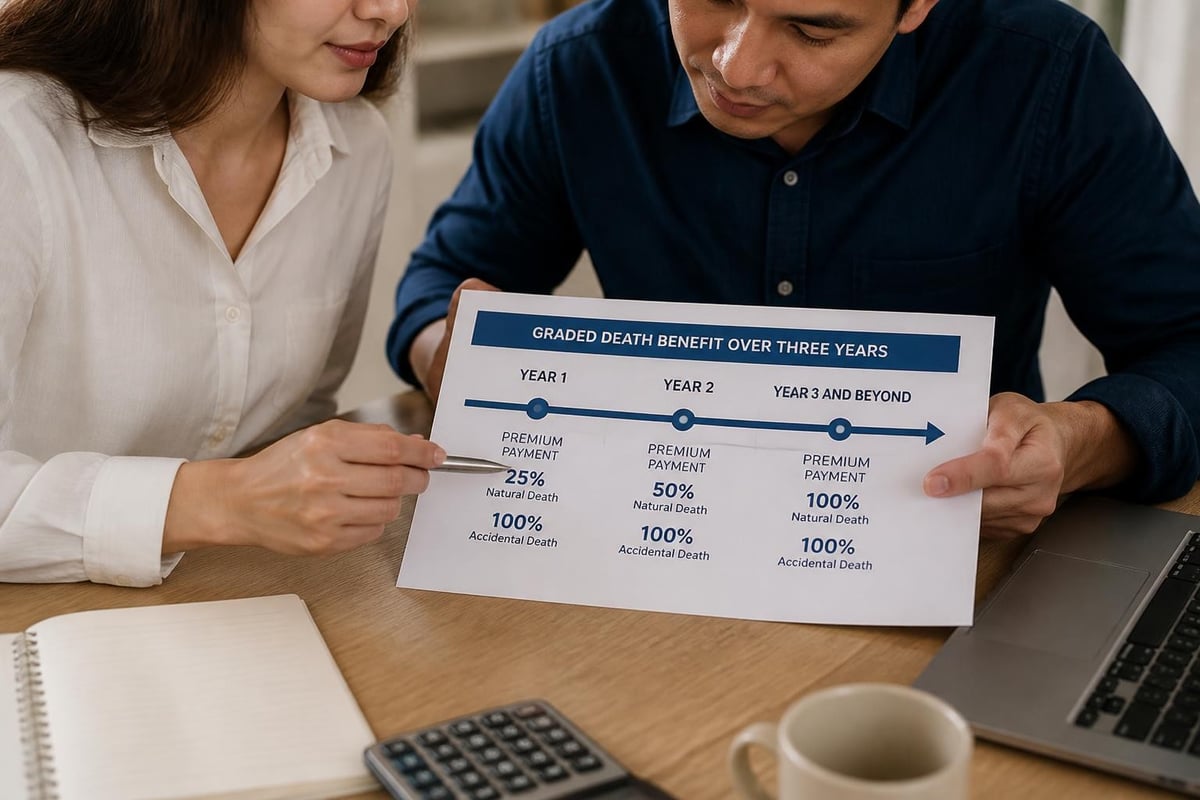
Most guaranteed issue policies include graded death benefit periods. If the insured dies from natural causes within the first two or three years, beneficiaries receive only the premiums paid plus interest rather than the full death benefit. Accidental death typically pays full benefits immediately.
Accelerated Underwriting Programs
Leading insurers now offer accelerated underwriting for applicants meeting specific health and lifestyle criteria. Northwestern Mutual and other major carriers use predictive models to identify low-risk applicants who can qualify for traditional underwriting rates without a medical exam.
These programs work best for:
- Non-smokers under age 50 with no chronic conditions
- Applicants seeking coverage amounts under $1,000,000
- Individuals with stable employment and good credit
- Those without recent hospitalizations or prescription medications for serious conditions
Approval happens within 24 to 48 hours for qualifying applicants, combining the speed of simplified issue with the pricing of traditional underwriting.
Who Benefits Most From No-Exam Coverage
Busy Professionals and Parents
People with demanding schedules struggle to find time for medical appointments, lab visits, and follow-up examinations required by traditional underwriting. A simplified application that takes 20 minutes fits much better into packed calendars than a process requiring multiple weeks and several appointments.
Time savings break down as follows:
- Application completion: 15-30 minutes versus 45-60 minutes
- Medical exam scheduling: 0 hours versus 2-4 hours for appointments
- Lab results waiting: 0 days versus 7-14 days
- Underwriting decision: 1-3 days versus 4-8 weeks
Parents purchasing coverage to protect young children particularly value the speed factor. When a second income or mortgage protection becomes urgent, waiting two months creates unnecessary risk exposure for families.
Applicants With Mild Health Concerns
Individuals managing controlled health conditions often secure better rates through no-exam policies than traditional underwriting. Conditions like well-managed high blood pressure, controlled diabetes, or past cancer remissions might trigger expensive ratings or outright declines through full underwriting but receive standard or near-standard pricing through simplified issue.
The key lies in how insurers weigh different risk factors. A 45-year-old taking blood pressure medication might face a 25% rate increase through traditional underwriting but only 10-15% through simplified issue, where broader risk pooling spreads costs across more applicants.
Older Adults Seeking Final Expense Coverage
Seniors aged 60 to 80 often find guaranteed issue policies ideal for covering funeral costs, outstanding debts, or leaving modest inheritances. New York Life notes that final expense coverage typically ranges from $10,000 to $25,000-enough to cover burial costs averaging $7,000 to $12,000 in 2026 plus settle remaining bills.
For residents throughout the Triad Area seeking straightforward protection, these smaller policies provide peace of mind without complex medical requirements. You can reach Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com to discuss final expense options tailored to your specific situation.
Cost Comparison and Premium Factors
Price Differences Across Policy Types
No-exam life insurance costs more than fully underwritten coverage because insurers assume additional risk without complete medical information. The premium difference varies based on age, health status, coverage amount, and specific insurer pricing models.
Average monthly premiums for $250,000 in 20-year term coverage:
| Age | Traditional | Simplified Issue | Guaranteed Issue* |
|---|---|---|---|
| 30 | $18-22 | $22-28 | Not available |
| 40 | $25-32 | $32-42 | Not available |
| 50 | $55-70 | $70-95 | $180-220 |
| 60 | $125-160 | $165-215 | $320-380 |
*Guaranteed issue typically maxes at $50,000 coverage
According to Progressive’s analysis, simplified issue premiums have decreased by approximately 12% since 2024 as improved data analytics reduce insurer risk uncertainty.
Factors That Influence No-Exam Rates
Insurers price no-exam policies based on hundreds of variables, but several factors carry the most weight. Age represents the primary driver-premiums double roughly every decade after age 40. Tobacco use adds 100% to 150% to base rates across all policy types.
Additional rating factors include:
- Gender: Women pay 20-30% less than men at equivalent ages
- Coverage amount: Per-dollar costs decrease as face amounts increase
- Policy length: Longer terms carry higher monthly premiums but lower per-year costs
- Occupation: Hazardous jobs trigger surcharges of 25-75%
- Hobbies: Aviation, scuba diving, and rock climbing increase rates
Health questions focus on major conditions diagnosed within the past five to ten years. Recent cancer diagnoses typically result in postponements, while 10-year cancer survivorship often qualifies for standard rates through simplified issue.
Application Process and Approval Timeline
Step-by-Step Application Guide
Applying for life insurance without medical exam follows a streamlined process that most applicants complete in a single session. The digital-first approach has become standard across the industry in 2026, with mobile applications accounting for 65% of submissions.
The typical application flow includes:
- Initial quote request: Provide age, gender, health status, and coverage needs (2 minutes)
- Detailed application: Answer health questions and provide personal information (10-15 minutes)
- Consent authorization: Approve prescription database checks and medical record access (2 minutes)
- Instant preliminary decision: Receive conditional approval or counteroffer (immediate to 24 hours)
- Final underwriting review: Insurer verifies information and issues policy (1-3 days)
Most simplified issue applications generate decisions within 72 hours. Guaranteed issue approvals happen instantly since no underwriting review occurs beyond age verification.
Common Reasons for Application Delays
While no-exam policies promise speed, certain situations trigger extended review periods. Unusual prescription patterns, conflicting information between databases, or high coverage amounts often require manual underwriting intervention.
Applications get delayed when applicants:
- Request coverage exceeding $500,000 without recent medical records
- Show prescription histories inconsistent with stated health conditions
- Have gaps in coverage history suggesting adverse selection
- Provide incomplete or contradictory answers to health questions
Responding promptly to insurer requests for clarification prevents delays from stretching beyond one week. Working with experienced agents at https://moserinsurancegroup.com helps applicants anticipate information needs and prepare documentation proactively.
Coverage Limits and Policy Restrictions
Maximum Benefit Amounts
No-exam policies cap coverage at lower amounts than traditional underwriting, though limits have increased substantially over the past three years. Most insurers now offer simplified issue term coverage up to $1,000,000 for applicants under age 50, with limits decreasing to $250,000-500,000 for applicants over 60.
Typical maximum coverage by age bracket:
- Ages 18-40: $500,000-$1,000,000
- Ages 41-50: $500,000-$750,000
- Ages 51-60: $250,000-$500,000
- Ages 61-70: $100,000-$250,000
- Ages 71+: $25,000-$100,000
Guaranteed issue policies max out between $10,000 and $50,000 regardless of applicant age. Some insurers allow stacking multiple policies to reach higher total coverage, though this approach increases administrative complexity.
Graded Death Benefits and Waiting Periods
Many guaranteed issue policies and some simplified issue policies for older applicants include graded death benefit provisions. These clauses limit payouts during the first two or three policy years, protecting insurers against adverse selection from terminally ill applicants.
| Time Period | Natural Death Benefit | Accidental Death Benefit |
|---|---|---|
| Months 1-12 | Return of premiums + 10% | 100% of face value |
| Months 13-24 | 25-50% of face value | 100% of face value |
| Months 25-36 | 50-75% of face value | 100% of face value |
| Month 37+ | 100% of face value | 100% of face value |
Western Southern’s guide notes that graded benefits have become less common for simplified issue policies as underwriting technology improves. Only 15% of simplified issue policies include grading in 2026, down from 35% in 2023.
Comparing Carriers and Finding Best Rates
Top-Rated No-Exam Insurance Providers
The no-exam life insurance market has consolidated around several major carriers with strong financial ratings and competitive pricing. Each insurer targets different demographic segments and health profiles, making comparison shopping essential.
Leading providers and their specializations:
- Mutual of Omaha: Strong guaranteed issue offerings for seniors, competitive whole life options
- John Hancock: Accelerated underwriting for healthy applicants, wellness incentive programs
- AIG: High coverage limits up to $1,000,000 simplified issue
- Prudential: Excellent rates for younger applicants seeking term coverage
- Transamerica: Flexible underwriting for applicants with controlled health conditions
Financial strength ratings matter significantly for permanent policies where cash value accumulation depends on insurer stability. All major no-exam providers maintain A.M. Best ratings of A- or higher, indicating strong claims-paying ability.
Getting Multiple Quotes Efficiently
Rate variations between carriers can exceed 40% for identical coverage, making comparison shopping critically important. Independent agents access multiple carriers simultaneously, generating quotes faster than contacting individual insurers.
The quote comparison process should evaluate:
- Premium costs over the full policy term, not just initial rates
- Conversion options allowing term policies to convert to permanent coverage
- Rider availability for accelerated death benefits, disability waivers, and children's coverage
- Customer service ratings from J.D. Power and other independent evaluators
- Claims processing speed and denial rates from state insurance departments
Working with Moser Insurance Group Inc provides access to multiple carriers serving Greensboro, High Point, Winston Salem, Kernersville, and throughout the Triad Area. Visit moserinsurancegroup.com or call 336-862-1763 to compare personalized quotes from top-rated insurers.
Alternatives to Consider
Traditional Fully Underwritten Policies
Despite the convenience of no-exam coverage, traditional underwriting delivers significant savings for healthy applicants willing to invest time in the process. A comprehensive medical exam costs applicants nothing but 30 minutes at a convenient location, with examiners traveling to homes or offices in most cases.
Cost savings through traditional underwriting:
- Ages 30-40: Save 20-35% compared to simplified issue
- Ages 41-50: Save 25-40% compared to simplified issue
- Ages 51-60: Save 30-50% compared to simplified issue
- Ages 61+: Save 40-60% compared to simplified issue
The medical exam includes blood pressure measurement, blood tests for cholesterol and glucose levels, urine analysis, and sometimes EKG or additional testing for larger coverage amounts. Results return within 7-10 days, with final underwriting decisions following within 2-3 weeks.
For individuals comfortable with medical testing and not needing immediate coverage, traditional underwriting often provides better value for term life insurance over the policy lifetime.
Group Life Insurance Through Employers
Many employers offer group life insurance as a voluntary benefit, providing guaranteed issue coverage up to specific limits without medical underwriting. Typical group policies include one to two times annual salary in automatic coverage, with options to purchase additional amounts through simplified issue.
Advantages of group coverage include:
- Lowest per-dollar costs due to group risk pooling
- Automatic payroll deduction for premium payments
- Portability options when changing employers
- Open enrollment periods allowing health-status changes
The primary disadvantage involves coverage termination upon leaving employment. Most group policies convert to individual coverage at significantly higher rates, making standalone policies more reliable for long-term protection needs.
Living Benefit Riders and Hybrid Policies
Modern life insurance has evolved beyond simple death benefit protection. Living benefit riders allow policyholders to access death benefits while alive under specific circumstances like terminal illness, chronic conditions, or critical illness diagnoses.
These riders add 5-15% to base premiums but provide valuable flexibility. A terminal illness rider typically allows accessing 50-100% of the death benefit if diagnosed with a condition expected to result in death within 12-24 months. Chronic illness riders pay benefits when unable to perform two or more activities of daily living.
Universal life insurance with no-lapse guarantees combines permanent coverage with flexible premiums and living benefits, offering comprehensive protection for families planning long-term financial security.
Special Considerations for Different Age Groups
Young Adults and Recent Graduates
Applicants in their 20s and early 30s represent ideal candidates for accelerated underwriting programs that offer traditional rates without medical exams. Good health, stable employment, and lower coverage needs align perfectly with insurer risk preferences for expedited approval.
A 25-year-old non-smoker can secure $500,000 in 30-year term coverage for $25-35 monthly through no-exam underwriting-essentially the same rates as traditional underwriting. The coverage protects future spouses, children, and mortgage obligations at locked-in rates for three decades.
Young applicants should prioritize:
- Long term lengths (30 years) to cover peak earning and family-raising years
- Convertibility options allowing conversion to permanent coverage without new underwriting
- Return of premium riders refunding all premiums if surviving the term
- Guaranteed insurability riders permitting coverage increases at life events without health questions
Middle-Aged Applicants With Families
Adults aged 40-55 carry the highest insurance needs while facing increased health concerns that complicate traditional underwriting. No-exam policies provide crucial speed advantages when replacing outdated coverage or increasing protection after major life changes like home purchases or business ventures.
This age group balances premium costs against coverage needs more carefully than younger applicants. Simplified issue makes sense when:
- Time constraints prevent scheduling medical exams within desired timeframes
- Minor health conditions might trigger ratings through traditional underwriting
- Immediate coverage needs outweigh potential long-term savings
- Existing coverage expires soon, creating gaps in family protection
Many 40-55 year-olds combine no-exam term coverage for immediate needs with traditional whole life policies for permanent protection, optimizing both speed and cost-effectiveness.
Seniors and Retirees
Guaranteed issue policies dominate the senior market, where ages 60-85 often face medical exam requirements that result in expensive ratings or coverage denials. Final expense coverage through guaranteed issue provides peace of mind without invasive underwriting.
Retirees should evaluate:
- Actual funeral and burial costs in their geographic area (averaging $8,000-$12,000 in North Carolina)
- Outstanding debts including mortgages, car loans, and credit cards
- Estate settlement costs such as attorney fees and probate expenses
- Charitable legacy goals for churches, schools, or nonprofit organizations
Working with experienced advisors ensures seniors understand graded benefit periods, premium payment options, and policy alternatives that fit fixed-income budgets while delivering necessary protection.
Making Your Decision
Questions to Ask Before Applying
Selecting the right no-exam policy requires careful evaluation of personal circumstances, financial goals, and family needs. The following questions help clarify decision factors:
Health and insurability questions:
- Do I have any diagnosed conditions that might affect traditional underwriting?
- Am I currently taking prescription medications for chronic conditions?
- Have I been hospitalized or had surgery within the past two years?
- Do I smoke tobacco or use nicotine products?
Coverage need questions:
- How much debt would my death leave for my family?
- What income replacement do my dependents need?
- How long will my family need financial support?
- What final expenses and legacy goals do I have?
Timeline and budget questions:
- How quickly do I need coverage in place?
- Can I afford 20-40% higher premiums for no-exam convenience?
- Will my health potentially improve, allowing later policy replacement?
- Do I plan to convert term coverage to permanent insurance later?
Honest answers guide you toward simplified issue, guaranteed issue, or traditional underwriting based on your unique situation.
When No-Exam Policies Make the Most Sense
Certain scenarios clearly favor no-exam coverage despite higher premiums. Immediate family protection needs, upcoming travel plans, business transaction requirements, or health conditions under active treatment all justify simplified or guaranteed issue applications.
According to Legal Clarity’s comprehensive analysis, no-exam policies provide optimal value when:
- Time urgency exceeds cost sensitivity for immediate family protection
- Health conditions create traditional underwriting uncertainty without clear outcomes
- Coverage amounts needed fall below no-exam policy maximums ($500,000 or less)
- Applicant age exceeds 60 where traditional underwriting becomes invasive and expensive
- Temporary coverage bridges gaps before employer group coverage begins
The comparison between simplified and guaranteed issue policies shows simplified issue as the preferred option for applicants able to answer health questions honestly without recent major diagnoses.
Working With Independent Agents
Independent insurance agents provide access to multiple carriers, objective comparisons, and personalized guidance through the application process. Unlike captive agents representing single companies, independent agents match client needs with the most suitable insurer from their entire portfolio.
Benefits of independent representation include:
- Competitive quote comparison across 10-15 carriers simultaneously
- Application assistance ensuring accurate answers that prevent delays or denials
- Ongoing policy service for beneficiary changes, premium adjustments, and claims
- Licensing and continuing education requirements ensuring professional competency
For residents throughout the Triad Area, connecting with local insurance professionals who understand North Carolina-specific regulations and carrier availability streamlines the entire process from initial quotes through policy delivery.
Life insurance without medical exam provides valuable protection for families across diverse circumstances, from busy young professionals to seniors planning final expenses. Understanding the differences between simplified issue and guaranteed issue coverage, comparing costs against traditional underwriting, and evaluating your specific timeline and health status helps you make confident decisions about family financial security. Whether you need immediate coverage for a growing family in Greensboro or final expense protection in Winston Salem, Moser Insurance Group Inc offers personalized guidance through every step of the process-helping you understand your options without pressure so you can choose the right coverage at the right price.
Recent Comments