

Reaching age 60 marks a significant milestone in your financial journey. While you may have spent decades building wealth and planning for retirement, protecting your loved ones remains essential. Many individuals assume that life insurance becomes unavailable or prohibitively expensive after 60, but this common misconception prevents countless families from securing crucial financial protection. The reality is that multiple affordable options exist specifically designed for those entering their retirement years, and understanding these choices can provide peace of mind for you and your beneficiaries.
Understanding Your Life Insurance Needs After 60
Life insurance over 60 serves different purposes than coverage purchased earlier in life. During your working years, policies primarily replaced income and protected against mortgage debt. Now, your priorities have shifted toward covering final expenses, leaving an inheritance, or ensuring your spouse maintains their standard of living.
Assessing Your Financial Obligations
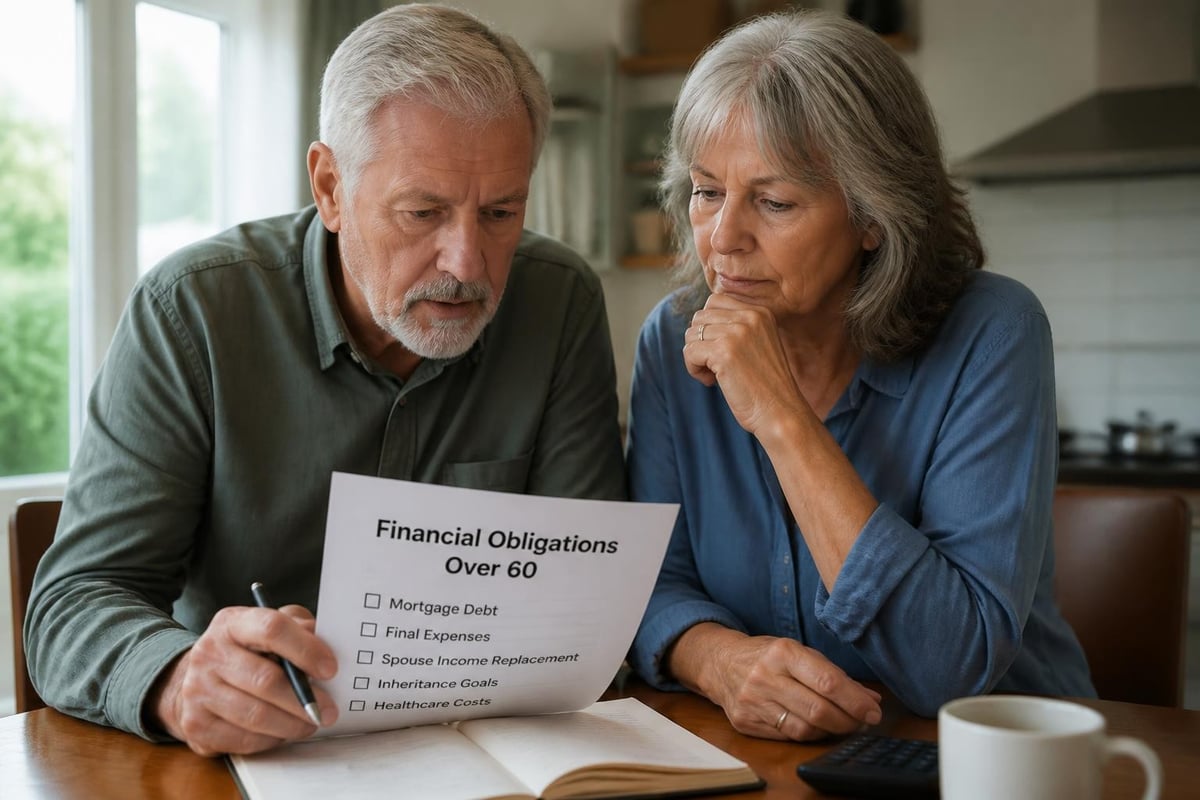
Before exploring policy types, evaluate your current financial situation honestly. Consider outstanding debts, including mortgages, car loans, or credit card balances. Your spouse may rely on your pension or Social Security benefits that disappear upon your death. Medical bills from a final illness can quickly deplete savings, leaving families struggling financially during an already difficult time.
Key factors to evaluate include:
- Remaining mortgage balance or rental obligations for your spouse
- Credit card debt or personal loans in your name
- Final expense costs including funeral and burial services
- Income replacement needs for a surviving spouse
- Estate planning goals and inheritance wishes
- Outstanding medical bills or anticipated healthcare costs
Many retirees in the Triad Area discover that life insurance options remain both necessary and affordable when aligned with specific goals rather than blanket coverage amounts.
Types of Life Insurance Over 60
The insurance marketplace offers several policy types specifically structured for older applicants. Each carries distinct advantages, costs, and qualification requirements that match different health profiles and financial objectives.
Term Life Insurance
Term policies provide coverage for a specific period, typically 10, 15, or 20 years. While less common for those over 60, term life insurance can work well if you need temporary coverage. For example, if you carry a mortgage that will be paid off in 10 years, a term policy bridges that gap affordably.
| Feature | Benefit | Consideration |
|---|---|---|
| Lower premiums | Most affordable option initially | Coverage expires after term |
| Fixed death benefit | Predictable payout for beneficiaries | No cash value accumulation |
| Simple structure | Easy to understand and compare | May not renew after term ends |
Whole Life Insurance
Whole life insurance provides permanent coverage that never expires as long as premiums are paid. These policies build cash value over time, creating a financial asset you can borrow against if needed. The premiums remain level throughout your lifetime, making budgeting straightforward.
Advantages of whole life include:
- Guaranteed death benefit regardless of when you pass
- Cash value growth that accumulates tax-deferred
- Level premiums that never increase with age
- Potential dividend payments from mutual insurance companies
- Estate planning benefits and wealth transfer strategies
The trade-off is higher initial premiums compared to term coverage. However, for individuals in Greensboro and surrounding communities seeking permanent protection, whole life delivers certainty and financial flexibility.
Guaranteed Issue Life Insurance
For those with significant health challenges, guaranteed issue policies require no medical exam and ask minimal health questions. These policies typically offer coverage amounts between $5,000 and $25,000, making them ideal for final expense planning.
The primary drawback involves a graded death benefit period, usually two to three years. If you pass away during this waiting period from natural causes, beneficiaries receive a return of premiums paid plus interest rather than the full death benefit. Accidental death typically triggers the full benefit immediately.
Final Expense Insurance
Final expense or burial insurance specifically covers end-of-life costs. These simplified issue policies require answers to health questions but no medical exam. Coverage amounts range from $5,000 to $35,000, with most policies falling between $10,000 and $20,000.
This specialized coverage addresses the reality that funeral and burial costs in 2026 average between $7,000 and $12,000 for basic services. Adding cemetery plots, headstones, and memorial services can push total expenses beyond $15,000.
Cost Factors for Life Insurance Over 60
Premium calculations for older applicants incorporate multiple variables beyond simple age considerations. Understanding these factors helps you identify opportunities to secure better rates.
Health Status and Medical History
Your current health profile significantly impacts pricing. Insurance companies evaluate chronic conditions like diabetes, heart disease, and high blood pressure. Well-controlled conditions with proper medication and doctor supervision result in better rates than unmanaged health issues.
Underwriting considers:
- Current medications and dosages
- Recent hospitalizations or surgeries
- Family history of serious illnesses
- Tobacco use within the past 12 months
- Body mass index and weight management
- Driving record and DUI history
Residents of Kernersville and High Point often discover that shopping with multiple carriers produces significantly different quotes based on each company's unique underwriting guidelines.
Coverage Amount and Policy Type
The death benefit you select directly correlates with premium costs. A $100,000 whole life policy costs substantially more than a $25,000 final expense plan. However, the per-thousand-dollars cost often decreases as coverage amounts increase, making larger policies more cost-effective if you need comprehensive protection.
| Coverage Amount | Average Monthly Premium (Age 65) | Cost Per $1,000 |
|---|---|---|
| $10,000 | $45 – $75 | $4.50 – $7.50 |
| $25,000 | $85 – $140 | $3.40 – $5.60 |
| $50,000 | $150 – $250 | $3.00 – $5.00 |
| $100,000 | $280 – $450 | $2.80 – $4.50 |
These figures represent simplified issue policies for non-smokers in average health. Guaranteed issue policies typically cost more due to reduced medical underwriting.
Gender and Lifestyle Factors
Women statistically live longer than men, resulting in lower premiums for comparable coverage. A 65-year-old woman might pay 15-30% less than a man for identical coverage due to this actuarial reality.
Lifestyle choices also matter. Participation in high-risk hobbies like skydiving or scuba diving can increase rates. Conversely, non-smokers, those maintaining healthy weight ranges, and individuals with clean driving records qualify for preferred pricing tiers.
Finding Affordable Coverage After 60
Securing cost-effective life insurance over 60 requires strategic shopping and understanding carrier differences. The insurance marketplace in Winston Salem and throughout North Carolina offers numerous options, but not all companies specialize in senior coverage.
Comparison Shopping Strategies
Working with an independent insurance agent provides access to multiple carriers simultaneously. Unlike captive agents representing single companies, independent professionals compare quotes across numerous insurers to identify the best combination of price and coverage.
Effective comparison steps include:
- Request quotes from at least three different carriers
- Compare identical coverage amounts and policy types
- Review each company's financial strength ratings
- Examine policy exclusions and waiting periods carefully
- Verify premium payment schedules and billing options
Finding affordable senior life insurance in 2026 often means looking beyond household-name companies to specialized insurers focused on older applicants.
Medical Exam vs. No-Exam Policies
Traditional underwriting involves medical exams including blood work, urine samples, and health questionnaires. This process takes several weeks but typically results in lower premiums for healthy applicants. If you maintain good health and take few medications, the medical exam route often saves money long-term.
No-exam policies expedite approval but cost more due to increased insurer risk. These work well when you need coverage quickly or have minor health issues that wouldn't significantly impact traditional underwriting outcomes.
Timing Your Application
Apply while you're relatively healthy rather than waiting until health problems emerge. A diagnosis of cancer, heart disease, or stroke dramatically increases premiums or results in coverage denial. Even waiting six months can lead to higher rates if your health deteriorates or you age into the next rate bracket.
Insurance companies use age bands, typically in five-year increments. Applying at 64 versus 65 can produce meaningful savings, as can purchasing before your next birthday rather than after.
Special Considerations for Retirement Planning
Life insurance over 60 integrates with broader retirement and estate planning strategies. Viewing coverage as an isolated decision misses opportunities to leverage policies for multiple financial objectives.
Coordinating with Social Security and Pensions
When you pass away, your spouse loses your Social Security benefit unless theirs was higher. This survivor benefit reduction can significantly impact household income. Life insurance provides a financial cushion to replace this lost income stream.
Similarly, many pensions offer joint-and-survivor options at reduced monthly payments. Choosing the single-life pension with higher payouts and purchasing life insurance to protect your spouse often delivers better overall value. This strategy requires careful calculation but frequently produces superior results.
Medicare and Healthcare Planning
Many individuals approaching age 65 focus intensely on Medicare enrollment decisions while overlooking life insurance needs. These decisions aren't mutually exclusive. In fact, comprehensive retirement planning addresses both healthcare coverage during life and financial protection after death.
Medicare doesn't cover all healthcare expenses, and serious illnesses can generate substantial out-of-pocket costs. Life insurance ensures these expenses don't deplete assets intended for your spouse or beneficiaries. For those in the Triad Area exploring coverage options, coordinating Medicare and life insurance decisions creates comprehensive protection.
Estate Planning Integration
Life insurance proceeds pass directly to named beneficiaries outside of probate, providing immediate liquidity when families need it most. This feature makes policies valuable estate planning tools, especially for individuals with assets that take time to liquidate.
Strategic applications include:
- Equalizing inheritances among multiple children
- Providing liquidity to pay estate taxes
- Funding charitable bequests without reducing family inheritance
- Creating immediate cash for estate settlement costs
- Replacing wealth transferred to charities during life
Common Mistakes to Avoid
Navigating the life insurance marketplace after 60 presents specific pitfalls that can result in overpaying for coverage or purchasing inappropriate policies.
Purchasing Insufficient Coverage
Many seniors drastically underestimate final expenses and end-of-life costs. A $5,000 policy might seem adequate until you consider that average funeral costs exceed $7,000 before adding cemetery expenses, headstones, or memorial services. Outstanding medical bills from a final illness frequently add thousands more.
Calculate realistic coverage needs based on current costs, not historical figures from decades ago. Inflation has significantly increased end-of-life expenses, and this trend continues in 2026.
Overlooking Policy Riders and Features
Policy riders customize coverage to match specific needs. Common valuable riders for those over 60 include:
- Accelerated death benefit rider: Provides access to death benefit proceeds if diagnosed with terminal illness
- Waiver of premium rider: Continues coverage if you become disabled and cannot pay premiums
- Accidental death benefit rider: Doubles or triples payout for accidental death
- Inflation protection rider: Automatically increases death benefit to keep pace with rising costs
These additions typically cost modest amounts but deliver significant value in appropriate situations.
Failing to Review Existing Coverage
Many individuals purchased life insurance decades ago and never reassessed their policies. Group coverage through former employers may have ended at retirement. Cash value in old whole life policies might provide options to reduce premiums or increase coverage through paid-up additions.
Schedule a comprehensive policy review to understand what coverage remains active, whether it aligns with current needs, and if better options exist. Some people discover they're paying for unnecessary coverage while simultaneously lacking protection in critical areas.
Working with Insurance Professionals
Professional guidance becomes increasingly valuable when purchasing life insurance over 60. The marketplace complexity, combined with health considerations and retirement planning integration, makes expert assistance worthwhile.
Benefits of Independent Agents
Independent insurance professionals represent multiple carriers, providing access to diverse product options. This structure allows objective recommendations based on your specific circumstances rather than being limited to a single company's offerings.
At Moser Insurance Group Inc, we help individuals and families throughout Greensboro, Winston Salem, and surrounding communities understand their options without pressure. Our educational approach ensures you make informed decisions aligned with your goals. Contact us at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your specific situation.
Questions to Ask Potential Agents
Not all insurance professionals possess equal expertise in senior coverage. Ask potential agents about their experience specifically with life insurance over 60 and request references from clients in similar situations.
Critical questions include:
- How many carriers do you represent for senior life insurance?
- What percentage of your clients are over age 60?
- Can you explain the difference between simplified and guaranteed issue policies?
- How do you handle claims assistance for beneficiaries?
- Do you coordinate life insurance with Medicare and retirement planning?
Professional agents should answer these questions confidently and provide clear explanations without resorting to high-pressure sales tactics.
Understanding Agent Compensation
Insurance agents earn commissions on policy sales, which some consumers view negatively. However, you pay identical premiums whether purchasing directly from carriers or through agents. The commission structure is built into pricing rather than added to your cost.
Quality agents earn their compensation by simplifying complex decisions, comparing multiple options, and providing ongoing service. They handle paperwork, follow up on underwriting questions, and assist beneficiaries with claims filing when needed.
Policy Application and Approval Process
Understanding the application journey reduces anxiety and helps you prepare necessary information. The process varies based on policy type but generally follows predictable patterns.
Required Documentation
Applications request detailed personal and health information. Gather the following before starting:
- Complete list of current medications with dosages
- Names and addresses of all physicians seen in past five years
- Details of any hospitalizations or surgeries
- Information about previous life insurance policies
- Beneficiary names, dates of birth, and Social Security numbers
- Financial information for larger coverage amounts
Having this information readily available accelerates the application process and reduces back-and-forth communication delays.
Medical Underwriting Timeline
For policies requiring medical exams, the insurer schedules a paramedical professional to visit your home at a convenient time. This appointment takes 20-30 minutes and includes basic measurements, blood draw, and urine sample collection. Results typically return within one week.
Underwriters then review your application, medical results, and prescription drug history. This analysis takes one to three weeks for standard applications. Complex health situations requiring additional medical records may extend the timeline to four to six weeks.
Simplified Issue Process
Simplified issue policies skip the medical exam but ask detailed health questions. These applications can receive approval within 24-48 hours for straightforward cases. The insurer reviews your answers against prescription drug databases and medical information bureaus to verify accuracy.
Guaranteed issue policies offer the fastest approval since they require minimal health information. Most applications receive immediate approval, with policies issuing within a few business days.
Making Your Final Decision
After researching options, comparing quotes, and consulting with insurance professionals, you face the ultimate decision of which policy to purchase. This choice deserves careful consideration rather than rushing based solely on price.
Balancing Cost and Coverage
The cheapest policy isn't always the best value. A slightly higher premium that provides significantly better coverage or eliminates waiting periods often represents superior value. Consider the total cost over your expected lifetime rather than focusing exclusively on monthly premiums.
Calculate the break-even point for different options. For example, if a guaranteed issue policy costs $50 monthly but includes a two-year waiting period, you'll pay $1,200 before full coverage begins. A simplified issue policy at $65 monthly without a waiting period provides immediate full coverage for just $15 more per month.
Reading the Fine Print
Policy contracts contain critical details that impact coverage. Review exclusion clauses, which outline circumstances where death benefits won't be paid. Common exclusions include suicide within the first two years and death during illegal activities.
Understand the contestability period, typically two years, during which insurers can investigate claims and potentially deny benefits if material misrepresentations are discovered on applications. Answer all health questions truthfully to avoid jeopardizing your beneficiaries' claims.
Finalizing Beneficiary Designations
Name primary and contingent beneficiaries clearly and specifically. Use full legal names rather than relationships like "my children" to avoid confusion. Consider naming contingent beneficiaries in case primary beneficiaries predecease you.
Review beneficiary designations every few years, especially after major life events like marriages, divorces, births, or deaths. Outdated beneficiary information causes countless legal disputes and unintended consequences.
Maintaining Your Coverage Long-Term
Purchasing life insurance over 60 represents just the beginning of your ongoing relationship with the policy. Proper maintenance ensures coverage remains in force when beneficiaries need it most.
Premium Payment Management
Set up automatic payments from checking accounts or credit cards to prevent accidental lapses. Most policies include a grace period of 30-31 days after missed payments, but relying on grace periods risks coverage termination during the period when you're unable to make payments.
Some insurers offer annual payment discounts versus monthly billing. If cash flow allows, paying annually can save 5-8% on total premiums while eliminating 12 potential payment failure points throughout the year.
Annual Policy Reviews
Schedule annual reviews to reassess coverage adequacy and confirm beneficiary designations remain current. Life changes including grandchildren births, children's marriages, or financial situations evolving may warrant coverage adjustments.
Many whole life policies allow you to purchase additional coverage through paid-up additions without new underwriting. These opportunities typically have deadlines, so regular reviews ensure you don't miss beneficial options.
Communicating with Beneficiaries
Inform beneficiaries about policy existence and location of documents. Many death benefits go unclaimed because families don't know policies exist. Provide beneficiaries with:
- Insurer name and policy number
- Agent contact information
- Location of policy documents
- Basic coverage amount
- Required documents for claims filing
This information allows efficient claims processing during an already difficult time, ensuring intended financial protection reaches your loved ones promptly.
Understanding life insurance over 60 options empowers you to protect loved ones and achieve peace of mind during retirement years. Whether you need final expense coverage, estate planning tools, or income replacement for a surviving spouse, appropriate policies exist at reasonable costs. If you're in the Triad Area including Greensboro, Kernersville, High Point, or Winston Salem, Moser Insurance Group Inc provides personalized guidance to help you make confident insurance decisions. Visit moserinsurancegroup.com, call 336-862-1763, or email moserinsurancegroup@gmail.com to explore your options with clear, pressure-free support.
Recent Comments