

Finding life insurance coverage quickly without the hassle of medical examinations or waiting periods has become increasingly accessible in 2026. Many individuals across the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, need immediate protection for their families but cannot wait weeks or months for traditional underwriting processes. Life insurance no medical exam no waiting period policies offer immediate coverage that starts on day one, providing peace of mind without extensive health screenings or delayed benefits. These policies have transformed how families secure financial protection, particularly for those with health concerns, busy schedules, or urgent coverage needs.
Understanding No Medical Exam Life Insurance Policies
Life insurance no medical exam no waiting period coverage represents a significant shift from traditional underwriting methods. Instead of requiring blood tests, urine samples, and comprehensive physical examinations, insurers use advanced algorithms and data analytics to assess risk quickly.
These policies rely on your answers to health questions, prescription drug databases, driving records, and other publicly available information. The technology behind accelerated underwriting has improved dramatically, allowing insurance companies to make accurate risk assessments in minutes rather than weeks.
How Instant Approval Works
The application process for no-exam policies typically takes 10-30 minutes online or over the phone. You provide basic information including age, health history, lifestyle factors, and coverage amount desired.
Key data sources insurers review:
- Prescription drug history through pharmacy databases
- Motor vehicle records for driving violations
- Medical Information Bureau (MIB) reports
- Credit-based insurance scores
- Public records and obituary databases
The system instantly evaluates your risk profile and determines eligibility. If approved, coverage begins immediately without any waiting period for death benefits related to accidental death, and full coverage for natural causes activates on day one for most policies.
Types of No-Exam, No-Waiting-Period Coverage
Several policy types fall under the life insurance no medical exam no waiting period category, each designed for different needs and budgets.
Simplified Issue Term Life Insurance
Simplified issue term policies offer substantial coverage amounts ranging from $25,000 to $1,000,000 or more. These policies provide protection for specific terms like 10, 20, or 30 years.
If you're looking for affordable protection for your family during critical earning years, term life insurance can be an excellent choice. The premiums remain fixed throughout the term, and the death benefit pays out tax-free to beneficiaries.
| Coverage Amount | Typical Monthly Premium (Age 35) | Term Length Options |
|---|---|---|
| $250,000 | $25-$45 | 10, 15, 20, 30 years |
| $500,000 | $45-$85 | 10, 15, 20, 30 years |
| $1,000,000 | $85-$160 | 10, 15, 20, 30 years |
Premiums vary based on age, health status, and lifestyle factors.
Guaranteed Issue Whole Life Insurance
Guaranteed issue policies accept all applicants regardless of health conditions. These permanent policies build cash value over time and provide lifelong coverage.
Important characteristics:
- No health questions required
- Coverage amounts typically range from $5,000 to $25,000
- Higher premiums relative to coverage amount
- Modified death benefit period may apply (typically two years for natural causes)
- Full accidental death coverage from day one
These policies work well for individuals with serious health conditions who cannot qualify for other coverage types.
Accidental Death Policies with Immediate Coverage
Accidental death insurance provides benefits if death results from an accident. Coverage activates immediately with no waiting period and no medical exam required.
While more limited in scope than comprehensive life insurance, these policies offer affordable supplemental protection. They work particularly well when combined with other coverage types to maximize total protection.
Cost Factors for Immediate Coverage Policies
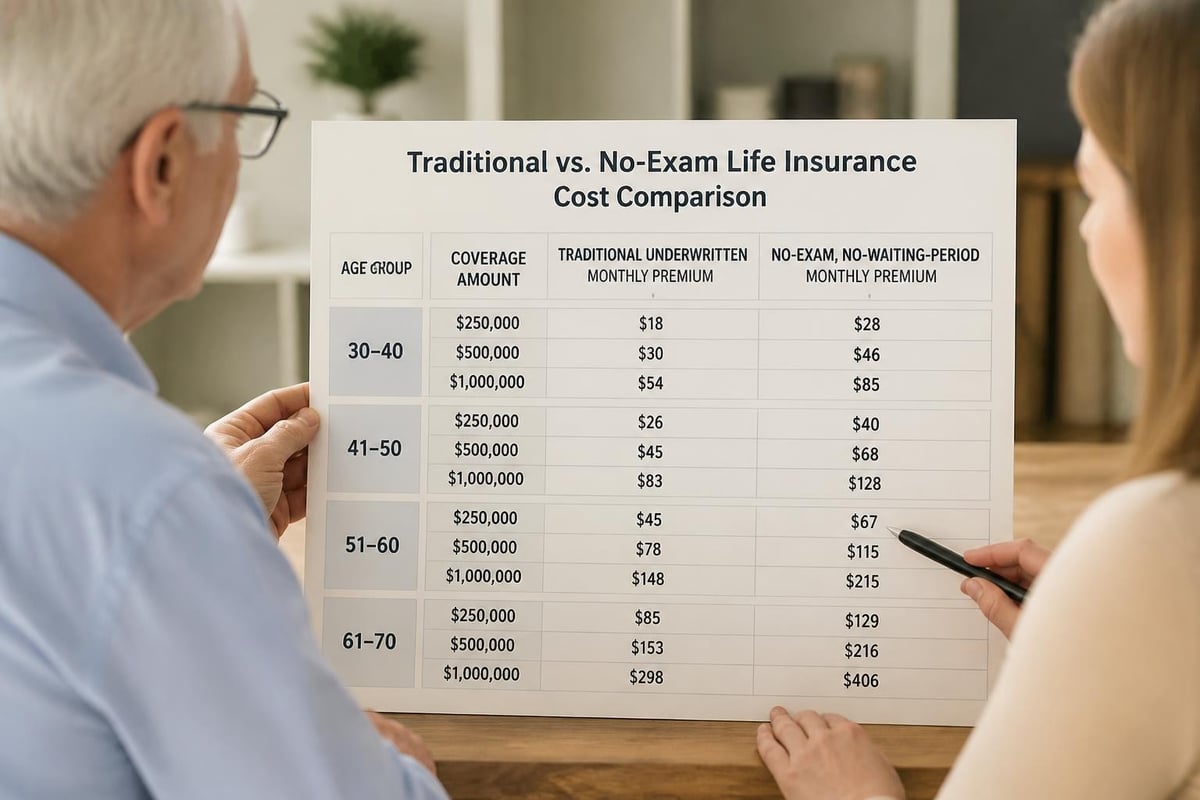
Life insurance no medical exam no waiting period policies generally cost 15-40% more than fully underwritten policies with medical exams. This premium difference reflects the increased risk insurers assume without detailed health information.
Age-Based Premium Structures
Your age at application significantly impacts premium costs. Younger applicants receive substantially better rates than older individuals.
Average monthly premiums for $250,000 simplified issue term (20-year):
- Age 25-30: $20-$35
- Age 35-40: $30-$50
- Age 45-50: $55-$95
- Age 55-60: $110-$180
These estimates assume standard health classification without significant medical conditions.
Health and Lifestyle Impact
While you skip the medical exam, insurers still evaluate health through application questions and database checks. Certain conditions or lifestyle factors increase premiums.
Higher-risk factors that affect pricing:
- Tobacco use (increases premiums 50-200%)
- Obesity (BMI over 35)
- Diabetes or heart disease history
- High-risk occupations or hobbies
- Recent DUI convictions
- Controlled substance use
Being honest on applications is critical. Misrepresentation can lead to claim denials during the contestability period.
Eligibility Requirements and Restrictions
Not everyone qualifies for life insurance no medical exam no waiting period coverage. Insurers maintain specific eligibility criteria to manage risk.
Age Limitations
Most no-exam policies have age restrictions:
- Minimum age: 18-20 years old
- Maximum age for term policies: 60-65 years old
- Maximum age for whole life: 75-85 years old
Some specialized products extend coverage for older applicants but with reduced death benefits or higher premiums.
Coverage Amount Caps
Insurers limit maximum coverage based on your income and existing insurance. Most companies cap no-exam term policies at $500,000 to $1,000,000.
Higher coverage amounts typically require traditional underwriting with medical exams. This protects both the insurer and applicant by ensuring appropriate coverage levels.
Health Question Disqualifiers
While you avoid medical exams, application questions still screen for major health conditions. Certain answers may result in declination or modified offers.
| Health Condition | Simplified Issue Result | Guaranteed Issue Result |
|---|---|---|
| Controlled diabetes | Likely approved with rating | Guaranteed approval |
| Cancer (remission 5+ years) | Case-by-case evaluation | Guaranteed approval |
| Recent heart attack (within 2 years) | Likely declined | Guaranteed approval |
| HIV/AIDS | Typically declined | Guaranteed approval |
| Serious mental illness | Case-by-case evaluation | Guaranteed approval |
Guaranteed issue policies provide options when health conditions prevent approval elsewhere.
Application Process and Approval Timeline
Applying for life insurance no medical exam no waiting period coverage is straightforward and can be completed entirely online or by phone.
Online Application Steps
The typical process includes:
- Request quotes from multiple carriers to compare rates
- Complete the online application with personal and health information
- Answer health questions honestly and thoroughly
- Provide beneficiary information and coverage preferences
- Review and e-sign the application
- Receive instant decision or follow-up within 24-48 hours
- Make first premium payment to activate coverage
Many providers offer instant approval with coverage effective immediately upon payment.
Phone Application Option
For those preferring personal assistance, phone applications provide guided support. A licensed agent walks you through each question and explains coverage details.
In the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, you can call 336-862-1763 to speak with a knowledgeable representative who can help you navigate your options.
Documentation Requirements
No-exam policies require minimal paperwork:
- Valid government-issued identification
- Social Security number
- Beneficiary names, dates of birth, and contact information
- Banking information for premium payments
- Income verification for larger coverage amounts
Most insurers deliver policies electronically, though paper copies are available upon request.
Coverage Limitations and Exclusions
Understanding what life insurance no medical exam no waiting period policies do not cover helps set appropriate expectations.
Contestability Period
All life insurance policies include a two-year contestability period from the issue date. During this time, insurers can investigate claims and deny benefits if material misrepresentation is discovered on the application.
After two years, the policy becomes incontestable except for non-payment of premiums or fraud.
Suicide Clause
Most policies exclude suicide deaths during the first two years. If the insured dies by suicide within this period, the insurer typically returns premiums paid rather than the full death benefit.
After the two-year period, suicide is covered like any other cause of death.
Modified Death Benefits
Some guaranteed issue policies include graded or modified death benefits for natural causes during the first 2-3 years. If death occurs from illness during this period, beneficiaries receive:
- Return of premiums plus interest (first year)
- Percentage of face value (second year, typically 50-75%)
- Full face value (after waiting period)
Accidental deaths pay full benefits immediately regardless of the waiting period. This structure protects insurers from adverse selection while still providing immediate accident protection.
Comparing No-Exam Options with Traditional Policies
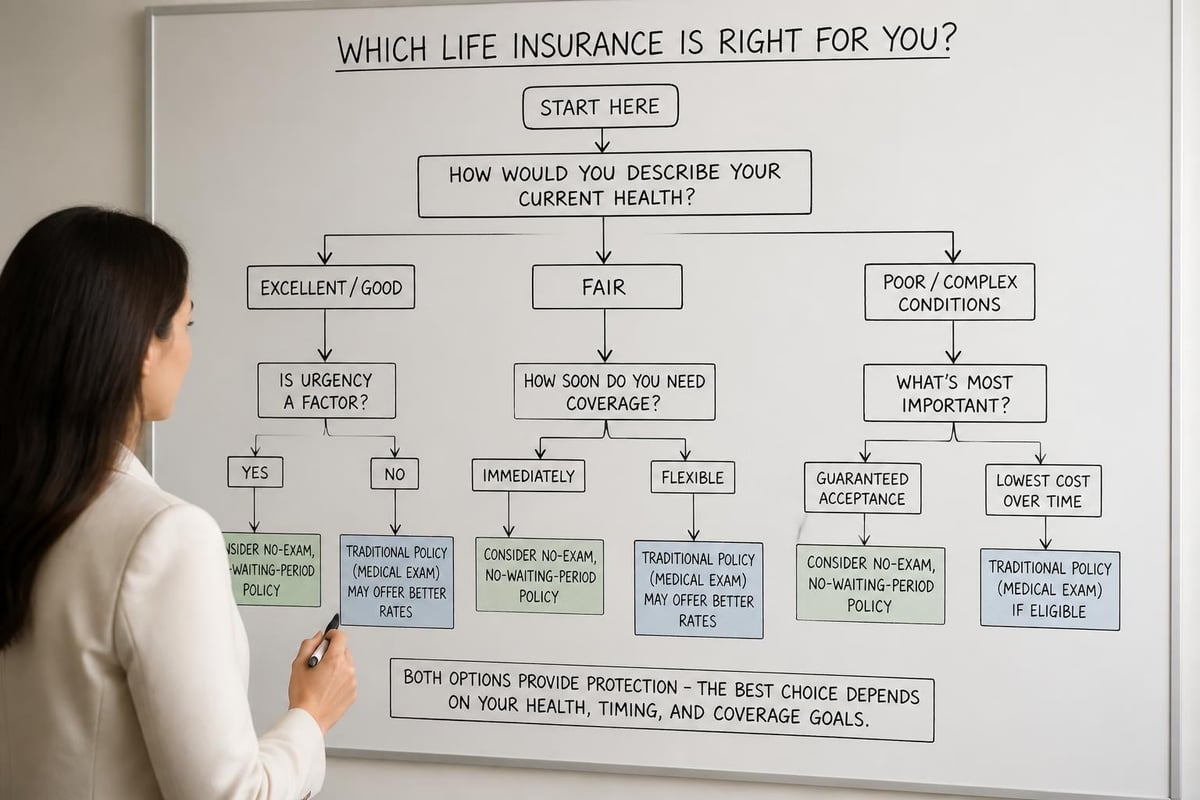
Weighing the advantages and disadvantages helps determine whether life insurance no medical exam no waiting period coverage suits your situation.
Advantages of No-Exam Policies
Immediate protection: Coverage begins the day your application is approved and payment is received, with no waiting period for accidental death and immediate full coverage for most simplified issue policies.
Convenience: Complete applications in 15-30 minutes from home without scheduling medical appointments or taking time off work.
Privacy: Avoid invasive medical examinations and sharing detailed health information with medical professionals.
Speed: Receive decisions in minutes or hours rather than waiting 4-8 weeks for traditional underwriting.
Accessibility: Qualify for coverage despite health conditions that might complicate traditional applications.
Disadvantages to Consider
Higher premiums compared to fully underwritten policies mean you pay more for the same coverage amount. Over a 20-year term, this difference can amount to thousands of dollars.
Coverage limits restrict maximum death benefits, potentially leaving gaps in family protection for high earners or those with significant financial obligations.
Less personalized underwriting may result in higher costs for very healthy individuals who would receive preferred rates through traditional processes.
Who Benefits Most from Immediate Coverage Policies
Life insurance no medical exam no waiting period policies serve specific populations particularly well.
Individuals with Health Concerns
Those with pre-existing conditions often face challenges obtaining traditional coverage. Simplified issue and guaranteed issue policies provide accessible options without the risk of declined applications.
Common conditions that complicate traditional applications include diabetes, high blood pressure, obesity, anxiety or depression, and past cancer diagnoses.
Busy Professionals
Time-constrained individuals who cannot schedule medical exams appreciate the streamlined process. Completing an application during lunch breaks or evenings fits better with demanding schedules.
Needle-Phobic Applicants
Some people have genuine phobias about needles or medical procedures. No-exam policies eliminate this barrier entirely.
Urgent Coverage Needs
When you need immediate protection due to travel plans, business obligations, or family circumstances, waiting weeks for traditional underwriting is impractical.
Older Applicants
Seniors seeking final expense or burial coverage find guaranteed issue whole life policies particularly valuable. These products ensure funds are available for end-of-life costs regardless of health status.
For comprehensive guidance on insurance options tailored to your specific situation, you can email moserinsurancegroup@gmail.com or visit moserinsurancegroup.com to explore your choices.
Tips for Getting the Best Rates
Even without medical exams, you can optimize your premium costs through strategic application approaches.
Compare Multiple Carriers
Different insurers use different underwriting algorithms and risk models. One company might offer significantly better rates based on your specific health profile.
Request quotes from at least 3-5 carriers before making a decision. Rate comparison tools streamline this process substantially.
Apply While Young and Healthy
Premiums increase with age, and health conditions accumulate over time. Securing coverage earlier locks in lower rates for the policy duration.
A 35-year-old pays dramatically less than a 50-year-old for identical coverage, even without medical exams.
Quit Tobacco Products
Tobacco use is one of the largest rating factors. If you quit smoking, many insurers reconsider your rates after 12 months of being tobacco-free.
The premium savings often exceed 50% when moving from smoker to non-smoker classification.
Choose Appropriate Coverage Amounts
Over-insuring increases costs unnecessarily, while under-insuring leaves family protection gaps. Calculate needs based on:
- Outstanding debts (mortgage, car loans, credit cards)
- Income replacement needs (typically 5-10 times annual income)
- Future expenses (college tuition, weddings)
- Final expenses (funeral, burial, estate settlement)
Match coverage amounts to actual financial obligations rather than arbitrary round numbers.
Answer Questions Accurately
Honesty on applications ensures smooth claims processing. Attempting to hide health conditions often backfires during claims investigation.
Insurers check prescription records, medical databases, and other sources. Inconsistencies trigger scrutiny and potential claim denials.
Regional Availability and Provider Options
Life insurance no medical exam no waiting period coverage is available nationwide, with numerous carriers offering products in North Carolina and throughout the Triad Area.
Top National Providers
Several well-established insurers dominate the no-exam market in 2026:
Leading companies include:
- Ethos: Offers term coverage up to $1,000,000 with decisions in minutes
- Ladder: Flexible term policies with adjustable coverage amounts
- Bestow: Simplified issue term life with competitive rates for healthy applicants
- Fabric: Fast approval process for young families
- Haven Life: Term policies up to $3,000,000 for qualified applicants
These carriers maintain strong financial ratings and competitive pricing structures.
Local Agency Support
While national direct-to-consumer options provide convenience, working with local agencies offers personalized guidance. In Greensboro, Kernersville, High Point, and Winston Salem, experienced agents help navigate the complexities of different policy types.
Local support proves valuable when comparing options, understanding policy language, and filing claims. The personalized attention ensures you select appropriate coverage for your family's unique circumstances.
When Traditional Underwriting Makes More Sense
Despite the convenience of life insurance no medical exam no waiting period policies, some situations favor traditional fully underwritten coverage.
Very Healthy Applicants
If you maintain excellent health with no medications, ideal weight, good blood pressure, and clean driving record, traditional underwriting often yields lower premiums.
The medical exam confirms your good health, qualifying you for preferred plus or preferred elite rate classes that offer significant savings.
Large Coverage Amounts
Policies exceeding $1,000,000 typically require traditional underwriting regardless of health status. Insurers need comprehensive risk assessment for high-value policies.
Long-Term Cost Optimization
When you plan to maintain coverage for 20-30 years, the cumulative premium savings from traditional underwriting can exceed $10,000-$30,000 compared to no-exam alternatives.
Investing a few extra weeks in the application process yields substantial lifetime savings.
Specific Policy Features
Some specialized riders and policy features are only available through fully underwritten policies. These include certain living benefits, return of premium riders, and customized coverage options.
Common Misconceptions About No-Exam Policies
Several myths about life insurance no medical exam no waiting period coverage persist despite their inaccuracy.
Myth: Coverage Quality Is Lower
No-exam policies provide identical death benefit protection as traditional policies from the same insurer. The payout to beneficiaries is equally guaranteed and tax-free.
The difference lies in the application process, not the coverage quality or financial security.
Myth: Only Unhealthy People Apply
Healthy individuals increasingly choose no-exam policies for convenience and speed. The simplified process appeals to busy professionals, young families, and anyone who values time efficiency.
Modern accelerated underwriting serves all health classes effectively.
Myth: Claims Get Denied More Frequently
Legitimate claims from no-exam policies are paid at the same rate as traditional policies. Insurers honor valid claims regardless of the underwriting method used.
Denials result from misrepresentation or policy exclusions, not from the lack of medical exams.
Myth: You Cannot Get Large Coverage Amounts
While coverage caps exist, many carriers offer simplified issue policies up to $1,000,000 or more. This amount provides substantial protection for most families.
Only those requiring exceptionally high coverage need traditional underwriting.
Integrating Life Insurance with Overall Financial Planning
Life insurance no medical exam no waiting period policies function as one component of comprehensive financial protection strategies.
Coordinating with Employer Coverage
Many people receive group life insurance through employers, typically 1-2 times annual salary. This coverage disappears when you leave the job.
Supplementing employer coverage with individual policies ensures continuous protection regardless of employment changes. Individual policies remain in force even during job transitions, retirement, or self-employment.
Estate Planning Considerations
Life insurance provides liquidity for estate settlement costs, including estate taxes, probate fees, and final expenses. Policies also equalize inheritances among beneficiaries when estates include illiquid assets like businesses or real estate.
Proper beneficiary designation ensures proceeds bypass probate and reach heirs quickly. Review and update beneficiaries after major life events like marriages, divorces, births, or deaths.
Business Protection Applications
Business owners use life insurance for multiple purposes:
- Key person insurance protecting against financial loss from critical employee deaths
- Buy-sell agreement funding ensuring smooth business transitions
- Executive bonus plans attracting and retaining top talent
- Debt repayment guaranteeing business loan satisfaction
No-exam policies facilitate quick implementation of these strategies without disrupting business operations for medical appointments.
Retirement and Cash Value Building
While term policies provide pure protection, permanent policies with cash value components serve dual purposes. The death benefit protects beneficiaries while accumulated cash value supplements retirement income.
Guaranteed issue whole life policies build cash value slowly but provide guaranteed growth regardless of market conditions. Policy loans against cash value offer tax-advantaged access to funds during emergencies.
Medical History Reporting and Database Checks
Understanding how insurers evaluate applications without medical exams helps applicants prepare accurate submissions.
Prescription Drug Database Searches
Insurers access comprehensive prescription histories through services like Milliman IntelliScript and ExamOne. These databases reveal medications filled within the past five to seven years.
Prescription patterns indicate underlying health conditions even without medical records. For example, insulin prescriptions confirm diabetes diagnosis, while statin medications suggest cholesterol management.
Motor Vehicle Records Review
Driving history reveals risk-taking behavior. Multiple speeding tickets, DUI convictions, or at-fault accidents increase premiums or trigger declines.
Insurers typically review the past 3-5 years of driving records. Serious violations like DUI can impact eligibility for several years after the incident.
Medical Information Bureau Reports
The Medical Information Bureau (MIB) maintains coded records of information from previous insurance applications. When you apply for coverage, your MIB report is checked for consistency with current application answers.
Discrepancies between current and past applications raise red flags requiring explanation or investigation.
Credit-Based Insurance Scores
In most states, insurers use insurance scores derived from credit reports to predict claim likelihood. Better scores correlate with lower lapse rates and more favorable underwriting outcomes.
Maintaining good credit indirectly improves life insurance approval odds and pricing.
Life insurance no medical exam no waiting period policies provide valuable protection for families across the Triad Area who need immediate coverage without extensive underwriting delays. Whether you choose simplified issue term coverage or guaranteed issue whole life, these products deliver financial security when it matters most. Moser Insurance Group Inc specializes in helping individuals and families in Greensboro, Kernersville, High Point, and Winston Salem understand their life insurance options with clear guidance and personalized support, ensuring you make confident decisions without pressure. Contact Moser Insurance Group Inc today to explore coverage options tailored to your unique needs and family circumstances.
Recent Comments