

Life insurance decisions can feel overwhelming, especially when you're trying to protect your family's financial future. Level term life insurance stands out as one of the most straightforward and affordable options available today. This type of coverage provides consistent protection with predictable costs, making it easier to budget for the long term while ensuring your loved ones receive financial support if something happens to you.
Understanding Level Term Life Insurance Fundamentals
Level term life insurance is a specific type of term policy where both your premium and death benefit remain constant throughout the entire coverage period. Unlike other insurance products where costs might increase annually or benefits might decrease over time, level term policies maintain stability from day one until the policy expires.
The mechanics are refreshingly simple. You select a coverage amount based on your family's needs, typically ranging from $100,000 to several million dollars. Then you choose your term length, commonly 10, 15, 20, or 30 years. Your monthly or annual premium is calculated based on factors like your age, health status, and coverage amount at the time of application.
Key characteristics include:
- Fixed monthly or annual premiums that never increase during the term
- Guaranteed death benefit that remains the same throughout coverage
- No cash value accumulation component
- Coverage that expires at the end of the chosen term
- Option to convert to permanent insurance with many policies
How Premium Stability Benefits Your Budget
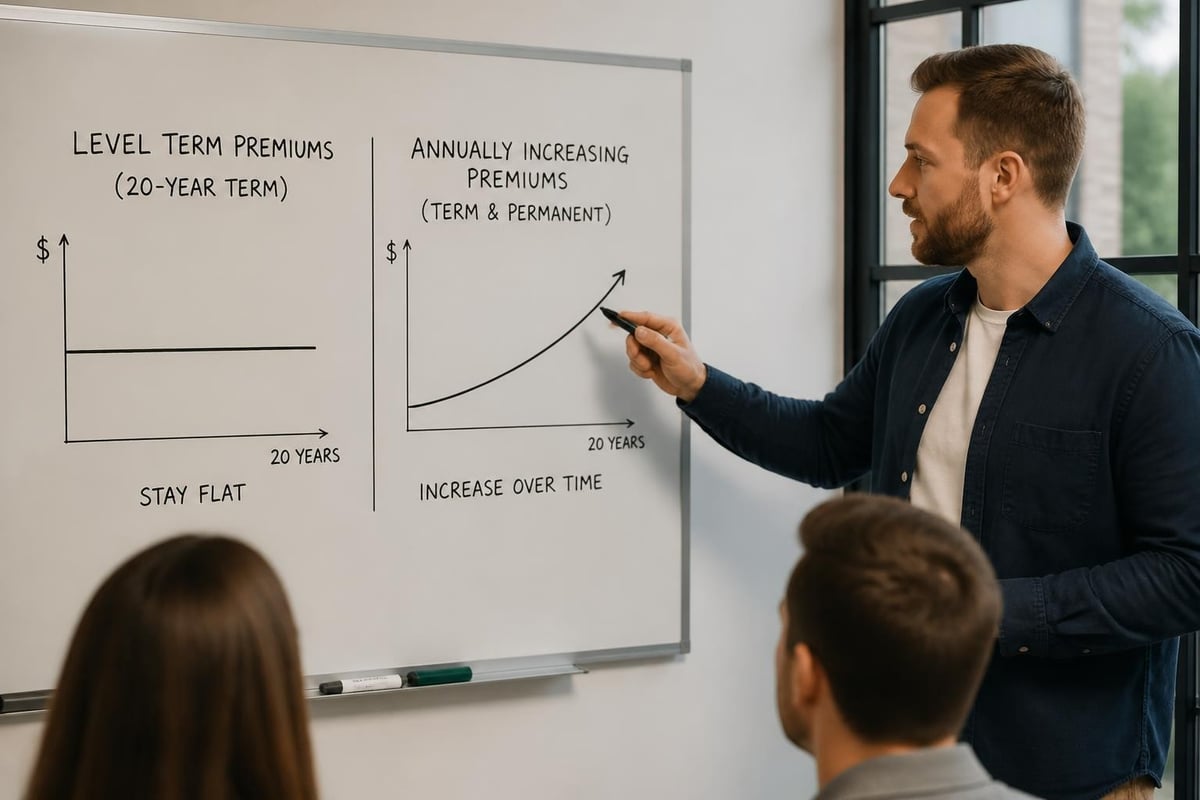
When you lock in a level premium, you're essentially protecting yourself against future rate increases. A 35-year-old purchasing a 20-year level term policy in 2026 will pay the same premium in 2046, regardless of changes to their health, the insurance market, or inflation.
This predictability makes financial planning significantly easier. You know exactly what your insurance will cost next year, in five years, and at the end of your term. For families managing mortgage payments, college savings, and retirement contributions, this certainty eliminates one variable from the budget equation.
Comparing Level Term with Other Life Insurance Options
Not all term life insurance operates the same way. Understanding the differences helps you make an informed decision about which product best serves your needs.
| Feature | Level Term | Decreasing Term | Annual Renewable Term | Permanent Insurance |
|---|---|---|---|---|
| Premium Cost | Fixed | Fixed | Increases annually | Higher, fixed |
| Death Benefit | Fixed | Decreases | Fixed | Fixed |
| Best For | General family protection | Mortgage protection | Short-term needs | Lifetime coverage |
| Cash Value | None | None | None | Yes |
| Affordability | High | Highest | Variable | Lowest |
Decreasing term life insurance features a death benefit that reduces over time, typically aligned with a decreasing debt like a mortgage. While premiums stay level, your coverage amount drops. This makes sense for specific debt protection but offers less flexibility than level term coverage.
Annual renewable term policies start with very low premiums that increase each year as you age. They work well for temporary situations but become prohibitively expensive if maintained long-term. By contrast, level term provides consistent costs throughout the entire period.
For those considering permanent coverage, universal life insurance offers lifetime protection with flexible premiums and cash value growth. However, this comes at a significantly higher cost than level term, making it suitable for different financial objectives.
When Level Term Makes the Most Sense
Level term excels in situations where you need substantial coverage for a defined period. Common scenarios include:
Income replacement during working years. If you're the primary breadwinner, your family depends on your income. A 20 or 30-year level term policy ensures they maintain their lifestyle if you pass away before retirement.
Mortgage protection. Rather than decreasing term insurance, level term provides consistent coverage that protects your home while offering flexibility. If you pay off your mortgage early or move, the full death benefit remains available for other needs.
Children's education funding. Parents often purchase level term to ensure college costs are covered if they die before their children complete school. A policy lasting until your youngest turns 25 provides comprehensive protection.
Business obligations. Entrepreneurs and business partners use level term to fund buy-sell agreements or protect against the loss of a key person. The stable death benefit ensures the business receives adequate funding regardless of when death occurs.
Choosing the Right Coverage Amount and Term Length
Determining how much coverage you need requires honest assessment of your financial obligations and goals. Financial advisors commonly recommend coverage equal to 10-15 times your annual income, but your specific situation might warrant more or less.
Calculating Your Coverage Needs
Start by listing all debts and financial obligations: mortgage balance, car loans, credit cards, student loans, and projected funeral costs. Add anticipated future expenses like college tuition for children or care for aging parents.
Next, calculate income replacement. If you earn $75,000 annually and want to replace 10 years of income, that's $750,000. Add this to your debt total for a baseline coverage amount.
Additional factors to consider:
- Current savings and investment accounts
- Spouse's income and earning potential
- Existing life insurance through your employer
- Social Security survivor benefits your family might receive
- Special needs of dependents requiring long-term care
Most families in the Triad Area find that coverage between $500,000 and $1,000,000 provides adequate protection without straining their budget.
Selecting Your Term Length Strategically
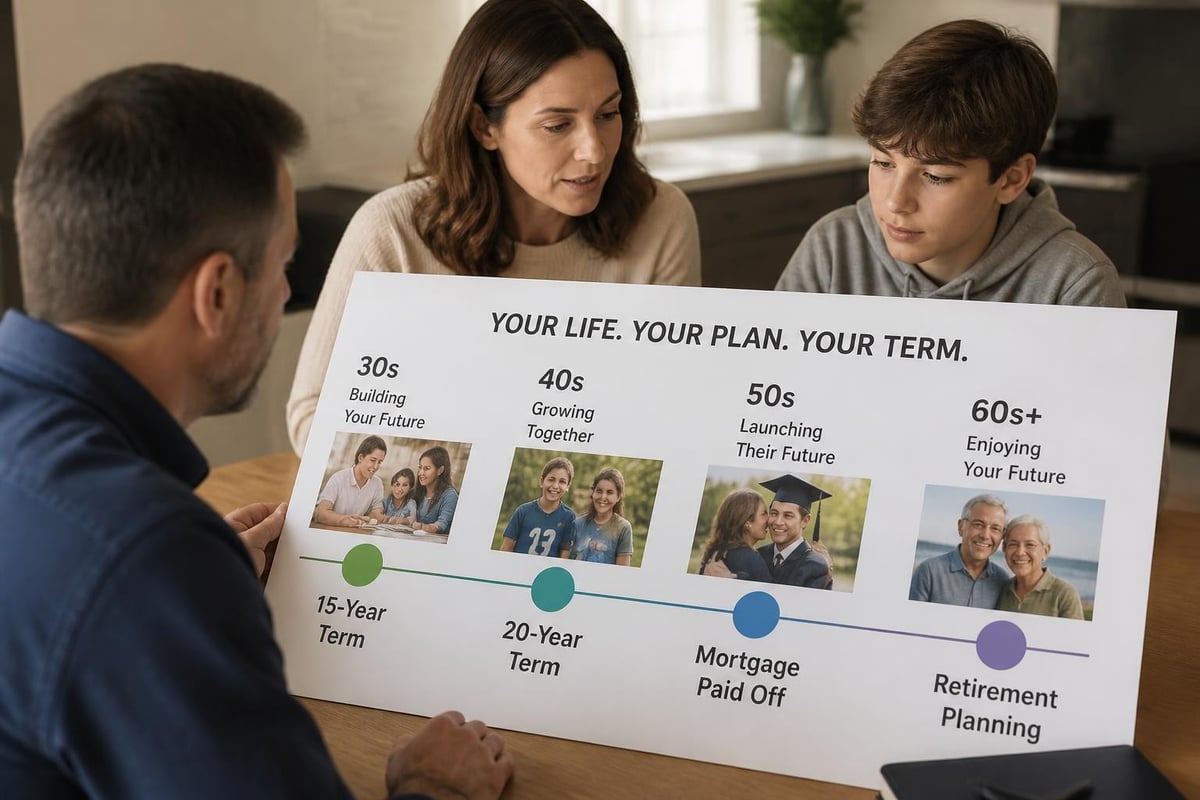
Your term length should align with your longest financial responsibility. Consider these benchmarks:
10-year terms suit short-term obligations like small business loans or covering the gap until a spouse's career advancement increases household income.
20-year terms are the most popular choice, typically covering the years until children finish college and become financially independent.
30-year terms make sense for young parents with newborns or couples with significant mortgages. They provide coverage well into your 60s when children are established and debts are paid.
Cost Factors and What to Expect in 2026
Level term life insurance remains remarkably affordable, especially for healthy applicants. Understanding how insurers calculate premiums helps you prepare for the application process and potentially secure better rates.
Primary Premium Determinants
Age is the single biggest factor. A 30-year-old pays significantly less than a 50-year-old for identical coverage because they're statistically less likely to die during the policy term. This is why purchasing coverage early saves substantial money over time.
Health status dramatically impacts pricing. Insurers evaluate your current health, medical history, family health history, and lifestyle choices. Conditions like diabetes, high blood pressure, or high cholesterol might increase premiums or require rated policies.
Tobacco use typically doubles or triples premium costs. Insurers define tobacco users broadly, including cigarettes, cigars, vaping, and chewing tobacco. Most companies require 12 months tobacco-free before qualifying for non-smoker rates.
Gender affects rates because women statistically live longer than men. A woman generally pays 20-30% less than a man of the same age and health status.
Coverage amount and term length obviously impact cost. More coverage and longer terms mean higher premiums, though the per-dollar cost often decreases as coverage amounts increase due to economies of scale.
| Age | $500,000 20-Year Term (Monthly Premium Estimate) |
|---|---|
| 30 | $25-$35 |
| 40 | $40-$55 |
| 50 | $90-$125 |
| 60 | $220-$310 |
Estimates for healthy non-smokers in 2026. Actual rates vary by insurer and individual health factors.
Ways to Reduce Your Premium
Several strategies can help you secure lower rates. Improving your health before applying makes a significant difference. Losing weight, managing blood pressure, controlling cholesterol, and quitting tobacco all contribute to better classifications.
Comparing quotes from multiple insurers is essential because each company weighs risk factors differently. What makes you high-risk at one carrier might be standard at another. At Moser Insurance Group Inc, we help clients in Greensboro, Kernersville, High Point, and Winston Salem compare options to find the best rates for their situation.
Annual payment typically costs less than monthly installments. While it requires larger upfront payment, the annual discount usually saves 8-12% over the year.
Application Process and Underwriting Considerations
Applying for level term life insurance involves several steps designed to assess your risk profile accurately. Understanding the process reduces anxiety and helps you prepare appropriate documentation.
What to Expect During Application
The initial application requests detailed personal information: age, address, occupation, income, existing insurance, and beneficiary designations. You'll answer comprehensive health questions about current conditions, medications, past surgeries, and family medical history.
Most applications require a medical examination, typically conducted at your home or office at no cost to you. The paramedical examiner collects:
- Height and weight measurements
- Blood pressure and pulse readings
- Blood samples for laboratory analysis
- Urine sample for health screening
- Sometimes EKG for larger coverage amounts or older applicants
The insurer's underwriters review your application, exam results, prescription history reports, and sometimes medical records from your physicians. This process typically takes 4-6 weeks, though some insurers now offer accelerated underwriting with decisions in days for healthy applicants.
Understanding Underwriting Classifications
Insurers assign you to a health classification that determines your premium:
Preferred Plus/Elite represents the healthiest applicants with ideal height-weight ratios, excellent family history, and no health conditions. These applicants receive the lowest available rates.
Preferred includes very healthy people with minor issues like well-controlled blood pressure or slightly elevated cholesterol.
Standard Plus applies to average health with some manageable conditions but nothing serious.
Standard represents typical health for your age with common conditions that don't significantly impact life expectancy.
Rated/Table classifications apply when health issues increase risk. The insurer adds percentage increases to standard rates based on severity.
Policy Features and Riders to Consider
While level term life insurance is straightforward, optional features can enhance protection for specific situations. Understanding available riders helps you customize coverage to your needs.
Conversion Privilege
Most level term policies include a conversion option allowing you to exchange your term policy for permanent insurance without new medical underwriting. This proves invaluable if you develop health conditions during your term that would make permanent insurance unaffordable or unavailable later.
Conversion deadlines vary by policy. Some allow conversion anytime during the term, while others restrict it to the first 10-15 years. If permanent coverage might interest you eventually, verify conversion terms before purchasing.
Common Rider Options
Accelerated death benefit riders allow you to access a portion of your death benefit if diagnosed with a terminal illness. This money can pay medical bills, experimental treatments, or allow you to spend quality time with family rather than working during your final months.
Waiver of premium riders continue your coverage without requiring premium payments if you become totally disabled. The policy remains in force, ensuring your family stays protected even when income stops.
Child term riders add coverage for your children at minimal cost. If a child passes away, you receive a small death benefit to cover funeral expenses and time away from work.
Accidental death benefit riders pay an additional amount if death results from an accident. While inexpensive, these riders are often unnecessary since level term already provides comprehensive death benefits regardless of cause.
Common Misconceptions About Level Term Coverage
Several myths persist about level term life insurance that prevent people from making informed decisions. Clearing up these misunderstandings helps you evaluate whether this coverage suits your needs.
Myth: If you outlive the term, you wasted money. This misses the point entirely. Insurance protects against risk. You don't waste money on car insurance if you don't have an accident. Level term provides peace of mind and financial security during your family's vulnerable years. If you outlive the policy, that's the best possible outcome.
Myth: Employer coverage is sufficient. Workplace life insurance typically provides one to two times annual salary, often inadequate for comprehensive family protection. Additionally, coverage ends when you leave the job, potentially when health conditions make individual insurance expensive or unavailable.
Myth: Young, healthy people don't need life insurance. Actually, young and healthy is the ideal time to purchase coverage. Premiums are lowest when you're young, and locking in rates now protects against future health changes. Even without dependents, coverage can pay final expenses and debts, preventing burdens on parents or siblings.
Myth: Level term is too expensive. For most people, term life insurance is remarkably affordable. A healthy 35-year-old might pay less than $50 monthly for $500,000 of coverage, less than many spend on streaming services or coffee. The cost of not having protection far exceeds premium expenses.
Special Considerations for Different Life Stages
Your insurance needs evolve throughout life. Level term adapts to various situations by offering appropriate coverage amounts and term lengths for each stage.
Young Adults and Newlyweds
Even without children, young couples benefit from coverage that pays off shared debts, maintains the mortgage if one spouse dies, and provides income replacement. A 20 or 30-year term ensures protection through child-rearing years and major financial obligations.
Consider purchasing now while rates are lowest rather than waiting until children arrive when budgets are tighter and premiums higher due to increased age.
Growing Families
Parents with young children need substantial coverage. Calculate expenses including mortgage payoff, college funding for all children, and 10-15 years of income replacement. A 30-year term purchased when your youngest is born provides coverage until they're established adults.
Both spouses should carry coverage, including stay-at-home parents whose childcare, household management, and other contributions have significant economic value.
Mid-Career Professionals
By your 40s and 50s, existing term policies might approach expiration while financial obligations persist. Review coverage to ensure it aligns with current debts, college costs, and retirement goals. If your health remains good, purchasing a new policy before an existing one expires maintains continuous protection.
This stage often involves caring for aging parents while supporting children, potentially requiring higher coverage amounts than earlier years.
Pre-Retirees and Retirees
As you approach retirement with paid-off mortgages, grown children, and accumulated savings, life insurance needs typically decrease. However, coverage might still make sense for estate planning, final expenses, or leaving a legacy.
Some retirees maintain smaller level term policies to cover funeral costs and ease burdens on adult children. Others shift to permanent insurance for estate liquidity or charitable giving strategies.
Making Your Decision and Moving Forward
Choosing level term life insurance requires balancing coverage needs, budget constraints, and long-term financial goals. Take time to evaluate your specific situation honestly rather than rushing into a decision.
Steps to Take Today
Calculate your actual needs using the factors discussed earlier. Be realistic about debts, income replacement requirements, and future obligations like college costs.
Determine your budget for monthly premiums. Remember that coverage costs less than you probably expect, but ensure premiums fit comfortably within your monthly expenses.
Compare options from multiple carriers. Different insurers price risk differently, and the company offering the best rate for one person might not be competitive for another with different health factors.
Review policy details carefully before signing. Understand your conversion options, rider choices, and policy terms completely.
Consider your beneficiary designations thoughtfully. Update beneficiaries whenever major life changes occur, like marriage, divorce, births, or deaths.
For residents throughout the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, working with an experienced insurance professional simplifies the process. Local expertise helps you navigate options, compare carriers effectively, and ensure your coverage truly meets your family's needs.
Questions to Ask Before Purchasing
Before finalizing your level term policy, confirm several critical details:
- What is the exact premium, and does it include all fees?
- When can I convert to permanent insurance, and what are the terms?
- Are there any health conditions that might affect my rate or eligibility?
- What happens if I miss a premium payment?
- Can I increase coverage later without new underwriting?
- What is the claims process for my beneficiaries?
Don't hesitate to ask your insurance professional to explain anything unclear. Quality advisors welcome questions and prioritize your understanding over quick sales.
Protecting What Matters Most
Level term life insurance offers a straightforward, affordable way to protect your family's financial future during your most vulnerable years. Its predictable premiums and guaranteed death benefit eliminate uncertainty while providing substantial coverage for a fraction of permanent insurance costs.
The key is taking action while you're healthy and rates are favorable. Waiting rarely improves your situation, and health changes can dramatically increase costs or even prevent coverage approval. Whether you need $250,000 for a decade or $1,000,000 for 30 years, level term policies adapt to your specific requirements.
Remember that life insurance isn't about you-it's about the people who depend on you. Your spouse who shares expenses and dreams, your children who need years of support and education, your aging parents who might need care, or business partners counting on continuity all benefit from the protection you establish today.
Level term life insurance provides affordable, predictable protection when your family needs it most, with fixed premiums and guaranteed death benefits throughout your coverage period. If you're ready to explore your options or have questions about finding the right coverage for your situation, Moser Insurance Group Inc can help you navigate these important decisions with personalized guidance and clear answers. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com to discuss how level term coverage fits your family's financial plan.
Recent Comments