
Navigating the complex landscape of health insurance requires understanding how insurance companies health insurance products work and what differentiates one provider from another. With healthcare costs continuing to rise in 2026, selecting the right insurance company and plan has never been more critical for individuals and families across the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem. Whether you're approaching Medicare eligibility, shopping for supplemental coverage, or seeking comprehensive family protection, knowing what insurance companies offer and how they deliver health insurance can help you make informed decisions that protect both your health and financial well-being.
Understanding How Insurance Companies Structure Health Insurance
Insurance companies health insurance offerings have evolved significantly to meet diverse consumer needs. Major carriers design their products around several core components that determine both cost and coverage quality.
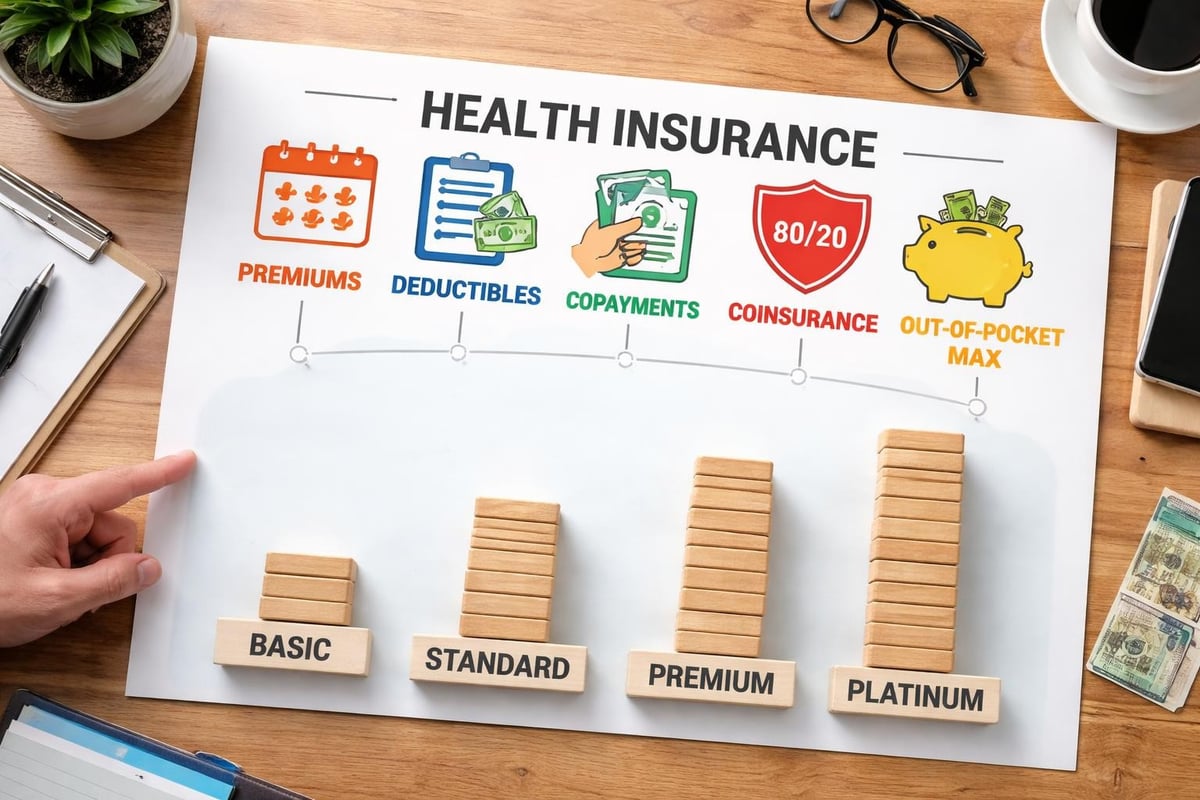
Premium structures represent the monthly payment you make to maintain coverage, regardless of whether you use medical services. Insurance companies calculate premiums based on multiple factors including age, geographic location, tobacco use, and the specific benefits included in your plan.
Deductibles and out-of-pocket maximums form the foundation of cost-sharing arrangements. Your deductible is the amount you pay before insurance coverage begins, while the out-of-pocket maximum caps your annual spending on covered services.
Key Coverage Components
- Network design determines which doctors and facilities you can access
- Prescription drug formularies specify which medications receive coverage
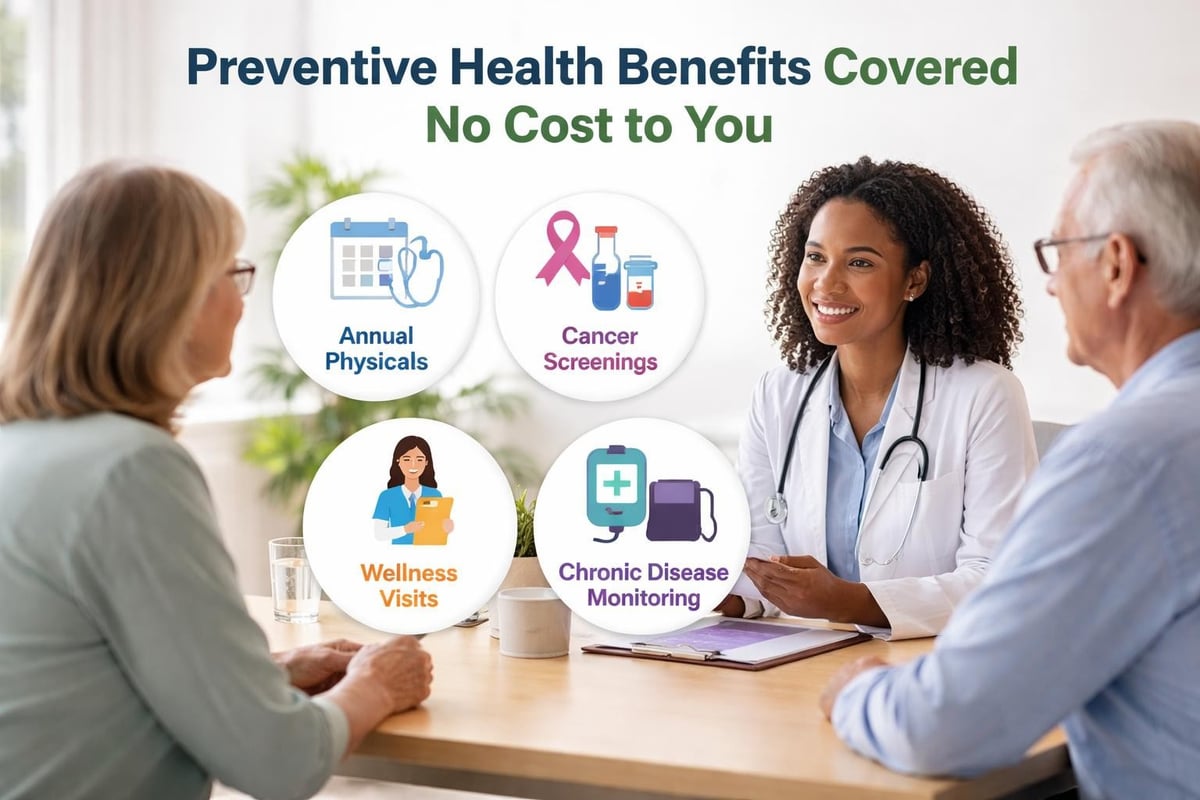
- Preventive care benefits often include no-cost screenings and wellness visits
- Specialist access varies between plans requiring referrals versus open access
The top health insurance companies in the United States control significant market share, which often translates to broader provider networks and negotiating power with healthcare facilities. In North Carolina, residents have access to both national carriers and regional providers tailored to local healthcare systems.
Major Types of Health Insurance Products
Insurance companies health insurance portfolios typically include multiple product categories designed for different life stages and needs. Understanding these distinctions helps consumers match coverage to their specific situations.
Medicare Products
For individuals turning 65 or those with qualifying disabilities, Medicare represents the primary health insurance option. Insurance companies offer Medicare Advantage plans (Part C) that bundle hospital, medical, and often prescription drug coverage into single packages. Many carriers also provide standalone Part D prescription drug plans and Medicare Supplement (Medigap) policies.
Medicare Advantage enrollment has grown substantially, with CVS Health reporting improved Medicare business performance in recent quarters. These plans often include additional benefits beyond Original Medicare, such as dental, vision, and hearing coverage.
Those new to Medicare can benefit from understanding Medicare Part D coverage gap provisions, which affect prescription drug costs at certain spending thresholds.
Individual and Family Plans
For those not eligible for Medicare or employer coverage, individual and family health insurance provides comprehensive medical protection. These plans must comply with Affordable Care Act regulations, ensuring coverage for essential health benefits and preventing discrimination based on pre-existing conditions.
| Plan Type | Network Flexibility | Monthly Premium | Out-of-Pocket Costs |
|---|---|---|---|
| HMO | Lowest – requires referrals | Lower | Moderate with in-network care |
| PPO | High – no referrals needed | Higher | Lower deductibles, higher premiums |
| EPO | Moderate – in-network only | Moderate | Varies by plan |
| HDHP | Varies | Lowest | Highest deductible, HSA-eligible |
Evaluating Insurance Company Financial Strength and Stability
When selecting insurance companies health insurance products, financial stability matters tremendously. An insurance company's ability to pay claims, maintain provider networks, and continue operations through economic uncertainty directly impacts your coverage security.
Rating agencies like AM Best, Moody's, and Standard & Poor's assess insurance company financial health. Look for carriers with ratings of A- or higher, indicating strong financial positions and claims-paying ability.
UnitedHealth Group’s recent adjustments to rising medical costs demonstrate how even major carriers must adapt to healthcare spending trends. Understanding how insurance companies manage these pressures helps predict premium stability and benefit continuity.
Financial Indicators to Consider
- Loss ratios showing the percentage of premiums paid out in claims
- Reserve levels ensuring sufficient funds for future claims
- Market capitalization for publicly traded companies
- Years in business indicating operational experience
Residents of Greensboro, Kernersville, High Point, and Winston Salem should verify that chosen carriers maintain strong provider relationships with local healthcare systems like Cone Health, Novant Health, and Wake Forest Baptist Health.
Network Quality and Provider Access
Insurance companies health insurance value depends heavily on network adequacy. The breadth and depth of participating providers determine whether you can access quality care conveniently.
Network Adequacy Standards
Strong networks include sufficient primary care physicians, specialists across major medical disciplines, nearby hospitals with quality ratings, and convenient pharmacy locations. Before enrolling, verify that your current doctors participate in the network or identify acceptable alternatives in your area.
Tiered networks have become increasingly common, with insurance companies offering lower cost-sharing when you use "preferred" or "tier one" providers. These arrangements reward patients for selecting high-value providers while maintaining access to broader networks at higher costs.
For those in the Triad Area, checking network directories for providers in Greensboro, Kernersville, High Point, and Winston Salem ensures convenient access to care without extensive travel.
Customer Service and Claims Processing
Even the most comprehensive coverage loses value if insurance companies health insurance administration creates obstacles to care. Customer service quality and claims processing efficiency significantly impact your healthcare experience.
Service Quality Indicators
- Claims processing speed – average time from submission to payment
- Appeal success rates – percentage of denied claims overturned on appeal
- Customer satisfaction scores – ratings from independent surveys
- Digital tools quality – mobile apps and online portals for managing coverage
- Phone support accessibility – wait times and resolution rates
Best health insurance companies for 2026 rankings often emphasize customer satisfaction alongside coverage value. Companies that invest in member support infrastructure typically deliver smoother experiences when you need to use your benefits.
Prescription Drug Coverage Considerations
Medication access represents a critical component of insurance companies health insurance offerings. Prescription drug coverage varies widely between carriers and plans, affecting both medication availability and out-of-pocket costs.
Formulary tiers categorize medications by cost-sharing level. Generic drugs typically occupy the lowest tier with minimal copays, while brand-name and specialty medications require higher cost-sharing or prior authorization.
Understanding Drug Coverage
| Formulary Tier | Typical Medications | Cost-Sharing Level |
|---|---|---|
| Tier 1 | Generic drugs | $5-15 copay |
| Tier 2 | Preferred brands | $30-50 copay |
| Tier 3 | Non-preferred brands | $60-100 copay |
| Tier 4 | Specialty medications | 25-33% coinsurance |
Prior authorization requirements mean you must receive insurance company approval before certain medications receive coverage. Step therapy protocols require trying less expensive alternatives before covering higher-cost options.
Medicare beneficiaries should understand how Part D plans structure drug coverage, including the coverage gap implications. Resources about expanding Medicare benefits can help seniors maximize their coverage.
Preventive Care and Wellness Programs
Modern insurance companies health insurance products increasingly emphasize preventive care and wellness initiatives. These programs aim to catch health issues early and promote healthier lifestyles, potentially reducing long-term healthcare costs.
No-cost preventive services under the Affordable Care Act include annual wellness visits, cancer screenings, immunizations, and chronic disease management support. These services receive full coverage without deductible requirements.
Many carriers offer wellness incentives such as gym membership reimbursements, weight management programs, smoking cessation support, and health coaching services. Some plans provide premium discounts for completing health assessments or achieving wellness goals.
Comparing Plans Within the Same Insurance Company
Insurance companies health insurance portfolios typically include multiple plan options at different price points and coverage levels. Understanding how to compare these internal options helps identify the best value for your needs.
Metal Tier Classifications
- Bronze plans – lowest premiums, highest deductibles (60% actuarial value)
- Silver plans – moderate premiums and deductibles (70% actuarial value)
- Gold plans – higher premiums, lower deductibles (80% actuarial value)
- Platinum plans – highest premiums, lowest deductibles (90% actuarial value)
Your optimal choice depends on expected healthcare utilization. Healthy individuals with minimal medical needs often benefit from bronze or silver plans with lower premiums, while those with chronic conditions or planned procedures may find gold or platinum plans more cost-effective overall.
Special Enrollment Considerations
Understanding when you can enroll in insurance companies health insurance matters as much as which plan you choose. Missing enrollment windows can leave you without coverage or facing penalties.
Medicare Initial Enrollment Period spans seven months around your 65th birthday. Late enrollment may result in permanent premium penalties for Part B and Part D coverage.
Annual Enrollment Periods allow changes to existing coverage. For Medicare, this runs October 15 through December 7 annually. Individual marketplace plans use November 1 through January 15 for most states.
Special Enrollment Periods trigger upon qualifying life events including marriage, birth of a child, loss of other coverage, or relocation to new service areas. Documentation requirements vary by circumstance.
Regional Considerations for North Carolina Residents
Insurance companies health insurance availability and pricing vary significantly by geographic region. North Carolina residents in the Triad Area face specific market dynamics affecting their options.
State insurance regulations influence plan designs and rate approvals. North Carolina uses the federal marketplace for individual coverage, while Medicare products follow national guidelines with local network variations.
Triad Area Healthcare Landscape
The Greensboro, Kernersville, High Point, and Winston Salem region benefits from multiple major health systems creating competitive provider networks. Insurance companies contracting with these systems offer varying levels of access and pricing.
Local provider concentrations in the Triad include numerous primary care practices, specialty clinics, and hospital facilities. Verifying your preferred providers participate in prospective insurance company networks prevents unexpected out-of-network costs.
For personalized guidance on available options, residents can contact Moser Insurance Group Inc at 336-862-1763 or email moserinsurancegroup@gmail.com.
Supplemental Coverage Options
Beyond primary insurance companies health insurance products, supplemental policies address specific coverage gaps. These additions can provide valuable financial protection for anticipated healthcare needs.
Medicare Supplement Insurance (Medigap) covers cost-sharing expenses that Original Medicare doesn't pay, including deductibles, copayments, and coinsurance. These standardized plans work alongside Original Medicare and Part D prescription coverage.
Dental and vision insurance often requires separate policies, as most health insurance plans provide limited or no coverage for routine dental care and eyewear. Standalone policies or discount plans may offer better value for regular dental and vision needs.
Understanding the importance of comprehensive health insurance coverage helps individuals protect their financial stability against unexpected medical expenses.
Digital Tools and Telehealth Access
Modern insurance companies health insurance platforms increasingly incorporate digital health solutions. These technological features enhance convenience and expand care access beyond traditional office visits.
Mobile applications allow members to view coverage details, check claim status, find providers, access digital ID cards, and communicate with customer service. User-friendly apps improve the overall insurance experience.
Telehealth benefits expanded dramatically during the pandemic and remain a valuable coverage component. Virtual visits for minor illnesses, mental health services, and chronic condition management provide convenient, cost-effective care alternatives.
Many plans now cover remote patient monitoring, virtual physical therapy, and digital mental health platforms. These services particularly benefit those in areas with limited specialist access or mobility challenges.
Making Your Decision
Selecting among insurance companies health insurance options requires balancing multiple factors against your specific needs and budget. No single "best" carrier exists for everyone.
Decision Framework
- Calculate total annual costs including premiums, expected out-of-pocket expenses, and prescription costs
- Verify network adequacy for your preferred providers and nearest quality facilities
- Review coverage details for services you regularly use or anticipate needing
- Assess financial stability through rating agency reports and company performance
- Test customer service by calling with questions before enrolling
For those approaching Medicare eligibility, exploring Medicare Advantage versus Medicare Supplement options provides insight into fundamentally different coverage approaches.
Detailed comparison of permanent insurance policies demonstrates how methodical evaluation techniques apply across insurance product types.
Getting Professional Guidance
Insurance companies health insurance complexity often justifies working with licensed insurance professionals who can explain options, compare plans objectively, and assist with enrollment processes. Independent agents access multiple carriers, offering broader perspective than captive agents representing single companies.
Local expertise proves particularly valuable for understanding regional network dynamics and identifying carriers with strong Triad Area provider relationships. Agents familiar with Greensboro, Kernersville, High Point, and Winston Salem healthcare systems can match you with appropriate networks.
Questions about specific insurance companies health insurance products, Medicare options, or supplemental coverage receive clearer answers from experienced professionals who stay current with industry changes and regulatory updates.
Visit moserinsurancegroup.com or call 336-862-1763 to discuss your specific situation with knowledgeable advisors who prioritize education over pressure sales tactics.
Understanding how insurance companies health insurance works empowers you to select coverage that protects your health and financial security effectively. The right plan balances comprehensive benefits with affordable costs while providing access to quality providers in your community. Whether you're navigating Medicare decisions, seeking family coverage, or exploring supplemental options, Moser Insurance Group Inc offers personalized guidance to help individuals and families throughout the Triad Area make confident insurance choices. Reach out at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your coverage needs with professionals committed to clear, pressure-free education.
Recent Comments