

Your ability to earn a paycheck represents your most valuable financial asset. Without a steady income, meeting mortgage payments, covering everyday expenses, and maintaining your family's standard of living becomes nearly impossible. Income protection insurance provides a safety net when unexpected illness or injury prevents you from working, replacing a portion of your lost wages during your recovery period. For individuals and families in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, understanding this critical coverage can make the difference between financial stability and hardship during challenging times.
What Income Protection Insurance Covers
Income protection insurance, also known as disability income insurance, pays you a monthly benefit when you cannot work due to a covered illness or injury. This coverage goes beyond what most people expect from traditional health insurance.
The policy replaces a percentage of your pre-disability income, typically between 50% and 70% of your gross earnings. This replacement income helps cover essential expenses while you focus on recovery rather than financial stress.
Key coverage features include:
- Monthly benefit payments during your disability period
- Coverage for both accidents and illnesses
- Protection for short-term and long-term disabilities depending on policy type
- Benefits that continue until you recover or reach the maximum benefit period
- Tax-free benefits in many cases when you pay premiums with after-tax dollars
Understanding Benefit Periods and Elimination Periods
Two critical terms shape how your income protection insurance functions in practice. The elimination period represents the waiting time between when your disability begins and when benefit payments start. Common elimination periods range from 30 days to 180 days.
The benefit period determines how long you receive payments if your disability continues. Short-term policies might pay benefits for three months to two years, while long-term policies can extend to age 65 or 67.
| Policy Type | Elimination Period | Benefit Period | Monthly Premium (Relative) |
|---|---|---|---|
| Short-term | 0-14 days | 3-24 months | Higher |
| Long-term | 90-180 days | To age 65-67 | Lower |
| Hybrid | 30-90 days | 2-5 years | Moderate |
Choosing longer elimination periods reduces your premium costs because you assume more initial risk yourself.
Who Needs Income Protection Insurance
Anyone who depends on their paycheck to maintain their lifestyle should consider this coverage seriously. According to the Citizens Advice guidance on income protection, one in seven workers will experience a disability lasting five years or longer before reaching retirement age.
Self-employed individuals face particular vulnerability since they lack employer-provided sick pay or disability benefits. Business owners in Greensboro, High Point, and surrounding communities must protect their earning capacity to sustain both personal finances and business operations.
Priority Candidates for Coverage
High-priority individuals include:
- Primary household earners with dependents
- Self-employed professionals and business owners
- Workers without employer disability coverage
- Individuals with limited emergency savings
- Those with significant ongoing financial obligations
Even workers with some employer coverage should evaluate whether that protection adequately replaces their income. Many employer plans replace only 60% of earnings and may have restrictive definitions of disability.
Young professionals often overlook this protection, assuming disability only affects older workers. However, disabilities from accidents, mental health conditions, and chronic illnesses affect people at all career stages. For families considering comprehensive protection, evaluating life insurance options alongside disability coverage creates a more complete safety net.
How Income Protection Insurance Differs From Other Coverage
Many people confuse income protection insurance with related products that serve different purposes. Understanding these distinctions helps you build appropriate coverage.
Health insurance covers medical treatment costs but does not replace lost income. You might have excellent health insurance that pays for surgery and rehabilitation, yet still face financial crisis without income during recovery months.
Workers' compensation only applies to job-related injuries and illnesses. If you develop a serious illness unrelated to work, workers' comp provides no assistance.
Critical illness insurance pays a lump sum upon diagnosis of specific conditions like cancer, heart attack, or stroke. This differs from income protection, which provides ongoing monthly payments regardless of your specific diagnosis.
Comparing Disability Insurance Types
| Coverage Type | Trigger Event | Payment Structure | Duration |
|---|---|---|---|
| Income Protection | Cannot work due to illness/injury | Monthly payments | Until recovery or max period |
| Critical Illness | Diagnosis of listed condition | One-time lump sum | Single payment |
| Accident Insurance | Accidental injury only | Fixed schedule or lump sum | Varies by policy |
| Workers' Comp | Work-related injury/illness | Weekly payments + medical | Until recovery |
The Policygenius overview of income protection insurance explains how this coverage fills gaps that other policies leave open, creating comprehensive financial protection.
Key Features That Affect Your Policy
Premium costs and coverage quality vary significantly based on specific policy features and definitions. Understanding these elements helps you make informed choices.
Own Occupation vs. Any Occupation
The disability definition in your policy determines when benefits become payable. "Own occupation" policies pay benefits when you cannot perform your specific job duties, even if you could work in another capacity. A surgeon who develops hand tremors would receive benefits under an own occupation policy, even if capable of teaching or consulting.
"Any occupation" policies only pay when you cannot perform any job for which you are reasonably qualified by education and experience. These policies cost less but provide narrower protection.
Definition comparison:
- Own occupation: Cannot perform your specific job
- Modified own occupation: Cannot perform your job for initial years, then any suitable job
- Any occupation: Cannot perform any reasonable job
Partial and Residual Disability Benefits
Quality policies include partial or residual disability riders that provide proportional benefits when you can work part-time or in a reduced capacity. These provisions recognize that recovery often happens gradually rather than all at once.
If you return to work at 50% capacity with corresponding reduced earnings, a policy with residual benefits might pay you 50% of your full disability benefit plus your actual earnings.
Cost of Living Adjustments
Inflation erodes purchasing power over time. Cost of living adjustment (COLA) riders increase your benefit amount annually based on inflation indices. While adding this feature increases premiums, it provides crucial protection during long-term disabilities.
For someone disabled at age 40 with benefits continuing to age 65, inflation could reduce the real value of fixed payments by 40% or more over 25 years.
How to Determine Appropriate Coverage Amounts
Calculating the right benefit amount requires analyzing your actual financial needs and understanding policy limitations. Most insurers limit coverage to 60-70% of gross income to maintain work incentive.
Start by listing your essential monthly expenses:
- Housing costs (mortgage/rent, insurance, taxes, utilities)
- Food and household supplies
- Transportation and vehicle costs
- Insurance premiums (health, auto, life)
- Minimum debt payments
- Essential healthcare costs
Add 10-15% cushion for unexpected expenses during disability. Compare this total to 60-70% of your current gross monthly income. The lower figure represents your realistic maximum coverage amount.
Premium Factors and Cost Management
Variables affecting your premium include:
- Your age at application (younger applicants pay less)
- Occupation and associated risk level
- Benefit amount and replacement percentage
- Elimination period length
- Benefit period duration
- Optional riders and features
- Your health and medical history
- Smoking status
You can reduce premiums by selecting longer elimination periods if you maintain adequate emergency savings to cover that gap. A 90-day elimination period instead of 30 days might reduce premiums by 20-30%.
Choosing a benefit period to age 65 instead of a five-year period increases cost but provides significantly stronger protection for working-age individuals. The Financial Ombudsman Service discussion of income protection insurance notes that many claims extend longer than policyholders initially expect.
The Application and Underwriting Process
Securing income protection insurance requires detailed disclosure of your health, occupation, and income. Insurers evaluate these factors to assess risk and determine eligibility.
Medical Underwriting
Expect to complete a comprehensive health questionnaire covering:
- Current health status and medications
- Medical history for past 5-10 years
- Family health history
- Height, weight, and lifestyle factors
- Mental health history
Depending on your age and coverage amount, insurers may require medical examinations, blood work, and physician statements. Pre-existing conditions may result in exclusions or declined coverage, though some conditions become coverable after demonstrated stability periods.
Income Verification
Insurers require proof of earnings to prevent over-insurance. Provide tax returns, W-2 forms, or business financial statements demonstrating your income level. Self-employed individuals need more extensive documentation, typically two to three years of tax returns.
The insurer calculates benefit amounts based on verified income, not your desired coverage amount. Claiming higher income than documentation supports leads to application denial or policy cancellation.
Occupation Classification
Insurers classify occupations by physical risk and earnings stability. Office professionals typically receive preferred rates, while construction workers, healthcare providers with injury risks, and workers in hazardous environments face higher premiums.
Your occupation class also affects the disability definition available. High-income professionals often qualify for true own occupation coverage, while manual laborers may only access any occupation policies.
Common Exclusions and Limitations
Reading and understanding policy exclusions prevents surprises during claims. Standard exclusions typically include:
- Disabilities resulting from war or military service
- Self-inflicted injuries
- Disabilities from commission of a crime
- Pre-existing conditions during specified lookback periods
- Normal pregnancy (though complications may be covered)
Some policies exclude or limit mental health and substance abuse claims, or cap benefits to 12-24 months for these conditions. As mental health disabilities represent a significant claim category, understanding these limitations matters considerably.
According to CHOICE’s detailed guide on income protection insurance, pre-existing condition clauses vary significantly between insurers, making careful policy comparison essential.
Filing and Managing Claims
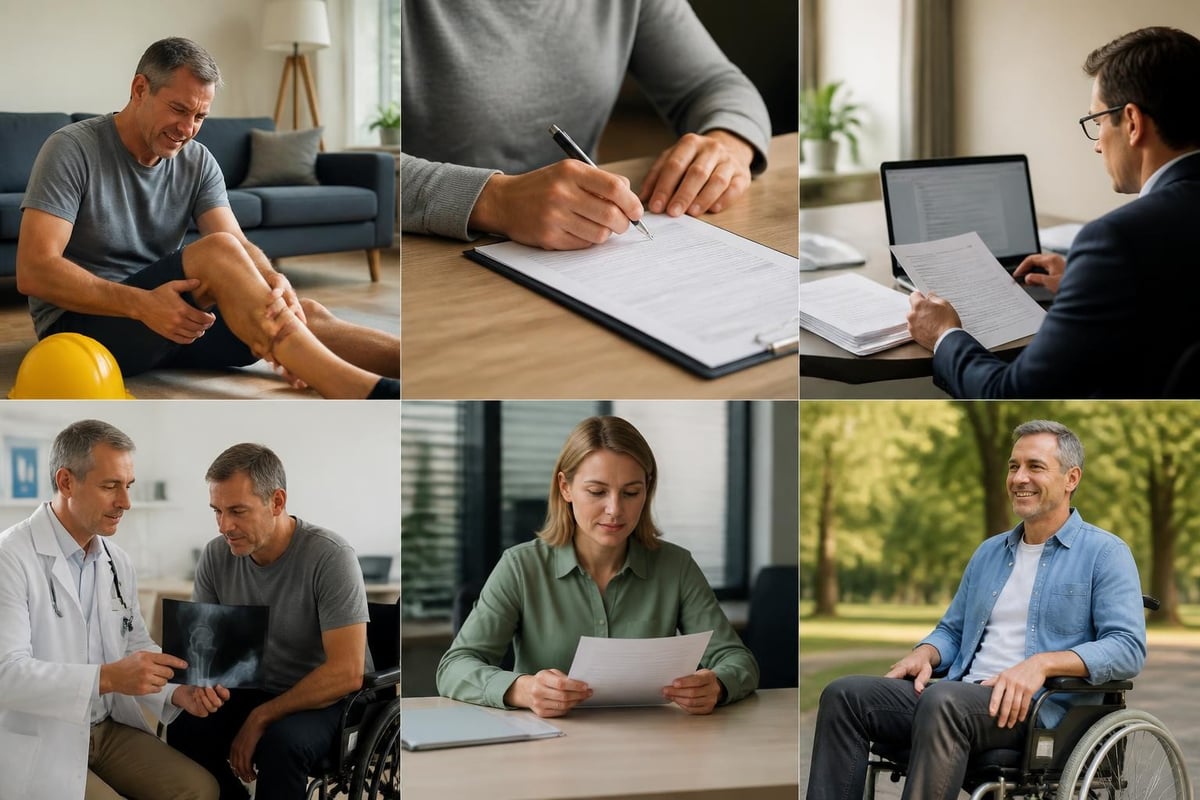
When disability strikes, understanding the claims process reduces stress during an already difficult time. Contact your insurer immediately when you become unable to work, even during the elimination period.
Claim filing steps:
- Notify your insurer as soon as disability begins
- Complete initial claim forms with detailed information
- Authorize medical providers to release records
- Submit attending physician statements
- Provide employment and income verification
- Submit periodic updates during benefit period
Maintain detailed records of all medical treatments, expenses, and communications with providers. This documentation supports your claim and expedites processing.
Ongoing Claim Requirements
Insurers require periodic proof of continuing disability. Expect to submit updated physician statements every 30-90 days. Some policies require regular examinations by independent medical evaluators chosen by the insurer.
Return-to-work programs help transition you back to employment when medically able. Many policies encourage gradual return through partial disability benefits, allowing you to test your capacity while maintaining income support.
Coordinating With Other Benefits
Income protection insurance rarely exists in isolation. Understanding how it coordinates with other benefits optimizes your total financial protection.
Social Security Disability Insurance
Social Security Disability Insurance (SSDI) provides government benefits for qualified workers. However, SSDI requires five-month waiting period and uses stringent disability criteria. Benefits average approximately $1,500 monthly as of 2026, often insufficient for middle and higher income earners.
Private income protection insurance supplements SSDI. Some policies reduce benefits dollar-for-dollar by SSDI amounts, while others use offset provisions allowing you to keep a larger portion of combined benefits.
Employer Group Coverage
Many employers provide group disability insurance as an employee benefit. Review your employer coverage carefully. Group policies often have restrictive definitions, limited benefit periods, and lower replacement percentages than individual policies.
Group coverage typically ends when employment terminates. Individual policies remain in force regardless of employment changes, providing continuity of protection throughout your career. For comprehensive planning guidance, the resources available at Moser Insurance Group help you understand how different coverages work together.
Tax Considerations for Benefits
How you pay premiums directly affects whether benefits are taxable. This tax treatment significantly impacts your actual take-home benefit during disability.
When you pay premiums with after-tax personal funds, benefits are tax-free. If your employer pays premiums or you pay with pre-tax dollars, benefits become taxable as ordinary income.
| Premium Payment Method | Benefit Tax Status | Effective Replacement Rate |
|---|---|---|
| After-tax personal funds | Tax-free | Full benefit amount |
| Employer-paid | Taxable as income | Reduced by tax rate |
| Pre-tax salary reduction | Taxable as income | Reduced by tax rate |
Consider this carefully when choosing coverage amounts. If you need $5,000 monthly after-tax income and benefits are taxable, you need a higher benefit amount to achieve that net figure after taxes.
Specialized Income Protection Options
Standard income protection insurance serves most workers well, but specialized situations may require tailored solutions. Business owners need coverage that protects not just personal income but also funds business overhead during disability.
Business overhead expense insurance pays for ongoing business costs like rent, utilities, and employee salaries while you recover. This keeps your business operational until you return or make permanent arrangements.
Key person insurance protects businesses against the loss of critical employees or owners. While technically life insurance, disability buyout coverage serves similar purposes for disabilities.
High-income professionals often need supplemental policies because insurers cap individual policy benefits, typically at $15,000-$20,000 monthly. Multi-policy strategies with different insurers overcome these limitations.
Making the Right Choice for Your Situation
Selecting appropriate income protection insurance requires honest assessment of your financial vulnerability, careful policy comparison, and professional guidance through complex features.
Start by calculating how long your emergency fund would sustain your household if your paycheck stopped today. If the answer is less than six months, income protection insurance deserves serious consideration.
Compare policies from multiple insurers, paying close attention to disability definitions, elimination periods, benefit periods, and exclusion clauses. The lowest premium rarely represents the best value when coverage quality varies significantly.
Work with insurance professionals who understand these products deeply. Disability insurance involves more complexity than many other coverages, and expert guidance helps you navigate options effectively. For residents throughout the Triad Area, personalized consultation helps match coverage to your specific circumstances and risk profile.
Contact Moser Insurance Group at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your income protection needs. You can also visit moserinsurancegroup.com to learn more about comprehensive coverage options available in Greensboro, Kernersville, High Point, Winston Salem, and surrounding communities.
The decision to secure income protection insurance represents a commitment to financial stability regardless of what health challenges the future may bring. Your earning ability deserves the same careful protection you extend to your home, vehicles, and health.
Protecting your income against unexpected disability creates essential financial security for you and your family during life's most challenging moments. Whether you need income protection insurance, Medicare guidance, or comprehensive life insurance solutions, Moser Insurance Group helps individuals and families throughout the Triad Area understand their options without pressure. Our personalized approach ensures you make confident decisions about protecting what matters most. Contact Moser Insurance Group at 336-862-1763 or moserinsurancegroup@gmail.com to discuss how we can help secure your financial future with clear guidance and expert support.
Recent Comments