

Understanding how much should life insurance cost is one of the most common questions families ask when planning their financial future. The answer depends on several personalized factors, including your age, health, coverage amount, and the type of policy you choose. While national averages provide helpful benchmarks, your actual premium will reflect your unique circumstances and needs. Whether you're protecting young children, paying off a mortgage, or ensuring your spouse can retire comfortably, knowing what influences life insurance costs helps you make informed decisions without overpaying.
Key Factors That Determine Life Insurance Costs
Life insurance pricing isn't arbitrary. Insurers use sophisticated actuarial methods to assess risk and calculate premiums. According to the American Academy of Actuaries, companies evaluate mortality risk, administrative expenses, investment assumptions, and profit margins when setting rates.
Age and Life Stage
Your age is the single most influential factor in determining premiums. Younger applicants pay significantly less because they statistically have decades before making a claim. A healthy 30-year-old might pay $25-$40 monthly for a $500,000 20-year term policy, while a 50-year-old could pay $150-$250 for identical coverage.
The difference becomes more dramatic as you age:
- Ages 20-30: Lowest premiums, often locked in for decades
- Ages 31-45: Moderate increases, still favorable rates
- Ages 46-60: Steeper pricing, especially for permanent policies
- Ages 60+: Highest term rates; whole life may be more cost-effective
Every year you delay purchasing coverage increases your premium. Families in the Triad Area often discover that locking in rates early saves thousands over the policy's lifetime.
Health Status and Medical History
Your health directly impacts how much should life insurance cost. Insurers classify applicants into rate classes ranging from Preferred Plus (best health) to Standard or Table-rated (health complications). The premium difference between rate classes can exceed 50% for the same coverage.
Common health factors that affect pricing:
- Blood pressure and cholesterol levels
- Body mass index (BMI) and weight
- Tobacco use (smokers pay 2-3 times more)
- Diabetes, heart disease, or cancer history
- Family medical history
- Prescription medications
Most carriers require a medical exam for policies above $250,000. Some simplified-issue policies skip exams but charge higher premiums to offset the additional risk. Understanding types of life insurance helps you choose between medically underwritten and simplified options.
Coverage Amount and Policy Duration
The death benefit you select directly influences your monthly cost. Doubling your coverage doesn't quite double your premium (economies of scale apply), but the relationship is close. Industry data from LIMRA’s 2024 fact sheet shows the median coverage amount has risen to $300,000 as families recognize the need for adequate protection.
Typical monthly premiums for healthy 35-year-old:
| Coverage Amount | 20-Year Term | 30-Year Term |
|---|---|---|
| $250,000 | $15-$25 | $20-$35 |
| $500,000 | $25-$40 | $35-$55 |
| $1,000,000 | $40-$70 | $60-$100 |
Term length matters considerably. A 20-year term life insurance policy costs less monthly than a 30-year term because the insurance company assumes risk for a shorter period. However, the 30-year option provides longer protection and may be more cost-effective if you need coverage into your 60s.
Policy Type: Term vs. Permanent
How much should life insurance cost varies dramatically between term and permanent policies. Term insurance provides coverage for a specific period (10, 20, or 30 years) and is significantly more affordable. Permanent insurance (whole life, universal life) lasts your entire lifetime and includes a cash value component, making it substantially more expensive.
Cost comparison for $250,000 coverage (healthy 40-year-old):
- Term (20-year): $30-$50/month
- Whole life: $250-$400/month
- Universal life: $200-$350/month
Consumer Reports recommends term insurance for most families because it delivers maximum protection at the lowest cost. Permanent policies make sense for estate planning, business succession, or lifetime coverage needs, but they require careful evaluation given their higher premiums.
Average Life Insurance Costs by Age and Gender
National averages provide useful benchmarks when estimating how much should life insurance cost for your situation. Women typically pay 20-30% less than men for identical coverage because of longer life expectancy.
Monthly Premiums for $500,000 20-Year Term
| Age | Male (Non-Smoker) | Female (Non-Smoker) | Male (Smoker) |
|---|---|---|---|
| 30 | $25-$35 | $20-$28 | $70-$90 |
| 40 | $40-$55 | $32-$45 | $130-$160 |
| 50 | $100-$135 | $80-$105 | $300-$380 |
| 60 | $240-$310 | $180-$235 | $650-$800 |
These figures represent preferred or preferred-plus rate classes for excellent health. Standard health classifications add 25-50% to these premiums. Residents in Greensboro, Kernersville, High Point, and Winston Salem see similar rates, as North Carolina doesn't significantly deviate from national pricing trends.
Smoker vs. Non-Smoker Impact
Tobacco use is one of the most significant cost factors. Smokers face premiums two to three times higher than non-smokers because of elevated health risks. If you quit smoking, most insurers allow reclassification after 12-24 months of tobacco-free living, which can save thousands over your policy's term.
Many carriers now treat vaping and nicotine replacement therapy as tobacco use. Be honest on your application-misrepresenting tobacco use can void your policy when your beneficiaries need it most.
Understanding Premium Structures and Payment Options
Beyond the factors that determine your rate, understanding how insurers structure payments helps you plan your budget effectively.
Level vs. Increasing Premiums
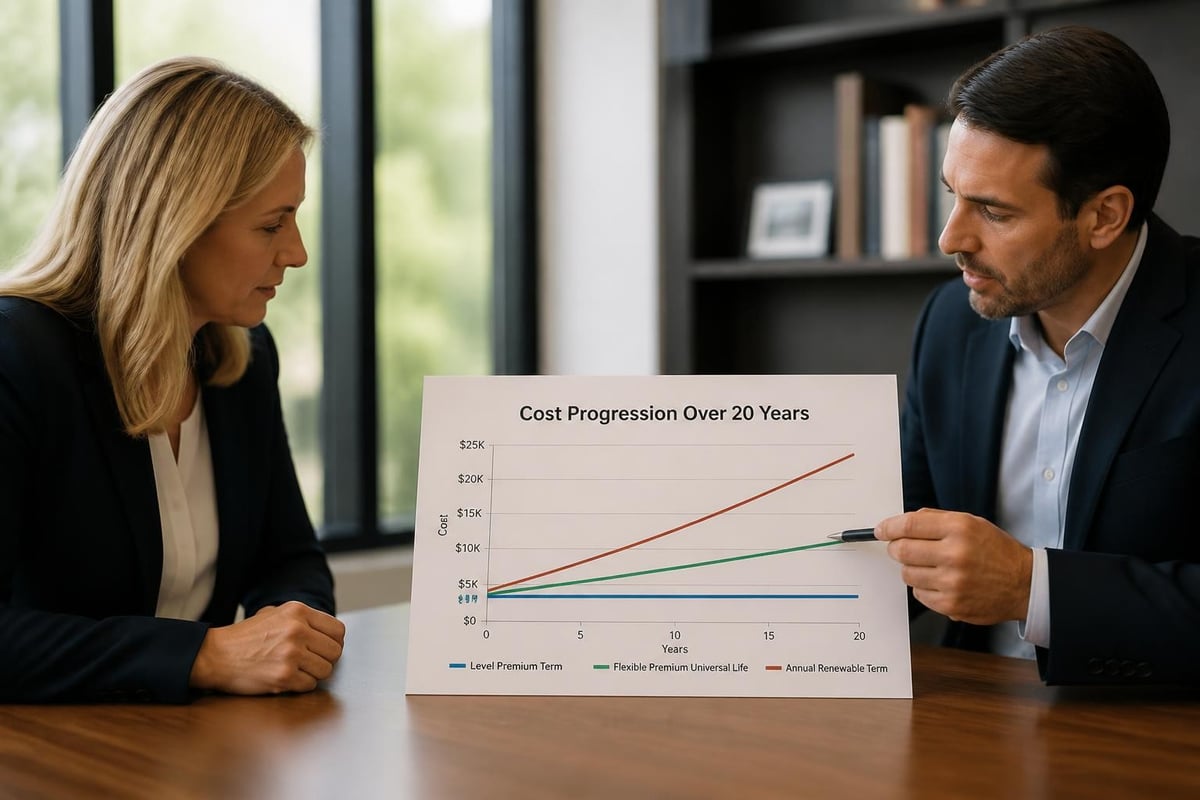
Most term policies offer level premiums that remain constant throughout the term. You'll pay the same monthly amount whether it's year one or year nineteen. This predictability makes budgeting straightforward and protects you from future rate increases.
Some permanent policies, particularly universal life, offer flexible premiums where you can adjust payments within limits. This flexibility sounds appealing but requires active management to ensure the policy doesn't lapse.
Annual renewable term policies start with low premiums that increase each year. While initially attractive, these policies become prohibitively expensive as you age and are rarely the best long-term choice.
Payment Frequency Options
Insurers typically offer multiple payment schedules:
- Monthly: Most common, convenient, but may include small processing fees
- Quarterly: Four payments annually
- Semi-annual: Two payments yearly, modest discount
- Annual: Single yearly payment, typically 3-5% cheaper overall
Paying annually saves money if you have the cash flow, but monthly payments work better for most family budgets. The key is choosing a payment schedule you can reliably maintain to prevent policy lapses.
Hidden Costs and Policy Riders
When evaluating how much should life insurance cost, don't overlook riders and additional features that increase premiums but may provide valuable protection.
Common Policy Riders and Their Costs
Accelerated death benefit riders allow you to access a portion of your death benefit if diagnosed with a terminal illness. Many carriers include this at no additional cost, but enhanced versions may add 3-5% to your premium.
Waiver of premium riders continue your coverage without payments if you become totally disabled. This typically costs 5-10% of your base premium-around $3-$7 monthly for a $500,000 policy.
Child riders provide coverage for your children (typically $10,000-$25,000 per child) for a small flat fee of $5-$10 monthly regardless of the number of children.
Guaranteed insurability riders let you purchase additional coverage at future dates without medical underwriting. These cost 10-15% of the base premium but provide valuable flexibility if your income or family size increases.
Administrative and Processing Fees
Some policies include monthly policy fees of $3-$8 that appear separate from your premium. These fees cover administrative costs and are more common with smaller policies. Ask about these fees upfront, as they proportionately impact smaller coverage amounts more significantly.
How to Reduce Life Insurance Costs
Several strategies can lower how much should life insurance cost without reducing necessary protection.
Improve Your Health Before Applying
Since health directly impacts your rate class, taking a few months to improve your health can save thousands over your policy's lifetime. Focus on:
- Losing weight to reach a healthier BMI
- Managing blood pressure and cholesterol
- Getting regular exercise
- Reducing or eliminating alcohol consumption
- Quitting tobacco entirely
Even moderate improvements can move you from Standard to Preferred classification, reducing premiums by 20-30%. For significant health improvements, consider applying after you've made sustained changes rather than accepting a higher rate now.
Choose the Right Coverage Amount
Many families overestimate their needed coverage, paying for protection they don't require. Calculate your actual need based on:
- Outstanding debts: Mortgage, car loans, credit cards
- Income replacement: Years of salary your family needs
- Future expenses: College funding, final expenses
- Existing assets: Savings, investments, employer coverage
The common rule of thumb (10-12 times your annual income) works for many families, but personalized calculation often reveals a more accurate number. Contact Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com for help determining your specific coverage needs.
Compare Multiple Carriers
Life insurance pricing varies significantly between companies. One insurer might rate your health condition more favorably than another, or specialize in your age group or occupation. Getting quotes from 3-5 carriers ensures competitive pricing.
Working with an independent agent who represents multiple companies provides access to more options than going directly to a single insurer. Independent agents can shop your application across their entire carrier network to find the best rate for your situation.
Special Considerations for Different Life Stages
How much should life insurance cost changes throughout your life as your responsibilities and health evolve.
Young Adults and New Families
Adults in their 20s and 30s enjoy the lowest premiums and should strongly consider locking in long-term rates. A $500,000 30-year term policy purchased at age 30 might cost $30-$40 monthly and provide coverage through age 60.
New parents should increase coverage to account for childcare costs, education expenses, and lost income if one parent stays home. Many young families in the Triad Area find that $500,000-$1,000,000 in coverage provides adequate protection for the cost of a streaming service subscription.
Middle-Aged Adults
People in their 40s and 50s face higher premiums but also typically have greater financial responsibilities. This is when whole life insurance becomes more competitive with term insurance, particularly if you need permanent coverage.
Consider supplementing existing employer coverage, which typically equals only 1-2 times your salary. Employer policies disappear if you change jobs, while individual policies remain in force regardless of employment.
Pre-Retirees and Seniors
Adults approaching or in retirement may need less coverage as mortgages are paid and children are independent. However, some maintain policies for:
- Estate planning and wealth transfer
- Final expense coverage (funeral, burial, estate costs)
- Leaving a legacy for grandchildren or charities
- Equating inheritances among heirs
Burial insurance policies specifically designed for final expenses typically range from $5,000-$25,000 and cost $30-$100 monthly depending on age and health.
Understanding the Tax Implications of Life Insurance
The IRS provides clear guidance on life insurance taxation, which affects the real cost of coverage.
Death Benefits Are Generally Tax-Free
Life insurance death benefits paid to beneficiaries are typically received tax-free, regardless of the amount. This tax advantage makes life insurance an efficient wealth transfer tool compared to other assets that trigger capital gains or estate taxes.
However, if your estate exceeds federal exemption limits (currently $13.61 million in 2026), life insurance proceeds may be included in your taxable estate. Proper estate planning can address this through irrevocable life insurance trusts.
Cash Value Accumulation
Permanent life insurance policies accumulate cash value that grows tax-deferred. You don't pay taxes on gains until you withdraw them, and policy loans are generally tax-free if the policy remains in force. Understanding direct recognition vs. non-direct recognition affects how policy loans impact your dividends and cash value growth.
If you surrender a permanent policy, you'll owe income tax on gains exceeding your total premium payments. This surrender cost should factor into your decision between term and permanent coverage.
Regulatory Protections and Consumer Resources
The National Association of Insurance Commissioners provides consumer resources and regulatory oversight to ensure fair pricing and claims handling. State insurance departments regulate carriers operating in North Carolina, reviewing rate filings and investigating consumer complaints.
State Guaranty Associations
Every state maintains a guaranty association that protects policyholders if their insurance company becomes insolvent. North Carolina's guaranty association covers up to $300,000 in death benefits per insured life, providing additional security for your family's protection.
This safety net means you can focus on finding the best price and features rather than worrying exclusively about carrier financial strength (though choosing well-rated insurers remains wise).
Getting Help Navigating Options
Determining how much should life insurance cost for your specific situation requires personalized analysis. Many families benefit from professional guidance to:
- Calculate appropriate coverage amounts
- Compare policy types and riders
- Navigate health underwriting requirements
- Review beneficiary designations and estate planning implications
Independent agents like Moser Insurance Group Inc serve residents throughout the Triad Area with personalized guidance on life insurance options. We explain policy features in plain language so you can make confident decisions without pressure or confusion.
Making Your Coverage Affordable
Even with moderate budgets, families can secure meaningful protection through strategic choices.
Laddering Policies
Policy laddering involves purchasing multiple term policies with different amounts and durations to match changing needs at lower total cost. For example:
- $500,000 20-year term (covers mortgage and young children)
- $300,000 30-year term (covers college expenses)
- $200,000 10-year term (covers immediate high expenses)
Total coverage starts at $1,000,000 and decreases as policies expire and your needs decline. This approach costs less than buying a single $1,000,000 30-year policy while providing appropriate coverage at each life stage.
Converting Term to Permanent
Most term policies include conversion privileges that allow changing to permanent coverage without medical underwriting. If your health declines during the term, this conversion option provides a path to lifetime coverage at standard rates rather than the higher rates you'd face applying fresh.
Conversion deadlines vary by policy (typically year 10-15 or age 65), so review your policy documents and mark important dates. This flexibility adds value even if you initially plan to maintain term coverage.
Employer Coverage Considerations
Employer-provided group life insurance offers convenience but several limitations affect long-term planning. Group coverage typically costs less per $1,000 of coverage but disappears if you change jobs or are laid off. It also rarely provides sufficient coverage (usually 1-2x salary) for families with mortgages and dependents.
Consider supplementing employer coverage with an individual policy rather than relying exclusively on group benefits. Individual policies provide portability and guaranteed premiums that employment-based coverage cannot match.
Regional Considerations for North Carolina Residents
While life insurance pricing remains relatively consistent nationwide, North Carolina residents should understand local regulatory environment and available resources.
North Carolina Insurance Department
The North Carolina Department of Insurance regulates all life insurance carriers operating in the state. They maintain resources for comparing policies, filing complaints, and verifying agent licenses at ncdoi.gov.
Local Economic Factors
The cost of living in Greensboro, High Point, Winston Salem, and Kernersville affects how much coverage families need but doesn't directly impact premium rates. However, your coverage amount should reflect local housing costs, salary replacement needs, and future expenses based on regional economics.
Moser Insurance Group Inc understands the specific needs of families throughout the Triad Area and can help you determine appropriate coverage that reflects local living costs while finding competitive rates from top carriers.
When to Review and Update Coverage
Life insurance costs become more significant if you discover your policy no longer meets your needs. Regular reviews ensure you maintain appropriate coverage throughout changing circumstances.
Life Events Triggering Review
Schedule a policy review when you experience:
- Marriage or divorce
- Birth or adoption of children
- Home purchase or mortgage refinance
- Significant salary increase
- Inheritance or large asset acquisition
- Starting a business
- Death of a spouse or dependent
These events change your coverage needs and may require adjusting your policy or purchasing additional coverage. Some riders (like guaranteed insurability) let you increase coverage without new underwriting at these milestone events.
Annual Check-Ins
Even without major life changes, reviewing your coverage annually ensures it remains aligned with your goals. Verify beneficiary designations remain current, confirm your address and contact information are updated, and assess whether your coverage amount still meets your family's needs.
Some families discover existing policies no longer fit their situation and can reduce coverage or cancel unnecessary policies, freeing budget for other financial priorities.
Common Mistakes That Increase Costs
Understanding pitfalls helps you avoid unnecessarily expensive coverage decisions.
Waiting Too Long to Apply
Every year you delay purchasing life insurance increases your premium due to age progression. A healthy 35-year-old might pay $35 monthly for coverage that costs the same person $45 monthly at age 40 and $60 monthly at age 45.
The combination of aging and potential health changes makes early purchase one of the most effective cost-control strategies. Things that make life insurance more expensive become harder to avoid as you age.
Misunderstanding Policy Types
Purchasing permanent insurance when term coverage better fits your needs wastes money. Conversely, choosing term insurance when you need lifetime coverage creates gaps in protection. Understanding each policy type's purpose prevents costly mismatches.
Term insurance excels at temporary needs (mortgage protection, income replacement during working years). Permanent insurance serves lifetime needs (estate planning, final expenses, wealth transfer).
Inadequate Coverage to Save Money
Buying too little coverage to reduce premiums defeats insurance's purpose. If your $100,000 policy leaves your family with $300,000 in unpaid mortgage and living expenses, the "savings" cost your family dearly.
Calculate your actual need, then find ways to make that coverage affordable through term insurance, policy riders, or strategic shopping rather than simply reducing your coverage amount.
Understanding how much should life insurance cost empowers you to make informed decisions that protect your family without overextending your budget. Your premium depends on your age, health, coverage amount, and policy type, but strategic choices can secure meaningful protection at affordable rates. Whether you're just starting to explore options or ready to compare specific policies, Moser Insurance Group Inc provides clear guidance tailored to your unique situation. Call us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your life insurance needs with an experienced advisor who will help you find the right coverage at the right price.
Recent Comments