
Navigating the landscape of health plans of North Carolina requires understanding the diverse options available to residents across the state. Whether you live in Greensboro, Winston Salem, High Point, Kernersville, or elsewhere in the Triad Area, choosing the right health coverage impacts your financial security and access to quality care. North Carolina offers various health insurance pathways, from Medicare for seniors to marketplace plans for working families, each with distinct eligibility requirements, benefits, and enrollment periods. This comprehensive guide examines the major health plan categories available in North Carolina, helping you make informed decisions about coverage that fits your needs and budget.
Understanding North Carolina's Health Insurance Landscape
North Carolina residents access health coverage through multiple channels, each serving different populations with unique needs. The state's health insurance ecosystem includes employer-sponsored plans, individual marketplace coverage, Medicare, Medicaid, and specialized programs for state employees.
The North Carolina State Health Plan provides comprehensive coverage for state employees, retirees, and their dependents, representing one of the largest health insurance programs in the state. This plan offers several options with varying copayments, deductibles, and network structures designed to meet diverse healthcare needs.
Recent developments have significantly expanded access to health plans of North Carolina. The state's Medicaid expansion enrolled over 400,000 residents within the first four months of implementation, demonstrating substantial unmet need for affordable coverage. Additionally, North Carolina's innovative approach to medical debt has eliminated over $6.5 billion in medical debt for more than 2.5 million residents, providing financial relief that complements health insurance coverage.
Regulatory Framework and Consumer Protections
The North Carolina Department of Insurance oversees many health insurance plans operating in the state, ensuring consumer protections and regulatory compliance. However, certain plans fall outside state regulation, as detailed in the department’s guidance on plans they do not regulate, including self-funded employer plans and certain federal programs.
Understanding which entity regulates your health plan determines where to file complaints, how disputes are resolved, and which consumer protections apply to your coverage. This regulatory framework ensures that health plans of North Carolina maintain minimum standards for benefits, claims processing, and network adequacy.
Medicare Options for North Carolina Residents
For individuals aged 65 and older, or those with qualifying disabilities, Medicare represents the primary health insurance option. Understanding when Medicare eligibility begins helps you prepare for this important transition and avoid coverage gaps.
Medicare offers several coverage pathways in North Carolina:
- Original Medicare (Parts A and B): Hospital insurance and medical insurance provided directly through the federal government
- Medicare Advantage (Part C): Private insurance plans that combine hospital and medical coverage, often including prescription drugs
- Medicare Supplement (Medigap): Policies that fill gaps in Original Medicare coverage
- Prescription Drug Plans (Part D): Standalone coverage for medications when paired with Original Medicare
Comparing Medicare Advantage and Medicare Supplement
North Carolina residents have dozens of Medicare Advantage plans available in the Triad Area, with insurers competing for enrollment through enhanced benefits like dental, vision, and fitness memberships. The choice between Medicare Advantage and Medicare Supplement depends on your healthcare needs, budget, and preferred providers.
| Feature | Medicare Advantage | Medicare Supplement |
|---|---|---|
| Monthly Premium | Often $0-$50 | Typically $100-$300 |
| Network Restrictions | Usually required | Any Medicare provider |
| Extra Benefits | Often includes dental, vision | No extra benefits |
| Maximum Out-of-Pocket | Annual limit applies | Varies by plan type |
| Travel Coverage | Limited to emergencies | Most plans cover nationwide |
The enrollment periods for Medicare require careful attention. Missing your Initial Enrollment Period can result in permanent late enrollment penalties. Moser Insurance Group Inc helps individuals navigate these critical timelines at 336-862-1763 or via email at moserinsurancegroup@gmail.com.
Marketplace Health Insurance Plans
For North Carolina residents who don't qualify for Medicare or employer coverage, the Health Insurance Marketplace provides access to private plans with potential premium subsidies based on income. Several major carriers offer coverage through the marketplace, including options from Cigna Healthcare and CareSource.
Metal Tier System Explained
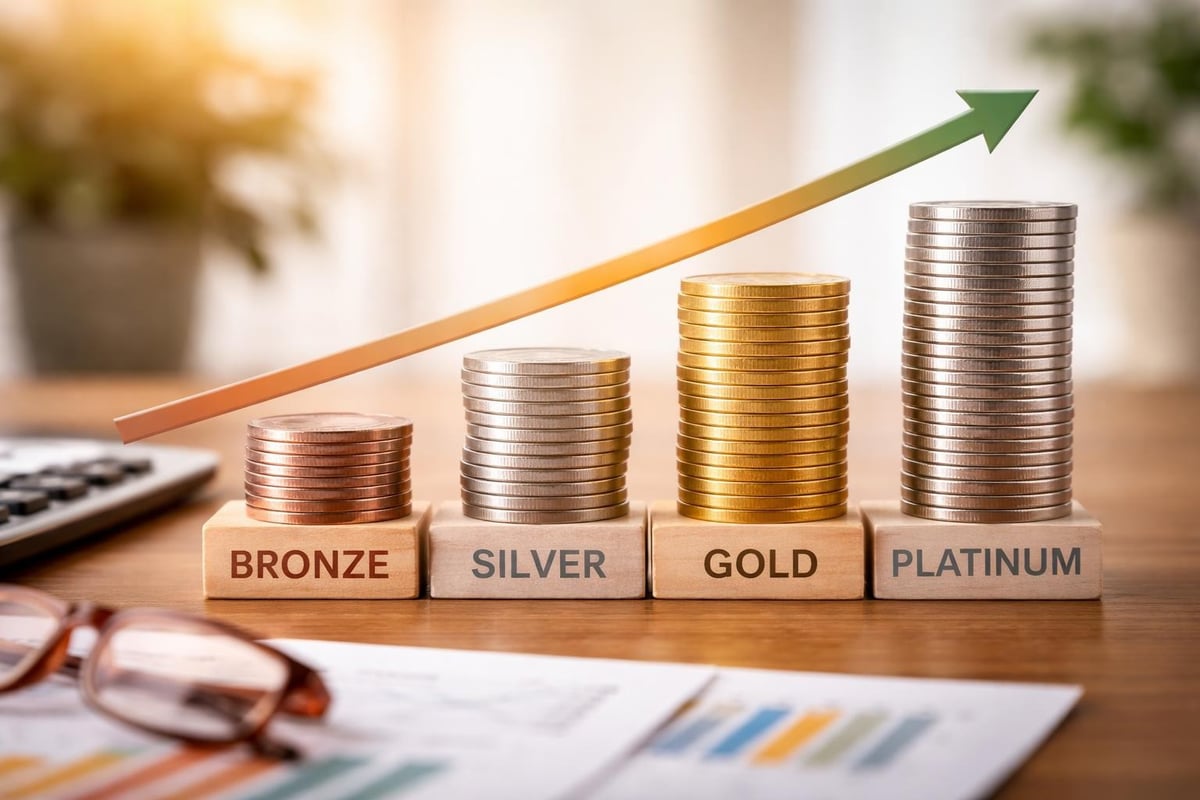
Marketplace plans in North Carolina use a metal tier system to categorize coverage levels:
- Bronze Plans: Lowest monthly premiums, highest out-of-pocket costs, covering approximately 60% of healthcare expenses
- Silver Plans: Moderate premiums and cost-sharing, covering approximately 70% of expenses, with cost-sharing reductions for eligible households
- Gold Plans: Higher premiums with lower out-of-pocket costs, covering approximately 80% of expenses
- Platinum Plans: Highest premiums and most comprehensive coverage, covering approximately 90% of expenses
The Annual Enrollment Period typically runs from November 1 through January 15 each year, though qualifying life events may trigger Special Enrollment Periods. Residents throughout Greensboro, Winston Salem, High Point, and Kernersville can compare plans and enroll through the federal marketplace or with assistance from licensed insurance agents.
Premium tax credits significantly reduce costs for eligible households. These advance payments go directly to insurance companies, lowering your monthly bill. Subsidies phase out as income increases, with eligibility extending to households earning up to 400% of the federal poverty level in many cases.
Specialized Health Plans for North Carolina Populations
Certain North Carolina residents qualify for specialized health plans designed to address specific healthcare needs. Alliance Health provides tailored coverage for behavioral health and intellectual/developmental disability services in select counties, demonstrating how health plans of North Carolina adapt to serve diverse populations.
State Employee and Retiree Coverage
The North Carolina State Health Plan serves approximately 750,000 members, making it one of the largest purchasers of healthcare services in the state. This plan offers multiple options with different cost structures:
- 70/30 Plan: Traditional option with 70% coverage after deductible, 30% member responsibility
- 80/20 Plan: Enhanced coverage with higher monthly premiums but lower out-of-pocket costs
- Consumer-Directed Health Plan: Lower premiums paired with Health Savings Account eligibility
State employees and retirees benefit from negotiated rates with healthcare providers and comprehensive prescription drug coverage. Understanding these plan differences helps members select coverage that aligns with anticipated healthcare utilization and budget constraints.
Children's Health Insurance Program (CHIP)
North Carolina Health Choice provides low-cost health coverage for children in families earning too much to qualify for Medicaid but unable to afford private insurance. This program ensures that children throughout the Triad Area have access to preventive care, dental services, and necessary treatments regardless of family income.
Impact of Healthcare Infrastructure Developments
North Carolina's healthcare landscape continues to evolve with significant infrastructure investments. The collaboration between UNC Health and Duke Health to build the state’s first standalone children’s hospital demonstrates commitment to expanding specialized care access. These developments influence health plan networks, provider availability, and quality of care for North Carolina residents.
Major healthcare systems in the Triad Area maintain partnerships with various insurance carriers, affecting which health plans of North Carolina provide in-network access to preferred facilities. When evaluating coverage options, verify that your preferred hospitals and specialists participate in the plan's network to maximize benefits and minimize out-of-pocket expenses.
Telemedicine and Virtual Care Expansion
Most health plans of North Carolina now include telemedicine benefits, a trend accelerated by recent healthcare challenges. Virtual visits provide convenient access to physicians for routine concerns, medication management, and behavioral health services. These benefits prove particularly valuable for residents in rural areas or those with transportation challenges.
Telemedicine coverage varies by plan type:
- Medicare Advantage plans typically include virtual visit options
- Marketplace plans must cover telehealth services comparable to in-person care
- State employee plans offer dedicated telemedicine programs with reduced copayments
Choosing the Right Health Plan in North Carolina
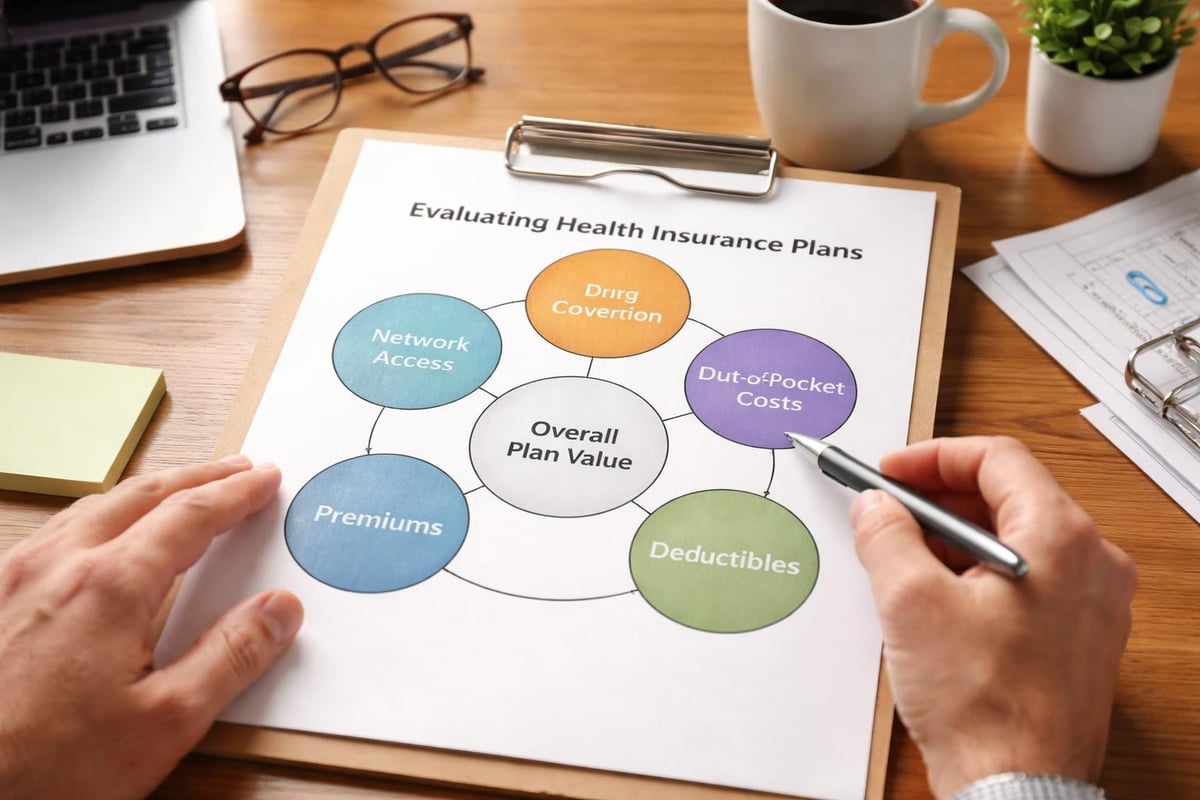
Selecting appropriate coverage requires evaluating multiple factors beyond monthly premiums. Consider your anticipated healthcare needs, preferred providers, prescription medications, and financial capacity for out-of-pocket expenses.
Essential Comparison Criteria
| Consideration | Why It Matters | How to Evaluate |
|---|---|---|
| Network Coverage | Determines provider access | Check if your doctors participate |
| Prescription Drug Coverage | Impacts medication costs | Review formulary for your drugs |
| Out-of-Pocket Maximum | Limits annual spending | Compare maximum exposure across plans |
| Premium Costs | Monthly budget impact | Factor in subsidies if eligible |
| Deductible Amount | First-dollar coverage | Balance with premium savings |
Working with experienced insurance professionals helps navigate these complex decisions. Moser Insurance Group Inc specializes in helping Triad Area residents understand their options without pressure, focusing on education that supports confident decision-making. Visit moserinsurancegroup.com or call 336-862-1763 to discuss your specific situation.
Common Enrollment Mistakes to Avoid
Many North Carolina residents make preventable errors during health insurance enrollment that lead to coverage gaps or unexpected costs:
- Missing enrollment deadlines: Resulting in waiting periods or coverage delays
- Failing to report income changes: Leading to incorrect subsidy calculations and potential repayment obligations
- Overlooking network restrictions: Causing higher costs when using out-of-network providers
- Ignoring prescription drug coverage: Resulting in substantial medication expenses
- Not reviewing plan changes annually: Missing benefit modifications or new plan options
Annual plan reviews ensure your coverage continues to meet evolving needs. Healthcare situations change, and health plans of North Carolina frequently adjust benefits, networks, and costs each year. What worked well last year may not remain the best option for the coming year.
Medicare Supplement Insurance in the Triad Area
For North Carolina seniors who choose Original Medicare, Medicare Supplement insurance fills coverage gaps that would otherwise require out-of-pocket payment. These standardized plans, labeled with letters (Plan G, Plan N, etc.), provide predictable costs and nationwide acceptance at any facility accepting Medicare.
Medigap plans offer several advantages for active retirees or those who travel frequently. Unlike Medicare Advantage plans with network restrictions, Medicare Supplement policies allow you to visit any provider accepting Medicare patients throughout the United States. This flexibility proves valuable for residents who winter in warmer climates or visit family across the country.
Timing Your Medicare Supplement Application
The optimal time to purchase Medicare Supplement coverage is during your six-month Medigap Open Enrollment Period, beginning when you're both 65 or older and enrolled in Medicare Part B. During this window, insurance companies cannot deny coverage or charge higher premiums based on health conditions.
North Carolina follows federal Medigap rules, providing standardized benefits across all carriers. Price becomes the primary differentiator, making it essential to compare multiple companies. Some insurers offer household discounts when spouses both carry policies, or lower rates for non-smokers.
For personalized guidance on Medicare coverage options and enrollment, contact Moser Insurance Group Inc at moserinsurancegroup@gmail.com. Our team helps Greensboro, Kernersville, High Point, and Winston Salem residents understand the timing, costs, and benefits of different Medicare paths.
Prescription Drug Coverage Considerations
Prescription medication costs represent a significant healthcare expense for many North Carolina residents. Understanding how different health plans of North Carolina handle pharmacy benefits helps you estimate total healthcare costs accurately.
Medicare Part D plans vary substantially in covered medications, pharmacy networks, and cost structures. Each plan maintains a formulary listing covered drugs organized into tiers, with generic medications typically costing less than brand-name alternatives. Some plans require prior authorization or step therapy for certain medications.
Comparing Prescription Drug Coverage
When evaluating drug coverage across plans, use the Medicare Plan Finder tool or request assistance from licensed insurance agents. Enter your specific medications to receive personalized cost estimates showing:
- Monthly premiums for the drug plan
- Deductibles before coverage begins
- Copayments or coinsurance for each medication
- Total estimated annual drug costs
- Coverage gap (donut hole) implications
Marketplace plans include prescription drug coverage as an essential health benefit, but formularies and cost-sharing vary. Review each plan's drug list before enrollment to ensure your medications receive coverage at acceptable costs.
Long-Term Care and Health Insurance
While health plans of North Carolina cover medical treatment, they typically exclude long-term custodial care in nursing homes or assisted living facilities. Medicare provides limited skilled nursing facility coverage following hospitalization, but not indefinite long-term care.
Planning for potential long-term care needs involves several strategies:
- Long-Term Care Insurance: Standalone policies that fund extended care services
- Hybrid Life Insurance Policies: Combining death benefits with long-term care riders
- Medicaid Planning: Structuring assets to qualify for Medicaid nursing home coverage
- Self-Funding: Reserving personal savings for potential care costs
Medicaid serves as the safety net for long-term care when personal resources become exhausted. North Carolina's Medicaid expansion improves access for eligible residents, though long-term care Medicaid maintains separate asset and income requirements.
Understanding how different insurance products work together creates comprehensive protection. Life insurance planning complements health coverage, ensuring financial security for loved ones. Moser Insurance Group Inc provides guidance across Medicare, health insurance, and life insurance, helping families develop coordinated strategies.
Healthcare Cost Management Strategies
Beyond selecting appropriate health plans of North Carolina, managing healthcare expenses requires proactive strategies that minimize waste and maximize value.
Effective Cost Control Approaches
Utilize Preventive Services: Most health plans cover annual physicals, screenings, and immunizations at no cost. These services detect health issues early when treatment is less expensive and more effective.
Choose Generic Medications: Generic drugs provide identical therapeutic benefits to brand-name versions at substantially lower costs. Ask your physician if generic alternatives exist for prescribed medications.
Understand Your Benefits: Review your plan's Summary of Benefits and Coverage document to understand what's covered, required copayments, and services needing prior authorization.
Stay In-Network: Using participating providers significantly reduces out-of-pocket costs. Verify network status before scheduling appointments, particularly with specialists.
Appeal Denied Claims: Insurance companies sometimes deny claims that should receive coverage. Understanding the appeals process and persisting through multiple levels often results in reversed decisions.
North Carolina residents benefit from medical debt relief initiatives, but preventing medical debt through appropriate insurance coverage and cost management provides better long-term financial security.
Special Enrollment Periods and Qualifying Events
While most health plans of North Carolina have defined enrollment windows, qualifying life events trigger Special Enrollment Periods allowing coverage changes outside normal timeframes.
Qualifying events include:
- Marriage or divorce: Changing family status
- Birth or adoption: Adding household members
- Loss of other coverage: Job loss or aging out of parent's plan
- Moving to a new coverage area: Relocating to different counties or states
- Changes in income: Affecting subsidy eligibility
You typically have 60 days from the qualifying event to enroll in new coverage or make plan changes. Missing this window means waiting until the next Annual Enrollment Period unless another qualifying event occurs.
For Medicare beneficiaries, certain circumstances also trigger Special Enrollment Periods, including moving outside your plan's service area or losing employer coverage. Understanding these rules prevents coverage gaps that leave you financially vulnerable.
Health Savings Accounts and Tax Advantages
High-deductible health plans paired with Health Savings Accounts (HSAs) offer tax advantages for North Carolina residents who can afford higher upfront costs. Contributions to HSAs reduce taxable income, funds grow tax-free, and qualified medical expense withdrawals incur no taxes.
HSA-eligible plans must meet specific requirements, including minimum deductibles and maximum out-of-pocket limits. These plans work well for healthy individuals with minimal healthcare needs or those who can afford to fund the HSA while covering the deductible from other sources.
Triple tax advantages make HSAs powerful savings vehicles:
- Contributions reduce current-year income taxes
- Investment growth accumulates tax-free
- Withdrawals for qualified medical expenses are tax-free
After age 65, HSA funds can be withdrawn for non-medical purposes without penalty (though income taxes apply), functioning similarly to traditional IRAs. This flexibility makes HSAs valuable retirement planning tools beyond their immediate health insurance applications.
Working with Insurance Professionals in the Triad Area
Navigating health plans of North Carolina becomes significantly easier with professional guidance from licensed insurance agents who understand the local healthcare landscape. Independent agents offer unbiased recommendations across multiple carriers, presenting options that captive agents representing single companies cannot provide.
Moser Insurance Group Inc serves Greensboro, Winston Salem, High Point, Kernersville, and the broader Triad Area with personalized insurance education. Our approach prioritizes client understanding over sales pressure, ensuring you make informed decisions aligned with your specific circumstances and goals.
Professional insurance assistance provides several advantages:
- Plan Comparison: Side-by-side analysis of available options
- Enrollment Support: Accurate application completion avoiding errors
- Claims Assistance: Help resolving coverage disputes
- Annual Reviews: Ongoing service ensuring continued plan suitability
- No Additional Cost: Commission-based compensation means no client fees
Whether you're approaching Medicare eligibility, losing employer coverage, or seeking better options during Annual Enrollment, experienced guidance helps you avoid costly mistakes and select coverage that truly meets your needs.
Looking Ahead: Future of North Carolina Health Coverage
Health plans of North Carolina continue evolving with policy changes, technological advances, and shifting demographics. The state's aging population increases Medicare enrollment while Medicaid expansion extends coverage to previously uninsured residents. These trends shape the insurance marketplace and influence available options.
Healthcare infrastructure investments, including new hospital facilities and expanded telehealth capabilities, improve access to quality care throughout the state. Insurance plans adapt their networks and benefits to incorporate these developments, providing members with enhanced service options.
Staying informed about changes affecting your coverage ensures you maintain appropriate protection as circumstances evolve. Annual plan reviews, attention to enrollment deadlines, and awareness of qualifying events help you respond effectively to both personal changes and broader market shifts.
Understanding health plans of North Carolina and selecting coverage that fits your needs doesn't have to feel overwhelming. Whether you're transitioning to Medicare, exploring marketplace options, or simply want to ensure you're making the most of your current coverage, expert guidance makes all the difference. Moser Insurance Group Inc helps individuals and families throughout the Triad Area understand their health insurance and Medicare options with clear, pressure-free education and personalized support. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your specific situation and find coverage that provides both protection and peace of mind.
Recent Comments