

Understanding how a health insurance supplement works can feel overwhelming, especially when you're trying to decide whether additional coverage makes financial sense for your situation. These supplemental policies are designed to help pay expenses that your primary health insurance doesn't fully cover-things like deductibles, copayments, coinsurance, and even services outside your network. Whether you're approaching Medicare eligibility or simply want better protection against unexpected medical bills, knowing how supplemental insurance fits into your overall coverage strategy is essential. For residents across the Triad Area, Greensboro, Kernersville, High Point, and Winston Salem, having the right guidance makes all the difference.
What Is a Health Insurance Supplement
A health insurance supplement is a secondary insurance policy that works alongside your primary health coverage to reduce out-of-pocket costs. Rather than replacing your main insurance, it fills the financial gaps that can quickly add up when you need medical care.
The most common type is Medicare Supplement Insurance, also known as Medigap. These standardized plans are specifically designed to work with Original Medicare (Parts A and B), helping beneficiaries manage the copayments, coinsurance, and deductibles that Medicare doesn't cover. According to the Centers for Medicare & Medicaid Services, Medigap policies are sold by private insurance companies but must follow federal and state laws.
Why People Choose Supplemental Coverage
The decision to purchase a health insurance supplement typically comes down to predictable costs and financial protection. Without supplemental insurance, you might face:
- High deductibles that must be paid before coverage kicks in
- Percentage-based coinsurance on expensive procedures or hospital stays
- Per-visit copayments that accumulate throughout the year
- Balance billing when seeing out-of-network providers
Supplemental policies help transform these unpredictable expenses into fixed monthly premiums, making healthcare budgeting significantly easier.
Types of Health Insurance Supplements Available
Not all supplemental policies serve the same purpose. Understanding the different categories helps you identify which type matches your needs.
Medicare Supplement Plans (Medigap)
These plans are standardized and labeled with letters-Plan A, Plan B, Plan C, Plan D, Plan F, Plan G, Plan K, Plan L, Plan M, and Plan N. Each letter represents a different combination of benefits.
Plan G has become the most popular option in 2026 because it offers comprehensive coverage while remaining cost-effective. It covers everything except the Medicare Part B deductible, which stands at $257 in 2026 according to Kiplinger’s Medicare cost breakdown.
| Plan Type | Part A Deductible | Part B Deductible | Part B Coinsurance | Foreign Travel Emergency |
|---|---|---|---|---|
| Plan A | No | No | Yes | No |
| Plan G | Yes | No | Yes | Yes |
| Plan N | Yes | No | Partial | Yes |
| Plan K | 50% | No | 50% | No |
Medicare Supplement Plans provide the predictability many retirees need when managing healthcare expenses on a fixed income.
Hospital Indemnity Plans
These supplemental policies pay fixed cash amounts directly to you when you're hospitalized, regardless of what your primary insurance covers. The cash benefit can be used for any purpose-covering deductibles, paying for transportation to treatment, or handling household bills while you recover.
Hospital indemnity plans typically pay:
- A set dollar amount per day of hospitalization
- An additional benefit for ICU stays
- A one-time admission benefit
- Coverage for outpatient surgeries in some plans
Critical Illness and Accident Supplements
Critical illness insurance provides a lump-sum payment if you're diagnosed with a covered condition like cancer, heart attack, or stroke. Accident insurance covers injuries from unexpected events, paying benefits for emergency room visits, fractures, or ambulance transportation.
These policies work particularly well for people who have high-deductible health plans and want protection against catastrophic expenses.
How Medicare Supplements Differ From Medicare Advantage
One of the most common points of confusion involves understanding the difference between Medicare Supplement Insurance and Medicare Advantage plans. These are fundamentally different approaches to Medicare coverage.
Coverage Structure
Original Medicare + Medigap means you have traditional Medicare Parts A and B, plus a private supplemental policy that helps with cost-sharing. You can see any doctor or specialist who accepts Medicare nationwide, without network restrictions.
Medicare Advantage replaces Original Medicare entirely with a private plan that bundles Part A, Part B, and usually Part D prescription coverage. These plans typically have provider networks and require referrals for specialists.
Cost Comparison
The comparison between Medigap and Medicare Advantage plans shows distinct financial patterns:
With a health insurance supplement, you pay:
- The Medicare Part B premium ($174.70 in 2026 for most beneficiaries)
- Your Medigap premium (varies by plan and location)
- Any Part D prescription drug plan premium
- Very little out-of-pocket when you receive care
With Medicare Advantage, you pay:
- The Medicare Part B premium
- Any plan premium (some plans have $0 premium)
- Copays and coinsurance each time you receive care
- An annual out-of-pocket maximum (capped at $8,850 for in-network services in 2026)
Which Approach Works Best
According to Healthline’s Medicare coverage analysis, Medigap typically makes more sense for people who:
- See doctors frequently or have chronic conditions
- Want complete freedom to choose providers
- Travel frequently and need nationwide coverage
- Prefer predictable monthly costs with minimal surprise bills
Medicare Advantage may be preferable for those who:
- Are generally healthy with minimal healthcare needs
- Don't mind network restrictions
- Want extra benefits like dental, vision, and hearing
- Prefer lower monthly premiums with higher per-service costs
Enrollment Periods and Guaranteed Issue Rights
Understanding when you can purchase a health insurance supplement is just as important as knowing which one to buy.
Medicare Supplement Open Enrollment Period
The best time to purchase Medigap is during your six-month Medigap Open Enrollment Period. This period begins the month you're 65 or older and enrolled in Medicare Part B.
During this window, insurance companies:
- Cannot deny you coverage based on health conditions
- Cannot charge higher premiums due to pre-existing conditions
- Must sell you any Medigap policy they offer
After this period ends, you may face medical underwriting, meaning insurers can review your health history and potentially deny coverage or charge significantly higher rates.
Guaranteed Issue Rights
Certain qualifying events trigger guaranteed issue rights, allowing you to purchase or switch Medigap plans without health questions. These situations include:
- Your Medicare Advantage plan is leaving Medicare or stops serving your area
- You moved out of your plan's service area
- Your employer health plan ended
- You dropped a Medicare Advantage plan within 12 months of first joining
The official Medicare & You 2026 handbook details all qualifying events and your rights during these special enrollment periods.
State-Specific Protections
Some states offer additional protections beyond federal requirements. California, for example, provides a birthday rule allowing beneficiaries to switch plans each year without underwriting. Understanding your state's specific regulations ensures you maximize your enrollment opportunities.
What a Health Insurance Supplement Covers
The exact benefits depend on which type of supplemental policy you purchase. For Medicare Supplement Insurance, coverage is standardized-meaning Plan G from one company provides identical benefits to Plan G from another company (though prices may differ).
Standard Medigap Benefits
Most comprehensive Medigap plans cover:
Part A coinsurance and hospital costs up to an additional 365 days after Medicare benefits are exhausted. This extended hospitalization benefit provides crucial protection for serious illnesses.
Part B coinsurance or copayment for doctor visits, outpatient care, and medical equipment. Without a health insurance supplement, you'd typically pay 20% of Medicare-approved amounts indefinitely.
First three pints of blood needed for medical procedures. Medicare doesn't cover these costs, but most Medigap plans do.
Part A hospice care coinsurance for end-of-life care services.
Skilled nursing facility coinsurance for days 21-100 of each benefit period.
Additional Benefits in Select Plans
Higher-tier plans like Plan G also include:
- Part A deductible coverage ($1,676 in 2026)
- Foreign travel emergency coverage (80% of costs after a $250 deductible, up to plan limits)
- Part B excess charges (when doctors charge more than Medicare-approved amounts)
What's Not Covered
It's important to note that Medicare Supplement Insurance typically does not cover:
- Prescription drugs (you need Part D)
- Dental care
- Vision care
- Hearing aids
- Long-term care
For comprehensive protection in these areas, residents in Greensboro, Winston Salem, High Point, and surrounding communities may need additional specialized policies.
Choosing the Right Supplemental Policy
Selecting a health insurance supplement requires balancing several factors unique to your healthcare needs and financial situation.
Assess Your Healthcare Utilization
Start by honestly evaluating your medical needs:
- How often do you visit doctors each year?
- Do you have chronic conditions requiring regular treatment?
- Are you taking multiple prescription medications?
- Do you prefer access to specialists without referrals?
- Do you travel frequently outside your local area?
High utilizers typically benefit more from comprehensive Medigap coverage, while healthier individuals might save money with less expensive options or even Medicare Advantage instead.
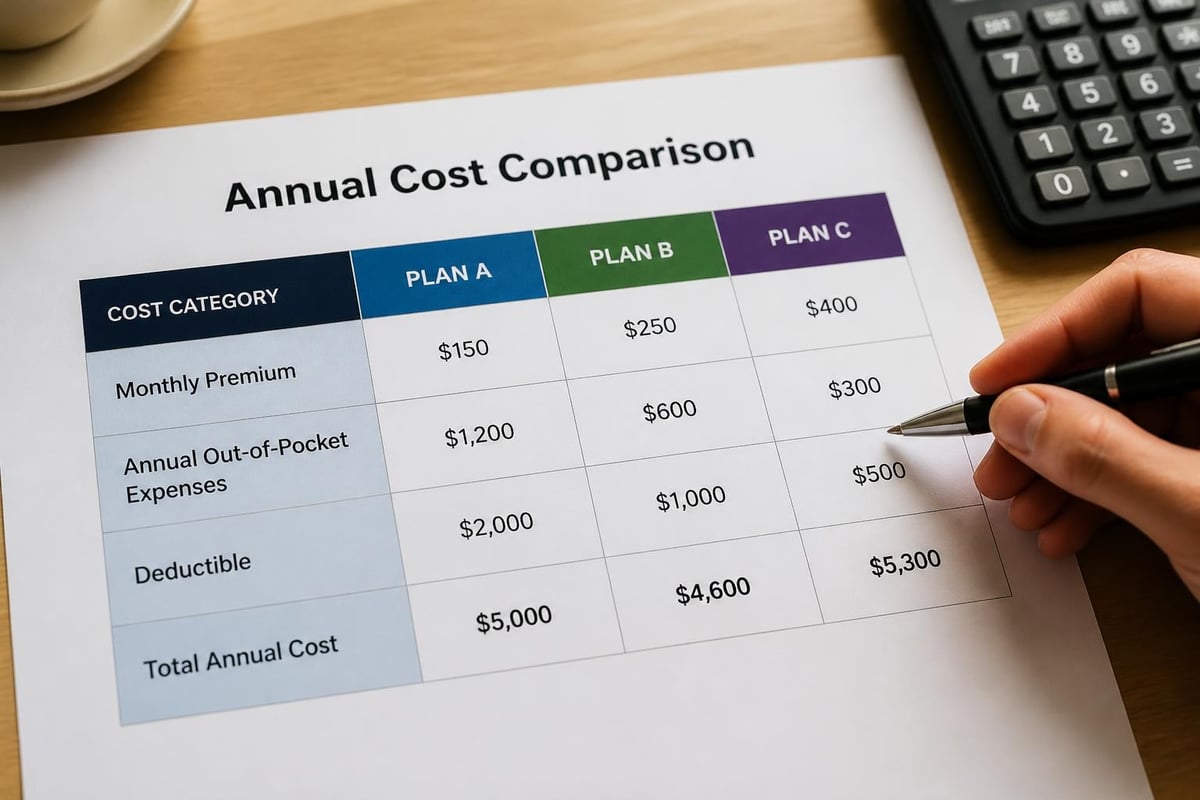
Calculate Total Annual Costs
Don't just compare monthly premiums. Calculate the total annual cost including:
- Monthly premiums × 12
- Estimated copays and coinsurance
- Deductibles you'll likely meet
- Prescription drug costs
- Out-of-pocket maximum exposure
| Scenario | Monthly Premium | Annual Premium | Typical OOP Costs | Total Annual Cost |
|---|---|---|---|---|
| High-use with Plan G | $180 | $2,160 | $500 | $2,660 |
| High-use with Plan N | $145 | $1,740 | $1,200 | $2,940 |
| Low-use with Plan N | $145 | $1,740 | $400 | $2,140 |
Consider Provider Relationships
One significant advantage of pairing Original Medicare with a health insurance supplement is provider freedom. According to the National Council on Aging’s guidance, Medigap allows you to see any doctor who accepts Medicare nationwide without worrying about networks or referrals.
This flexibility becomes especially valuable if you:
- Have established relationships with specific doctors
- Live part of the year in different states
- Want access to specialized medical centers
- Travel frequently
Review Financial Stability of Insurers
Not all insurance companies are equal. Before purchasing a health insurance supplement, research the insurer's:
- Financial strength ratings from agencies like AM Best, Moody's, or Standard & Poor's
- Customer service reputation through state insurance department complaint ratios
- Rate increase history to understand how premiums have changed over time
- Market presence in your area for local support
Plan for Rate Increases
Medigap premiums typically increase as you age and as healthcare costs rise. Understanding the pricing method helps predict future costs:
- Community-rated (same price regardless of age)
- Issue-age-rated (based on age when you buy, increases only for inflation)
- Attained-age-rated (increases as you get older)
Most plans use attained-age rating, meaning your premium rises each year even if your health doesn't change.
Common Misconceptions About Supplemental Insurance
Several myths persist about how health insurance supplement policies work. Clearing up these misconceptions helps you make better decisions.
"I'm Automatically Enrolled in a Supplement When I Get Medicare"
False. Medicare Supplement Insurance is optional coverage you must purchase separately from a private insurance company. It doesn't come automatically with Medicare enrollment.
"All Plan G Policies Are Identical, So I Should Just Buy the Cheapest"
Partially true. While benefits are standardized, customer service, rate stability, and company reputation vary significantly. The cheapest plan today might have aggressive rate increases tomorrow.
"I Can Switch Medigap Plans Anytime Without Restrictions"
Not quite. You can apply to switch anytime, but after your initial enrollment period, insurance companies can use medical underwriting to deny coverage or charge higher rates based on health conditions.
"Supplemental Insurance Duplicates Medicare Advantage"
No. These are mutually exclusive options. You cannot have both Medicare Advantage and a Medicare Supplement at the same time. It's illegal for insurance companies to sell you Medigap if you're enrolled in Medicare Advantage.
"I Don't Need a Supplement If I'm Healthy"
Health can change unexpectedly. The purpose of a health insurance supplement is to protect against unpredictable future costs, not just manage current medical needs. Waiting until you're sick means you'll likely face medical underwriting and higher rates.
How to Purchase Supplemental Coverage
The process of buying a health insurance supplement involves several key steps to ensure you make an informed choice.
Start During Your Enrollment Window
Begin researching at least two months before your 65th birthday or Part B effective date. This gives you time to:
- Compare multiple insurance companies
- Review different plan options
- Ask questions and get personalized guidance
- Submit applications without rushing
Compare Multiple Quotes
Request quotes from at least three different insurance companies. Since Medigap benefits are standardized, you're essentially shopping for the best combination of:
- Monthly premium
- Company financial strength
- Customer service reputation
- Claims processing efficiency
- Rate increase history
Review Plan Materials Carefully
Before signing, thoroughly review the:
- Outline of Coverage explaining what the plan covers
- Policy application for accuracy
- Premium schedule showing how rates may change
- Free-look period giving you 30 days to cancel for a full refund
Work With Knowledgeable Guidance
The MedPAC June 2026 report notes that beneficiaries often struggle understanding trade-offs between different coverage options. Working with an insurance professional who specializes in Medicare can help you navigate:
- Plan comparisons specific to your health needs
- Understanding guaranteed issue rights
- Coordinating effective dates with Medicare
- Avoiding coverage gaps during transitions
If you're in the Triad Area including Kernersville and surrounding communities, personalized local support makes the enrollment process significantly easier. You can reach out at 336-862-1763 or moserinsurancegroup@gmail.com for guidance tailored to your situation.
Special Considerations for Specific Situations
Certain circumstances require additional planning when it comes to supplemental insurance.
If You're Still Working Past 65
Many people delay Medicare enrollment because they have employer coverage. Understanding how your health insurance supplement timing works with employer plans is crucial:
- You can delay Part B without penalty if you have creditable coverage through active employment
- Your Medigap Open Enrollment Period begins when you actually enroll in Part B, not when you turn 65
- Employer plans and Medigap cannot be coordinated (it's one or the other)
When Moving Between States
Medigap policies are generally portable, but complications can arise:
- Not all plan types are available in every state (Massachusetts, Minnesota, and Wisconsin have different standardized plans)
- Premiums vary significantly by location
- You may need to apply for a new policy in your new state
- Medical underwriting may apply unless you have guaranteed issue rights
For Couples and Household Planning
Each person needs their own individual health insurance supplement. When planning household coverage:
- Compare premium differences between spouses (women often pay slightly higher rates)
- Consider staggered enrollment if one spouse is younger
- Evaluate whether both spouses need the same plan level
- Account for total household healthcare costs in budgeting
During Health Changes
If your health deteriorates after purchasing Medigap, your rates won't increase due to your specific conditions (though annual age-related increases still apply). However, if you try to switch plans later, you'll face medical underwriting unless you qualify for guaranteed issue.
Cost Management Strategies
While a health insurance supplement adds another premium to your monthly budget, several strategies help manage total healthcare costs effectively.
Bundle Part D Drug Coverage Wisely
Since Medigap doesn't include prescription drug coverage, you'll need standalone Part D. When evaluating total costs:
- Compare drug plans annually during the October 15 – December 7 enrollment period
- Ensure your medications are on the plan's formulary
- Consider mail-order options for maintenance medications
- Factor in the Part D deductible and coverage gap
Take Advantage of Preventive Services
Medicare covers numerous preventive services at no cost. Maximizing these benefits helps catch health issues early:
- Annual wellness visits
- Cardiovascular screenings
- Cancer screenings (mammograms, colonoscopies)
- Bone density tests
- Diabetes screenings and supplies
Consider Household Assistance Programs
If premiums strain your budget, several programs may help:
- Medicare Savings Programs (QMB, SLMB, QI) help pay Medicare premiums for qualifying low-income beneficiaries
- Extra Help assists with Part D prescription costs
- State Health Insurance Assistance Programs (SHIP) provide free counseling
Evaluate High-Deductible Options
For those comfortable with more risk, High-Deductible Plan G offers lower monthly premiums in exchange for a higher deductible ($2,800 in 2026). This works well if you:
- Are generally healthy
- Have emergency savings to cover the deductible
- Want catastrophic protection rather than first-dollar coverage
Making Coverage Work for Your Situation
A health insurance supplement serves as financial protection that gives you peace of mind when managing healthcare expenses. The right choice depends on your unique combination of health status, budget, provider preferences, and risk tolerance.
For Medicare beneficiaries, supplemental insurance often represents the difference between predictable healthcare costs and potentially devastating medical bills. The standardized nature of Medigap plans makes comparison straightforward, while the guaranteed renewable feature ensures your coverage continues as long as you pay premiums.
Whether you're approaching Medicare eligibility, currently enrolled and considering a supplement, or helping a family member navigate their options, understanding how these policies work empowers you to make confident decisions. The investment in supplemental coverage often pays for itself through reduced stress and financial predictability.
Taking time to evaluate your specific needs, compare available options, and ask detailed questions ensures you select coverage that provides the right balance of protection and affordability. In 2026, with healthcare costs continuing to rise, having comprehensive protection through a well-chosen health insurance supplement offers valuable security for your retirement years.
Understanding your supplemental insurance options shouldn't feel confusing or overwhelming. At Moser Insurance Group Inc, we specialize in helping individuals and families across the Triad Area navigate Medicare, supplemental coverage, and health insurance with clear, pressure-free guidance. Whether you're in Greensboro, Winston Salem, High Point, or Kernersville, we're here to educate and support you through every decision. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com to get personalized help finding the coverage that truly fits your needs.
Recent Comments