

Finding good term life insurance means securing affordable protection that truly fits your family's needs. With so many options available in 2026, understanding what makes a policy valuable helps you make confident decisions about coverage that will protect the people who depend on you financially. Whether you're in Greensboro, Kernersville, High Point, or Winston Salem, the right policy provides peace of mind without overwhelming your budget.
What Makes Good Term Life Insurance Stand Out
Good term life insurance delivers straightforward, affordable protection for a specific period. Unlike complex permanent policies, term coverage focuses on one essential goal: providing your family with a tax-free death benefit if something happens to you during the coverage period.
The best policies combine competitive pricing with reliable coverage and flexible options. When evaluating term life insurance, you should look for policies that offer clear terms, transparent pricing, and coverage amounts that match your actual financial obligations.
Key Features of Quality Coverage
- Affordable premiums that fit your monthly budget
- Flexible term lengths ranging from 10 to 30 years
- Guaranteed level premiums that won't increase during the term
- Convertibility options to change to permanent coverage later
- Strong financial ratings from the insurance carrier
Quality term life insurance provides coverage for a set period while charging fixed monthly premiums. If you pass away during the term, your beneficiaries receive the full death benefit tax-free.
Understanding Coverage Amounts and Term Lengths
Choosing the right coverage amount represents one of the most important decisions when purchasing good term life insurance. Your coverage should replace your income, pay off major debts, and fund future expenses like your children's education.
Calculating Your Coverage Needs
Financial experts typically recommend coverage equal to 10-15 times your annual income. However, your specific situation may require more or less based on several factors.
| Financial Factor | Typical Coverage Amount |
|---|---|
| Income replacement (10 years) | $500,000 – $750,000 |
| Mortgage balance | $200,000 – $400,000 |
| College education (2 children) | $100,000 – $200,000 |
| Final expenses and debts | $25,000 – $50,000 |
A 35-year-old parent earning $75,000 annually with two young children and a $300,000 mortgage might need $750,000 to $1,000,000 in coverage. This ensures the family can maintain their lifestyle, pay off the home, and fund education expenses.
Term length should align with your financial responsibilities. According to financial planning experts, most people choose terms between 20 and 30 years to cover the period until their children become financially independent or their mortgage is paid off.
Premium Factors That Affect Your Cost
Good term life insurance remains affordable because carriers assess your risk carefully and price policies accordingly. Understanding these factors helps you secure the best rates possible.
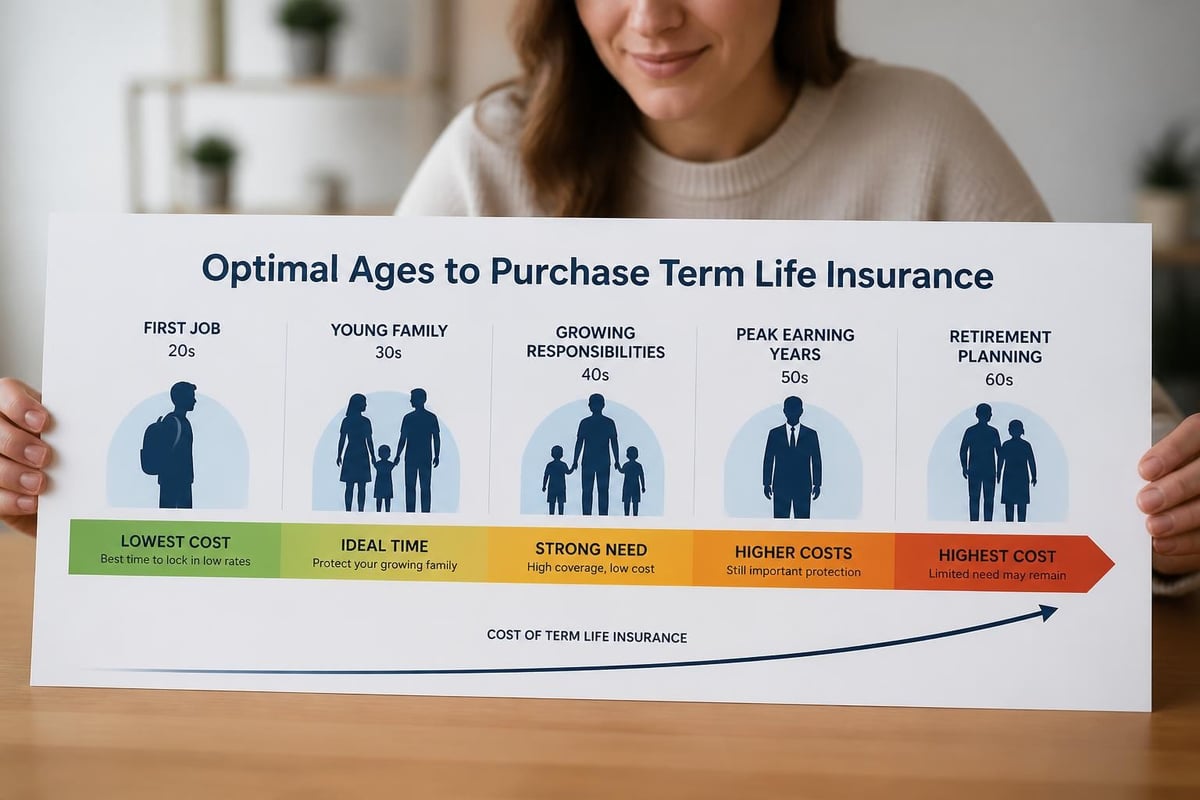
Age serves as the primary determinant of your premium. The younger you are when you purchase coverage, the lower your monthly cost. A 30-year-old non-smoker might pay $30-40 monthly for $500,000 in coverage, while a 50-year-old could pay $150-200 for the same policy.
Health status significantly impacts pricing. Insurance carriers evaluate your medical history, current health conditions, and family health history. People with well-managed conditions can still qualify for good rates, though they typically pay more than those in excellent health.
Additional Cost Considerations
- Smoking status increases premiums by 200-300% compared to non-smokers
- Occupation hazards may result in higher rates or exclusions
- Hobbies and lifestyle activities like skydiving affect pricing
- Coverage amount directly correlates with premium cost
- Term length influences total cost, with longer terms generally costing more
The structure of term life insurance premiums remains level throughout the coverage period. This predictability makes budgeting easier and prevents surprise increases during your term.
Comparing Good Term Life Insurance Options
Not all term life insurance policies offer the same value or features. Comparing options carefully ensures you get coverage that meets your needs without paying for unnecessary extras.
Policy Features Worth Evaluating
Good term life insurance includes several features beyond the basic death benefit. Look for policies offering conversion privileges, which let you change your term policy to permanent coverage without a medical exam. This flexibility proves valuable if your health changes or your needs evolve.
Accelerated death benefits allow you to access a portion of your death benefit if diagnosed with a terminal illness. This living benefit can help cover medical expenses or make your final months more comfortable financially.
Waiver of premium riders continue your coverage without requiring premium payments if you become totally disabled. While this adds to your cost, it protects your family even if you can't work.
| Feature | Standard Policy | Enhanced Policy |
|---|---|---|
| Conversion option | First 5 years | Throughout term |
| Accelerated benefits | 50% of face value | Up to 100% |
| Waiver of premium | Not included | Optional rider |
| Return of premium | Not available | Available option |
| Monthly cost (example) | $45 | $65 |
Understanding the benefits of term life insurance helps you identify which features matter most for your situation. Not everyone needs every available rider or option.
Medical Underwriting and Approval Process
Obtaining good term life insurance typically requires a medical exam and underwriting review. The process has become more streamlined in 2026, with many carriers offering simplified and accelerated underwriting for qualifying applicants.
Traditional underwriting includes a paramedical exam at your home or a local facility. A technician collects blood and urine samples, measures your height, weight, and blood pressure, and reviews your medical history questionnaire.
Simplified underwriting eliminates the medical exam for certain applicants. If you're young, healthy, and applying for moderate coverage amounts, you might qualify by answering health questions only. Approval often happens within days instead of weeks.
What Underwriters Evaluate
- Complete medical history including past surgeries and hospitalizations
- Current medications and prescriptions
- Family health history focusing on hereditary conditions
- Lifestyle factors including alcohol use and exercise habits
- Motor vehicle records and any criminal history
- Financial information to ensure coverage matches your income
The underwriting process for term versus whole life insurance remains similar, though approval criteria may differ based on policy type and coverage amount.
If you have questions about the application process or want guidance on preparing for underwriting, you can reach out to experienced agents who understand how to present your application favorably.
Common Mistakes to Avoid
Even with good intentions, people make predictable mistakes when purchasing term life insurance. Avoiding these errors saves money and ensures proper protection.
Underinsuring represents the most common problem. Many people buy only $100,000 or $250,000 in coverage because the premium seems affordable, but this amount falls short of replacing years of income or covering major debts. Run the calculations carefully before settling on a coverage amount.
Choosing the wrong term length creates gaps in coverage. If you select a 10-year term but won't pay off your mortgage for 20 years, your family faces exposure. Match your term to your longest financial obligation.
Delaying the purchase costs you money. Every year you wait, premiums increase by roughly 8-10% due to aging. A policy purchased at 35 costs significantly less than the same coverage at 45.
- Failing to compare multiple carriers and their rates
- Not reading policy exclusions and limitations carefully
- Forgetting to update beneficiaries after major life changes
- Letting policies lapse due to missed payments
- Overlooking conversion options before term expiration
Special Considerations for Different Life Stages
Good term life insurance looks different depending on where you are in life. Your coverage needs, budget constraints, and financial goals shift as you age and your circumstances change.
Young Professionals and New Parents
People in their 20s and 30s need maximum coverage at minimum cost. Term life insurance excels here because premiums remain extremely affordable while providing substantial death benefits.
A 28-year-old purchasing their first home in the Triad Area might need $500,000 in coverage for 30 years. The monthly premium could be as low as $25-35, making protection accessible even on a tight budget.
New parents should increase coverage to account for childcare costs, education expenses, and extended income replacement. Families seeking comprehensive protection often combine term policies for both spouses.
Mid-Career Families
People aged 40-50 face peak financial responsibilities. Mortgages, college tuition, retirement savings, and elderly parent care all compete for resources.
Good term life insurance at this stage means ensuring adequate coverage while managing costs. A 45-year-old might maintain a 20-year term alongside retirement accounts and other investments, creating a comprehensive financial safety net.
Pre-Retirees and Empty Nesters
As you approach 60, term insurance needs often decrease. Children are financially independent, mortgages are paid down, and retirement accounts have grown. However, coverage still matters if you have a non-working spouse or significant debts.
Some people convert term policies to permanent coverage before the term ends, especially if health issues have developed that would make new coverage expensive or difficult to obtain.
How to Get the Best Rates
Securing good term life insurance at competitive rates requires preparation and strategy. Small changes in how you apply and present your health information can result in significant savings.
Improve your health before applying. Losing 10-20 pounds, quitting smoking for at least 12 months, and managing chronic conditions better can move you into a preferred rate class, potentially saving hundreds annually.
Shop during open enrollment periods or special promotions. Some carriers offer reduced rates or waived fees during specific times of the year, particularly in January when people focus on financial planning.
Work with independent agents who represent multiple carriers. Different companies price risk differently. One carrier might offer better rates for someone with diabetes, while another specializes in competitive pricing for people with heart disease family history.
| Rate Class | Requirements | Potential Savings |
|---|---|---|
| Preferred Plus | Excellent health, no tobacco, ideal weight | 30-40% vs Standard |
| Preferred | Good health, minor conditions, no tobacco | 15-25% vs Standard |
| Standard Plus | Average health, managed conditions | 10-15% vs Standard |
| Standard | Typical health, some risk factors | Baseline pricing |
Understanding whether term life insurance is worth it depends largely on getting rates that align with your budget. For residents of Greensboro, Winston Salem, Kernersville, and High Point, working with local agents familiar with regional pricing helps secure optimal rates.
Policy Management and Maintenance
Purchasing good term life insurance represents just the beginning. Proper policy management ensures your coverage continues protecting your family as intended.
Review beneficiaries annually and after major life events like marriage, divorce, births, or deaths. Outdated beneficiary designations can result in benefits going to unintended recipients, including ex-spouses or deceased relatives.
Keep premium payments current by setting up automatic withdrawals from your bank account. A single missed payment can trigger a grace period, and continued non-payment leads to policy lapse. Reinstating lapsed coverage often requires new underwriting or higher premiums.
When to Update Your Coverage
- Marriage or partnership requires adding or increasing coverage
- New children necessitate higher death benefits
- Major purchases like homes create additional protection needs
- Significant income increases warrant coverage adjustments
- Career changes may affect both needs and affordability
Good term life insurance adapts to your changing circumstances. Many carriers allow you to increase coverage during specified periods without additional underwriting, assuming you purchase this rider initially.
Regional Considerations for Triad Area Residents
Living in the Triad Area presents unique financial considerations that affect your term life insurance needs. Understanding local factors helps you make informed coverage decisions.
Housing costs in Greensboro, Winston Salem, High Point, and Kernersville remain moderate compared to national averages, but they still represent substantial financial obligations. Your term insurance should cover your remaining mortgage balance to keep your family in their home.
Healthcare expenses factor into total coverage needs. While Medicare provides essential coverage for retirees, working families need protection against income loss that could affect their ability to pay for quality healthcare. Many local residents combine term life insurance with comprehensive health coverage to create complete financial protection.
Education planning matters significantly for families with college-bound children. North Carolina offers excellent public universities, but tuition and expenses still require substantial savings. Good term life insurance ensures education funding continues even if a parent dies unexpectedly.
For personalized guidance based on your specific situation in the Triad Area, call 336-862-1763 or email moserinsurancegroup@gmail.com to discuss your options with experienced local agents.
Evaluating Insurance Carriers
Good term life insurance comes from financially strong carriers with excellent customer service records. The insurance company's stability matters as much as the policy features and price.
Financial strength ratings from agencies like AM Best, Moody's, and Standard & Poor's indicate a carrier's ability to pay claims. Look for companies with ratings of A or better. A lower-rated carrier might offer cheaper premiums but could struggle to pay death benefits decades from now.
Claim payment history reveals how carriers treat beneficiaries. Research complaint ratios with state insurance departments and read consumer reviews about the claims process. Fast, fair claim settlement makes a significant difference when your family needs support most.
Customer service quality affects your experience throughout the policy term. Can you reach representatives easily? Do they answer questions clearly? How smoothly do they handle routine requests like beneficiary changes or address updates?
Important Carrier Criteria
- Decades of operating history demonstrating stability
- Low complaint ratios with state insurance regulators
- Multiple customer service channels including phone, email, and online portals
- Clear, accessible policy documents and contracts
- Competitive pricing without sacrificing quality
Detailed information about what term life insurance covers and how it works helps you evaluate whether specific carriers meet your standards.
Integration with Overall Financial Planning
Good term life insurance works best as part of a comprehensive financial strategy, not as an isolated purchase. Coordinating your coverage with other financial tools maximizes protection while minimizing costs.
Emergency funds complement life insurance by handling short-term financial disruptions. While life insurance replaces your income if you die, emergency savings cover job loss, major repairs, or unexpected medical bills while you're alive.
Retirement accounts eventually replace the need for term life insurance. As your 401(k), IRA, or pension grows, your family's financial vulnerability decreases. By the time you reach retirement age, your accumulated wealth may eliminate the need for life insurance entirely.
Disability insurance protects against a more common risk than premature death. You're far more likely to become disabled than to die during your working years. Good financial planning includes both life and disability coverage.
Creating a Balanced Protection Strategy
| Age Range | Life Insurance Focus | Complementary Protection |
|---|---|---|
| 25-35 | High coverage, 30-year term | Emergency fund, disability insurance |
| 35-50 | Maintain high coverage, 20-30 year term | Maximize retirement contributions, college savings |
| 50-65 | Transition to lower coverage or permanent insurance | Accelerate retirement savings, pay off debts |
Many residents of the Triad Area benefit from reviewing their complete insurance portfolio to ensure all risks are properly addressed. Visit moserinsurancegroup.com to explore how different coverage types work together to protect your family.
Tax Advantages and Financial Benefits
Good term life insurance offers several tax advantages that enhance its value beyond the basic death benefit. Understanding these benefits helps you appreciate the full financial impact of your coverage.
Death benefits are tax-free to your beneficiaries. If you have $500,000 in coverage, your family receives the full $500,000 without owing federal income tax. This tax-free transfer of wealth makes life insurance one of the most efficient ways to leave money to loved ones.
Premiums are not tax-deductible for personal policies, but they remain affordable regardless. The low cost of term insurance means the lack of tax deduction rarely affects purchasing decisions.
Estate planning advantages become relevant for larger estates. Life insurance death benefits generally pass outside your estate, avoiding probate delays and potentially reducing estate tax exposure for high-net-worth individuals.
Strategic Uses of Term Life Insurance
- Business continuity for entrepreneurs and partners
- Key person coverage protecting companies from employee loss
- Debt guarantee ensuring loans get repaid if you die
- Charitable giving naming nonprofits as beneficiaries
- Income replacement maintaining family lifestyle
Working with experienced agents helps you understand how to maximize these benefits for your unique situation. The team at Moser Insurance Group Inc provides clear guidance on structuring coverage to achieve your specific goals.
Making Your Final Decision
Choosing good term life insurance requires balancing coverage needs, budget constraints, and personal preferences. After researching options and comparing quotes, several final considerations help you commit to the right policy.
Read the entire policy document before signing. Understand exclusions, conversion options, renewal provisions, and cancellation terms. Good term life insurance comes with clear, straightforward contracts that you can understand without a law degree.
Verify all information on your application is accurate. Misrepresentations, even unintentional ones, can result in claim denials later. If you're unsure about a medical question, consult your doctor's records rather than guessing.
Start coverage immediately once you've made your decision. Every day without protection exposes your family to financial risk. Most carriers offer temporary coverage while processing your application, ensuring protection begins right away.
For personalized support throughout the decision-making process, experienced agents in Greensboro, Kernersville, High Point, and Winston Salem can answer questions and help you avoid common pitfalls. Their local knowledge combined with industry expertise ensures you get coverage that truly meets your needs.
The right term life insurance policy provides invaluable peace of mind, knowing your family will maintain financial stability even if you're no longer there to provide for them. Taking time to understand your options and choose wisely makes all the difference in the quality of protection you secure.
Finding good term life insurance that fits your budget and protects your family's future doesn't have to be complicated. With clear guidance and personalized support, you can make confident decisions about coverage that provides lasting peace of mind. Whether you're just starting to explore your options or ready to purchase a policy, Moser Insurance Group Inc helps individuals and families in the Triad Area understand their insurance choices without pressure. Call 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your specific needs and get started with protection today.
Recent Comments