

Understanding prescription drug costs under Medicare Part D can feel overwhelming, especially when terms like "coverage gap" and "donut hole" enter the conversation. For years, the donut hole medicare coverage gap created confusion and unexpected expenses for millions of Medicare beneficiaries. However, significant legislative changes in 2025 have fundamentally transformed how prescription drug coverage works, eliminating the traditional donut hole structure that previously left many seniors struggling with high medication costs during certain coverage phases.
What the Donut Hole Medicare Coverage Gap Was
The donut hole medicare terminology referred to a temporary coverage gap in Medicare Part D prescription drug plans. After beneficiaries and their drug plans spent a certain amount on covered medications, they entered a phase where they paid a higher percentage of drug costs out of pocket. This gap existed between the initial coverage period and catastrophic coverage, creating a financial burden that many retirees found difficult to navigate.
The Four Phases of Traditional Part D Coverage
Before 2025, Medicare Part D coverage operated in four distinct phases:
- Annual Deductible – The amount you paid before your plan started covering medications
- Initial Coverage Period – You and your plan shared costs according to your plan's formulary
- Coverage Gap (Donut Hole) – You paid a higher percentage until reaching the catastrophic threshold
- Catastrophic Coverage – You paid a small coinsurance or copayment for the rest of the year
| Coverage Phase | Previous Structure (Pre-2025) | Current Structure (2026) |
|---|---|---|
| Deductible | Up to $505 (2024) | Up to $590 (2026) |
| Initial Coverage | 25% coinsurance typical | 25% coinsurance typical |
| Coverage Gap | 25% of brand/generic costs | Eliminated |
| Catastrophic Coverage | 5% or small copay | Replaced with $2,000 cap |
The traditional donut hole medicare structure meant that once combined spending reached approximately $4,660 (in 2024), beneficiaries entered the coverage gap. They remained responsible for 25% of drug costs until their out-of-pocket spending reached $7,400, at which point catastrophic coverage began.
How the 2025 Elimination Changed Everything
The Inflation Reduction Act fundamentally restructured Medicare Part D prescription drug coverage, eliminating the donut hole entirely starting in 2025. This legislative change replaced the complex four-phase system with a simpler structure that includes an annual out-of-pocket maximum of $2,000.
The New $2,000 Annual Cap
Beginning in 2025 and continuing through 2026, Medicare beneficiaries no longer face the uncertainty of the coverage gap. Instead, once you've paid $2,000 in out-of-pocket prescription drug costs during the calendar year, your plan covers 100% of covered medications for the remainder of the year.
Key benefits of this change include:
- Predictable maximum annual prescription costs
- No coverage gap where costs suddenly increase
- Protection against catastrophic medication expenses
- Simplified cost structure that's easier to understand
For individuals and families navigating Medicare health plans in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, this change represents significant financial relief, especially for those managing chronic conditions requiring expensive medications.
Understanding Your Current Prescription Drug Costs
Even with the elimination of the traditional donut hole medicare gap, understanding how your Part D plan calculates costs remains essential. The deductible and initial coverage period still exist, though the structure has been simplified.
What Counts Toward Your Out-of-Pocket Maximum
Costs that count:
- Your annual deductible payments
- Coinsurance and copayments during initial coverage
- What you pay for covered brand-name drugs
- What you pay for covered generic drugs
Costs that don't count:
- Your monthly premium
- Non-covered medications
- Drugs purchased outside your plan's network
- Costs for medications not on your plan's formulary
The $2,000 cap applies only to out-of-pocket spending on covered medications. This distinction matters when planning your medication budget for the year.
Medicare Advantage Plans and Prescription Coverage
Many beneficiaries in the Greensboro area and throughout North Carolina choose Medicare Advantage plans that include prescription drug coverage. These top Medicare Advantage plans must follow the same Part D rules, including the $2,000 out-of-pocket maximum.
Medicare Advantage plans that include prescription coverage were also affected by the donut hole before its elimination. Now, these plans offer the same protections as standalone Part D plans, ensuring comprehensive coverage without unexpected gaps.
Comparing Coverage Options
| Plan Type | Prescription Coverage | Out-of-Pocket Max | Additional Benefits |
|---|---|---|---|
| Original Medicare + Part D | Separate Part D plan required | $2,000 (drugs only) | Requires separate policies |
| Medicare Advantage with Part D | Included in plan | $2,000 (drugs) + plan maximum | Often includes dental, vision, hearing |
| Medicare Advantage without Part D | Must add standalone Part D | Varies by plan | May include other benefits |
Understanding these differences helps you make informed decisions about which coverage type best suits your needs. If you're exploring options in High Point or Winston Salem, comparing plan details becomes crucial for maximizing your benefits.
Strategies to Minimize Prescription Drug Costs
Even with the $2,000 annual cap protecting you from catastrophic expenses, smart strategies can help you minimize what you pay before reaching that threshold.
Generic Medication Options
Generic medications typically cost significantly less than brand-name alternatives. When clinically appropriate, choosing generics can dramatically reduce your annual prescription spending. The changes to Medicare Part D coverage make it easier to afford necessary medications regardless of which version you need.
- Ask your doctor about generic alternatives for all new prescriptions
- Review your current medications annually with your healthcare provider
- Check if your plan offers lower copays for preferred pharmacies
- Consider mail-order pharmacy options for maintenance medications
- Use manufacturer copay assistance programs when available for brand-name drugs
Timing and Planning Considerations
The $2,000 cap resets every January 1st. If you anticipate high medication costs, understanding how timing affects your expenses can help with financial planning.
Some beneficiaries may benefit from scheduling expensive treatments or procedures strategically. However, never delay necessary medical care solely for financial reasons. Instead, work with your healthcare team and insurance advisor to develop a comprehensive plan.
Extra Help Programs for Lower-Income Beneficiaries
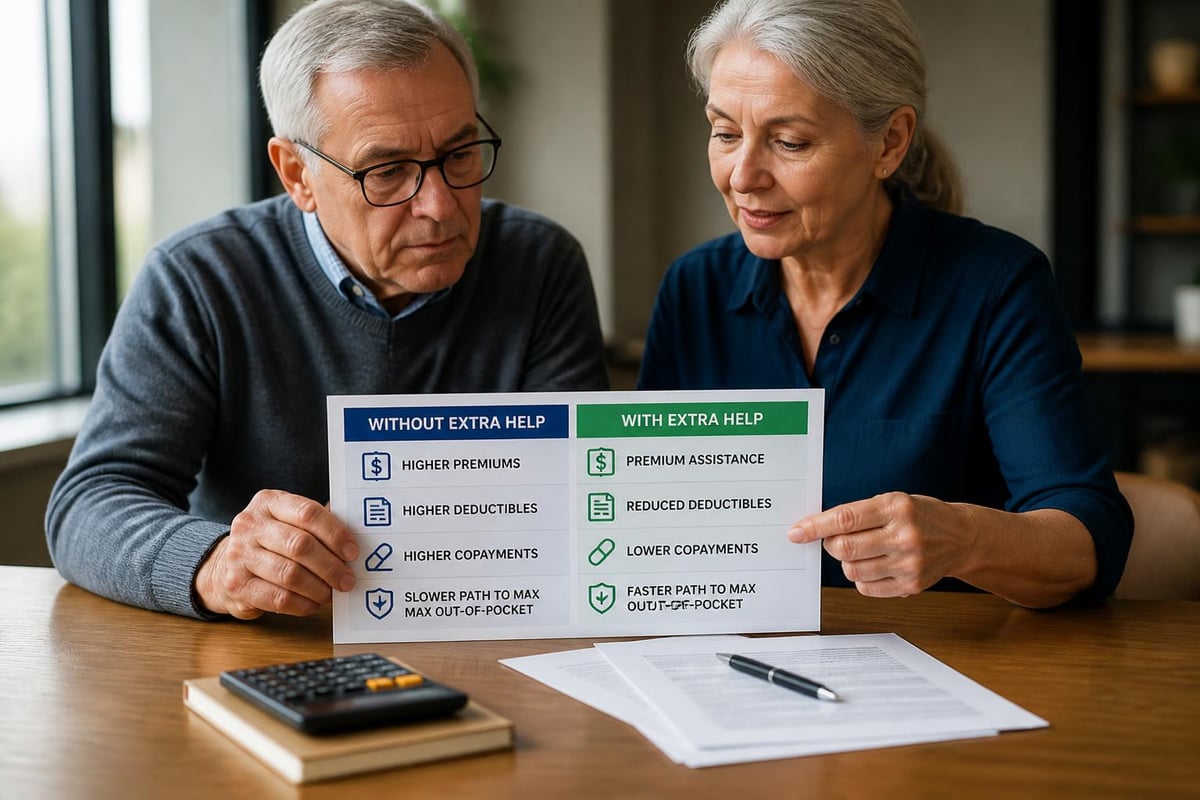
The Extra Help program (also called the Low-Income Subsidy or LIS) provides assistance with Medicare prescription drug costs for qualifying beneficiaries. This program has become even more valuable following the restructuring of Part D coverage.
Eligibility requirements for 2026:
- Income below $23,265 for individuals or $31,435 for married couples
- Resources less than $17,220 for individuals or $34,360 for couples
- These limits may be higher in Alaska and Hawaii
Those qualifying for Extra Help receive reduced or eliminated premiums, deductibles, and copayments. The program significantly lowers the threshold at which you reach the $2,000 out-of-pocket maximum.
What Changed Between 2024 and 2026
The elimination of the traditional donut hole medicare gap represents the most significant change, but several other improvements also took effect.
Year-by-Year Implementation
The transition away from the coverage gap occurred through phased implementation:
2024: The coverage gap still existed but with reduced cost-sharing compared to previous years
2025: Complete elimination of the coverage gap; introduction of the $2,000 annual cap
2026: Continued implementation with adjusted thresholds reflecting annual increases
Additionally, the Inflation Reduction Act capped insulin costs at $35 per month for Medicare beneficiaries, regardless of the type or amount of insulin needed. This change provides particular relief for diabetes patients who previously faced substantial monthly medication expenses.
Impact on Monthly Premiums
Some beneficiaries worry that eliminating the coverage gap might increase monthly Part D premiums. While premiums do vary by plan and region, the overall structure provides better financial protection. The $2,000 annual maximum creates certainty that wasn't possible under the previous system.
For residents of Kernersville and surrounding areas, comparing plan premiums alongside coverage details ensures you select the most cost-effective option for your specific medication needs.
How to Choose the Right Part D Plan in 2026
Selecting an appropriate prescription drug plan requires careful evaluation of your medication needs, preferred pharmacies, and budget considerations.
Essential Factors to Review
Formulary coverage – Verify that your current medications appear on the plan's formulary and check which tier they occupy. Lower-tier medications typically have lower copayments.
Preferred pharmacies – Many plans offer reduced copayments at preferred pharmacy networks. Confirm your local pharmacy participates in your chosen plan's preferred network.
Monthly premiums – Balance premium costs against your anticipated prescription expenses. A higher premium might save money overall if you take expensive medications regularly.
Mail-order options – For maintenance medications, mail-order pharmacies often provide 90-day supplies at reduced costs compared to retail pharmacies.
| Evaluation Factor | Questions to Ask | Why It Matters |
|---|---|---|
| Drug Coverage | Are all my medications covered? | Ensures you won't pay full price |
| Tier Placement | What tier are my drugs on? | Affects your copayment amounts |
| Pharmacy Network | Is my pharmacy preferred? | Can reduce costs significantly |
| Prior Authorization | Do any drugs require approval? | Affects access and timing |
Working with experienced insurance professionals helps navigate these decisions. At Moser Insurance Group Inc, we specialize in helping individuals throughout the Triad Area understand their options without pressure or confusion.
Medicare Supplement Plans and Prescription Coverage
It's important to understand that Medicare Supplement Plans (Medigap) do not include prescription drug coverage. If you choose a Medigap policy, you'll need to enroll in a separate Part D plan to access prescription benefits and the $2,000 annual cap protection.
The combination of Medigap and Part D provides comprehensive coverage but requires coordinating two separate policies. This differs from Medicare Advantage plans that bundle hospital, medical, and often prescription coverage into one plan.
Coordinating Multiple Policies
Managing both Medigap and Part D requires understanding how each policy functions:
- Medigap covers gaps in Original Medicare (Parts A and B) like deductibles and coinsurance
- Part D specifically addresses prescription drug coverage
- Neither automatically includes the other's benefits
This structure offers flexibility but requires more active management than all-in-one Medicare Advantage plans. Consider your comfort level with managing multiple policies when deciding between these approaches.
Common Misconceptions About the Coverage Gap Elimination
Despite widespread information about the donut hole medicare elimination, several misconceptions persist among beneficiaries.
Misconception #1: "I'll never pay more than $2,000 for healthcare"
The $2,000 cap applies only to Part D prescription drug costs. Medical expenses, hospital stays, and other healthcare services count toward different maximums or may not have caps at all under Original Medicare.
Misconception #2: "All medications are covered until I reach $2,000"
Only medications on your plan's formulary count toward the out-of-pocket maximum. Non-covered drugs don't contribute to this threshold, and you'll pay full price for them.
Misconception #3: "The donut hole still exists in some plans"
Federal law eliminated the coverage gap across all Medicare Part D plans starting in 2025. No legitimate Part D plan can include a coverage gap structure.
Misconception #4: "Monthly premiums count toward the $2,000 cap"
Your monthly Part D premium never counts toward out-of-pocket spending calculations. Only what you pay at the pharmacy for covered medications contributes to reaching the maximum.
Planning for 2027 and Beyond
Medicare prescription drug coverage will continue evolving. The changes implemented through 2025 established a foundation, but annual adjustments to deductibles, premiums, and formularies remain inevitable.
Annual Enrollment Period Strategy
Each year during the Annual Enrollment Period (October 15 through December 7), review your Part D coverage:
- List all current medications and dosages
- Check if your plan's formulary changed for the upcoming year
- Compare total estimated costs across available plans
- Verify your preferred pharmacy remains in-network
- Enroll in a new plan if better options exist
Staying proactive during this period ensures you maintain optimal coverage aligned with your current health needs and medication requirements.
Medication Changes Throughout the Year
If your doctor prescribes new medications during the year, verify your Part D plan covers them. If not, you have options:
- Request a formulary exception from your plan
- Ask your doctor about covered alternatives
- Switch plans during the next enrollment period
- Access patient assistance programs if available
Never discontinue prescribed medications without consulting your healthcare provider. Financial concerns about coverage should prompt conversations with both your doctor and insurance advisor, not independent decisions to skip necessary treatments.
Getting Expert Guidance in the Triad Area
Navigating Medicare prescription drug coverage, understanding the elimination of the donut hole medicare gap, and selecting appropriate plans requires expertise. Making uninformed decisions can result in unnecessary costs or inadequate coverage.
For personalized assistance in Greensboro, Kernersville, High Point, Winston Salem, and throughout the Triad Area, professional guidance makes a significant difference. Whether you're new to Medicare or reviewing existing coverage, expert support helps you understand your options clearly.
Contact Information:
- Phone: 336-862-1763
- Email: moserinsurancegroup@gmail.com
- Website: moserinsurancegroup.com
Professional insurance advisors can compare multiple plans, explain complex coverage details, and help you make confident decisions without pressure. This personalized approach ensures your prescription drug coverage aligns with your specific medication needs and budget.
Understanding Your Rights and Protections
Medicare beneficiaries enjoy specific rights and protections regarding prescription drug coverage. Understanding these rights helps you advocate for appropriate care and resolve coverage disputes.
Coverage Determination and Appeals
If your Part D plan denies coverage for a medication, you have the right to request a coverage determination. Your doctor can provide supporting documentation explaining medical necessity for non-formulary drugs or those requiring prior authorization.
The appeals process includes multiple levels:
- Redetermination by your plan
- Reconsideration by an independent review entity
- Hearing before an administrative law judge
- Medicare Appeals Council review
- Federal court review for qualifying cases
Most coverage disputes resolve at early stages when appropriate documentation supports medical necessity.
Transition Fills and Emergency Coverage
When switching Part D plans, you typically receive a temporary supply of non-formulary medications (transition fill) while working with your doctor to find covered alternatives. This protection prevents treatment interruptions during plan transitions.
Emergency situations may also warrant coverage for medications not typically covered by your plan. Understanding these protections ensures continuous access to necessary treatments.
Understanding the elimination of the donut hole medicare coverage gap and the new $2,000 annual cap helps you plan for prescription costs with confidence. These changes represent substantial improvements in Medicare Part D coverage, providing financial protection that wasn't available under the previous system. At Moser Insurance Group Inc, we help individuals and families throughout the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, understand Medicare options with clear guidance and personalized support. Whether you need help comparing Part D plans, understanding Medicare Made Easy, or navigating your prescription benefits, our team provides expert assistance without pressure. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to make confident insurance decisions based on your unique needs.
Recent Comments