

When homeowners think about protecting their families from financial hardship, mortgage protection often tops the list of concerns. Decreasing mortgage life insurance offers a specific solution designed to align coverage with outstanding loan balances. This specialized insurance product provides peace of mind by ensuring that if something happens to you, your family won't face the burden of mortgage payments alongside their grief. Understanding how this coverage works, who benefits most from it, and how it compares to other life insurance options can help you make informed decisions about protecting your home and loved ones.
What Is Decreasing Mortgage Life Insurance and How Does It Work
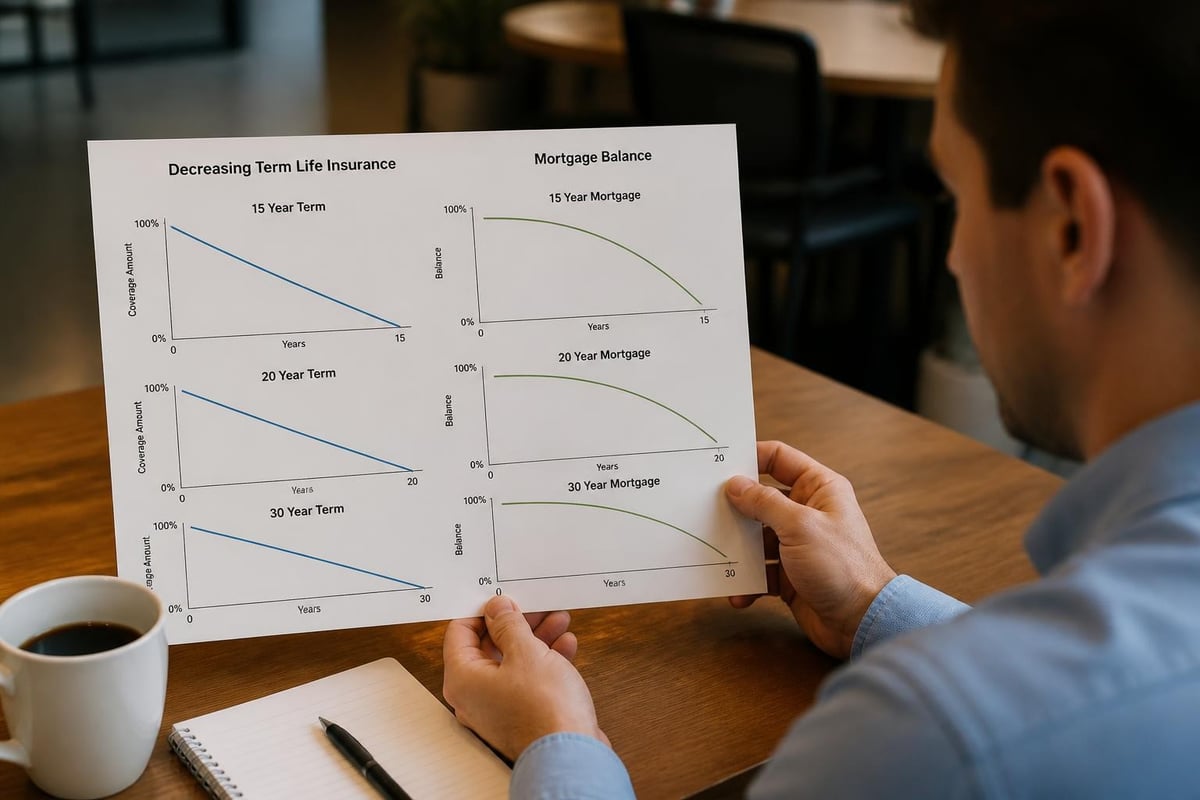
Decreasing mortgage life insurance is a type of term life insurance where the death benefit reduces over time according to a predetermined schedule. The policy is specifically designed to match the declining balance of your mortgage as you make payments over the years.
Unlike traditional level term life insurance that maintains the same death benefit throughout the policy term, decreasing mortgage life insurance provides maximum coverage when your mortgage balance is highest. As you pay down your principal, the coverage amount decreases proportionally.
Key characteristics of this coverage include:
- Fixed premium payments that remain the same throughout the policy term
- Death benefit that decreases on a set schedule, typically annually
- Coverage terms that match common mortgage lengths (15, 20, or 30 years)
- Beneficiary designation that can pay directly to the lender or to your family
The concept is straightforward: your mortgage represents your largest debt, and as that debt shrinks, you need less insurance to cover it. According to recent insurance industry analysis, this type of policy can be more affordable than level term insurance because the insurance company's risk decreases over time.
The Mechanics Behind Coverage Reduction
The reduction schedule in decreasing mortgage life insurance follows a predictable pattern that mirrors typical mortgage amortization. Most policies decrease the death benefit annually, though some adjust monthly or quarterly.
For example, if you purchase a $300,000 policy with a 30-year term, the coverage might decrease by approximately $10,000 per year. By year 15, your coverage would be around $150,000, assuming a linear reduction schedule.
However, actual mortgage balances don't decrease linearly because of how interest works. In the early years of your mortgage, most of your payment goes toward interest rather than principal. This means your actual loan balance may decrease more slowly than your insurance coverage in the initial years.
Who Benefits Most From Decreasing Mortgage Life Insurance
This specialized coverage makes the most sense for specific financial situations and life stages. Understanding whether you fall into these categories can help you determine if it's the right choice.
Primary candidates include:
- First-time homebuyers with limited budgets who want affordable protection
- Young families with significant mortgage debt and minimal savings
- Individuals with declining debts beyond mortgages, such as business loans
- People who view their mortgage as their primary financial obligation
- Homeowners who don't need additional coverage beyond mortgage protection
The comparison between decreasing and level term insurance reveals that decreasing policies typically cost 10-30% less than comparable level term policies. For families in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, this cost savings can make the difference between having coverage and going uninsured.
When Decreasing Coverage Doesn't Make Sense
Despite its benefits, decreasing mortgage life insurance isn't the optimal choice for everyone. Several scenarios suggest that alternative coverage might serve you better.
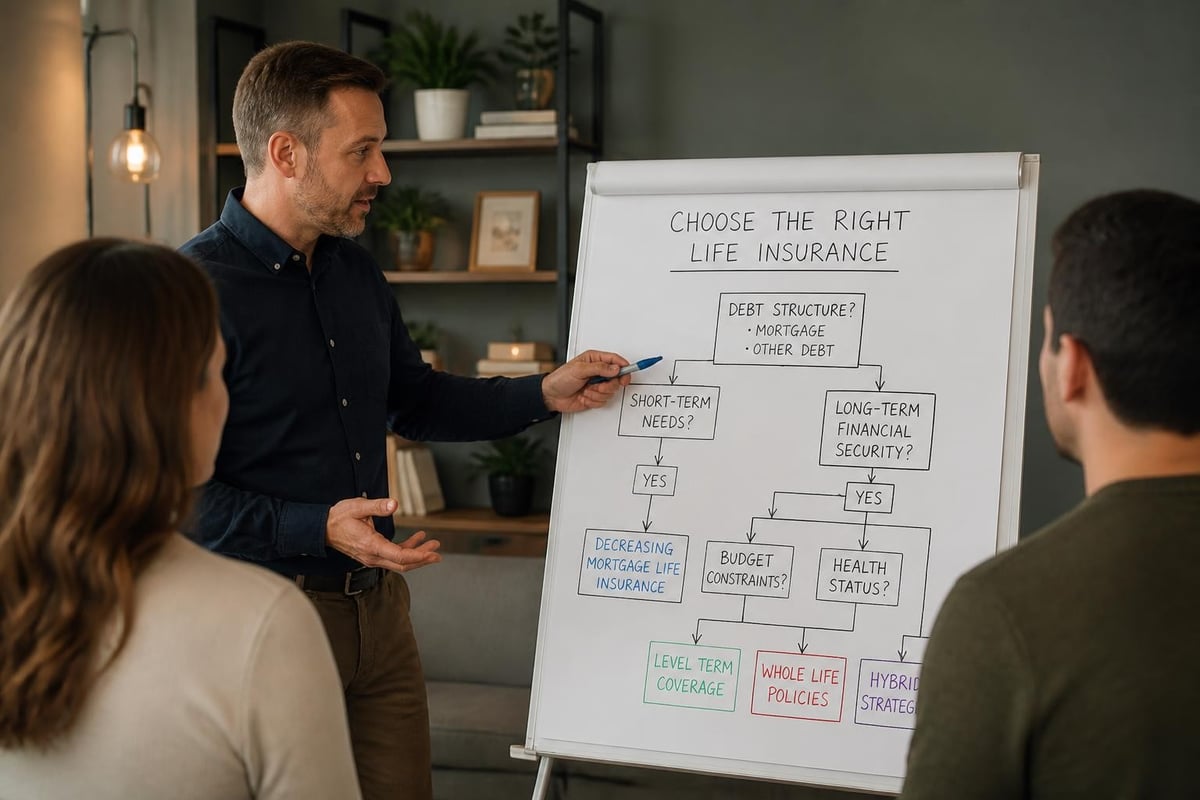
If you have multiple financial obligations beyond your mortgage, such as children's education expenses, income replacement needs, or estate planning goals, level term life insurance provides more comprehensive protection. The fixed death benefit ensures your beneficiaries receive the full coverage amount regardless of when you pass away.
Additionally, if you plan to refinance your home, move to a different property, or have variable income that might affect payment schedules, the inflexibility of decreasing coverage could create coverage gaps. As detailed in mortgage protection guides, the policy's declining benefit may not align with your actual debt if your financial circumstances change.
Comparing Decreasing Mortgage Life Insurance to Other Options
Understanding how decreasing mortgage life insurance stacks up against alternatives helps clarify whether it's your best choice. Each type of coverage offers distinct advantages and limitations.
| Coverage Type | Death Benefit | Premium | Flexibility | Best For |
|---|---|---|---|---|
| Decreasing Term | Reduces over time | Fixed, lower cost | Limited | Mortgage-only protection |
| Level Term | Remains constant | Fixed, moderate cost | High | Multiple financial needs |
| Whole Life | Remains constant + cash value | Higher, fixed | Very high | Lifetime coverage goals |
| Mortgage Life (Lender) | Pays lender directly | Fixed | Very limited | Simplified underwriting needs |
Term Life Insurance provides significantly more versatility than decreasing coverage. With level term, your beneficiaries receive the full death benefit whether you pass away in year one or year twenty-nine, giving them maximum financial flexibility to address immediate needs, pay off debts, or invest for their future.
The True Cost Comparison
While decreasing mortgage life insurance appears cheaper upfront, calculating the actual value requires examining what you're paying per dollar of coverage over the policy's lifetime.
Consider a 40-year-old non-smoking male purchasing a 30-year policy with an initial $250,000 death benefit. A decreasing term policy might cost $35 monthly, while a level term policy costs $45 monthly. Over 30 years, the decreasing policy costs $12,600 versus $16,200 for level term, a difference of $3,600.
However, the level term policy provides $250,000 in coverage throughout the entire term. The decreasing policy only averages $125,000 in coverage over that same period. On a per-dollar basis, you're actually getting less value despite the lower premium.
According to insurance product analysis, this trade-off makes sense only if you're absolutely certain your sole insurance need is mortgage coverage and you have other assets to support your family's broader financial needs.
Key Considerations Before Purchasing Decreasing Coverage
Several important factors deserve careful evaluation before committing to decreasing mortgage life insurance. These considerations can prevent costly mistakes and ensure the coverage serves its intended purpose.
Beneficiary Designation and Payout Structure
One critical distinction involves who receives the death benefit. Some decreasing mortgage life insurance policies pay directly to your mortgage lender, while others pay your designated beneficiaries.
Policies that pay lenders directly:
- Simplify the claims process
- Ensure the mortgage gets paid off
- Remove decision-making burden from grieving families
- Limit flexibility for other pressing needs
Policies with family beneficiaries:
- Provide complete control over fund usage
- Allow for strategic debt management decisions
- Enable beneficiaries to invest instead of pay off low-interest debt
- Require responsible financial management from survivors
When working with families throughout Winston Salem and High Point, we often recommend beneficiary-controlled policies because they offer greater financial flexibility. Your family might decide that keeping a low-interest mortgage and investing the insurance proceeds makes more financial sense than immediately paying off the loan.
Medical Underwriting and Approval Requirements
The application process for decreasing mortgage life insurance varies by provider and policy type. Understanding these requirements helps set realistic expectations.
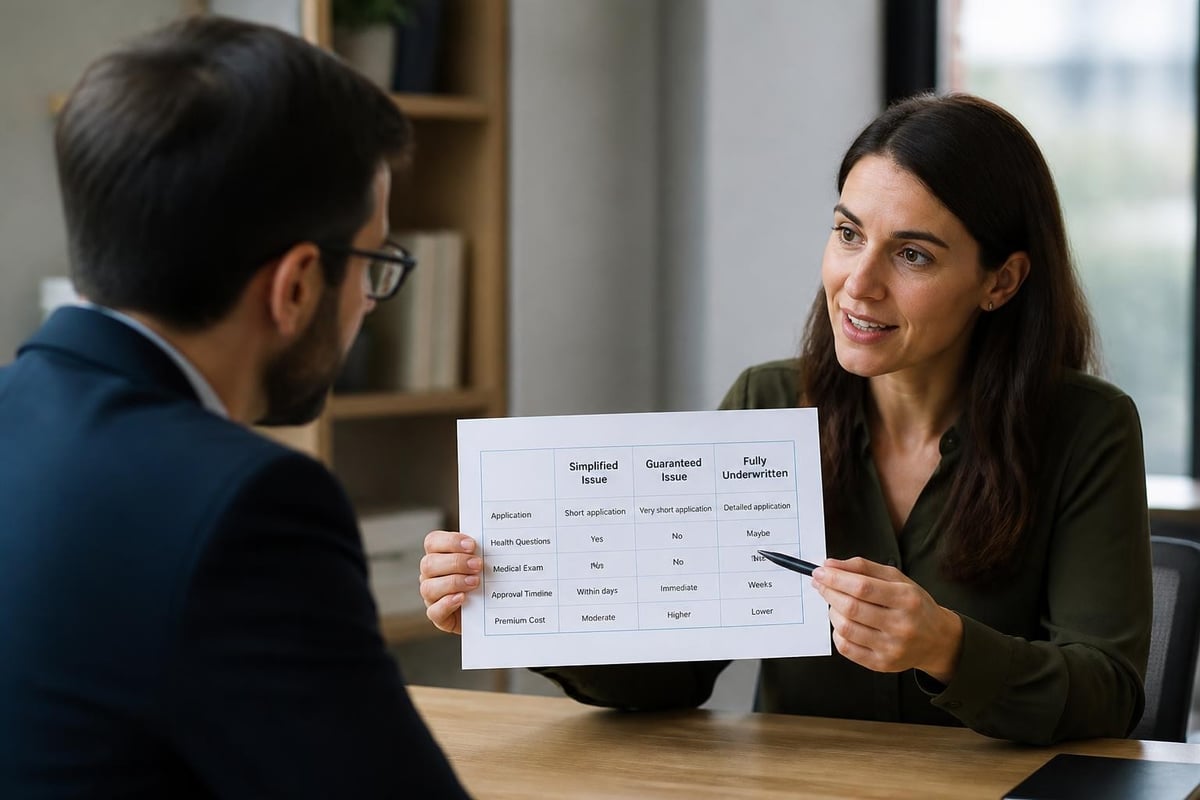
Traditional decreasing term policies typically require full medical underwriting, including health questionnaires, medical records review, and sometimes paramedical examinations. This process takes two to six weeks but often results in lower premiums for healthy applicants.
Some lender-offered mortgage life insurance products feature simplified or guaranteed issue underwriting, meaning minimal or no medical questions. While this speeds up approval and guarantees coverage, it comes at a significant premium increase, sometimes 50-100% higher than medically underwritten policies.
Strategic Alternatives and Hybrid Approaches
Rather than viewing decreasing mortgage life insurance as an all-or-nothing proposition, many financial advisors recommend hybrid strategies that provide both mortgage protection and broader coverage.
The Laddering Strategy
Life insurance laddering involves purchasing multiple term policies with different coverage amounts and term lengths to create a customized coverage profile that decreases over time while maintaining flexibility.
For example, instead of a single $300,000 decreasing term policy, you might purchase:
- A $100,000 30-year level term policy for permanent baseline protection
- A $100,000 20-year level term policy for intermediate-term needs
- A $100,000 10-year level term policy for maximum current coverage
This approach provides $300,000 in total coverage initially, reducing to $200,000 after 10 years and $100,000 after 20 years. While the total premium might be slightly higher than a decreasing term policy, you maintain the flexibility to convert, extend, or cash out individual policies as circumstances change.
The advantages and disadvantages of decreasing term insurance become less significant when you can customize your coverage decline rate to match your specific situation rather than accepting a predetermined schedule.
Combining Decreasing Coverage With Permanent Insurance
Another strategic approach combines affordable decreasing term coverage for your mortgage with a smaller permanent policy for lifetime needs. This hybrid strategy acknowledges that your insurance needs extend beyond just mortgage protection.
For instance, you might purchase a $200,000 decreasing term policy to cover your mortgage alongside a $50,000 Whole Life Insurance policy that builds cash value and provides permanent protection. The whole life component ensures your family receives at least some death benefit regardless of when you pass away, while the decreasing term handles the temporary need of mortgage coverage.
This combination often costs less than a large level term policy while providing both temporary high coverage and permanent baseline protection. For Kernersville families balancing multiple financial priorities, this balance can offer the best of both worlds.
Common Mistakes to Avoid With Decreasing Mortgage Life Insurance
Understanding potential pitfalls helps you navigate the decision-making process more effectively. Many homeowners make preventable errors when purchasing this specialized coverage.
Frequent mistakes include:
- Purchasing through your mortgage lender without comparing alternatives – Lender-offered policies often cost significantly more than policies purchased independently while offering less flexibility
- Failing to account for refinancing possibilities – If you refinance to a new 30-year mortgage after 10 years, your decreasing coverage won't align with the new loan balance
- Ignoring inflation – The purchasing power of your coverage decreases over time, potentially leaving your family underinsured even if the nominal amount covers the mortgage
- Not considering other debts and income replacement – Your family's financial needs extend beyond just the mortgage payment
- Choosing coverage based solely on premium cost – The cheapest policy may not provide the best value or appropriate coverage structure
According to comprehensive insurance definitions and comparisons, the most common regret among decreasing term policyholders involves insufficient coverage for non-mortgage needs when the unexpected occurs.
Understanding Policy Conversion Options
One frequently overlooked feature in some decreasing term policies is the conversion privilege. This provision allows you to convert your decreasing term policy to a permanent policy without additional medical underwriting.
Conversion options provide valuable flexibility if your health deteriorates during the policy term or if your insurance needs change. However, not all decreasing term policies include this feature, and those that do often limit conversion to specific timeframes, typically the first 10-15 years of the policy.
When evaluating policies, ask specifically about conversion privileges, what policy types you can convert to, any deadlines for conversion, and whether the new policy requires higher premiums based on your current age.
Regional Considerations for Triad Area Residents
Homeowners in Greensboro, Winston Salem, High Point, Kernersville, and throughout the Triad Area face specific considerations when evaluating decreasing mortgage life insurance that differ from national averages.
Local factors affecting decisions include:
- Housing market stability – The Triad's relatively stable real estate market means less refinancing volatility compared to coastal areas
- Cost of living – Lower housing costs mean smaller mortgages, potentially making the premium savings from decreasing coverage more impactful
- Employment patterns – Mixed employment sectors suggest diversified coverage needs beyond just mortgage protection
- Family structures – Strong multigenerational family connections in the region may provide additional financial safety nets
The median home price in the Triad Area hovers around $220,000-$280,000 depending on the specific city, which represents a moderate mortgage burden compared to national figures. This moderate debt level means families might benefit more from comprehensive level term coverage rather than mortgage-specific decreasing coverage.
Working With Local Insurance Advisors
Navigating life insurance options benefits significantly from personalized guidance that accounts for your specific circumstances, budget, and family situation. Independent advisors can compare multiple carriers and policy types to find the optimal solution.
Unlike captive agents who represent single insurance companies or lenders offering their own mortgage life products, independent advisors in the Triad Area can access dozens of carriers and hundreds of policy options. This access ensures you're not limited to one-size-fits-all solutions.
For questions about how different life insurance options might serve your mortgage protection and broader family needs, reaching out to local experts who understand both insurance products and regional considerations provides clarity. You can contact Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your specific situation and explore options available at moserinsurancegroup.com.
Premium Factors and Cost Management Strategies
Understanding what drives premium costs for decreasing mortgage life insurance helps you identify opportunities to reduce expenses while maintaining adequate protection. Multiple variables influence your quoted rates.
| Factor | Impact on Premium | Optimization Strategy |
|---|---|---|
| Age | Higher age = higher premium | Purchase when younger |
| Health status | Poor health = higher premium | Improve health before applying |
| Tobacco use | Smokers pay 2-3x more | Quit smoking 12+ months before applying |
| Coverage amount | Higher amount = higher premium | Match coverage to actual need |
| Term length | Longer term = higher premium | Choose term matching mortgage |
| Gender | Males typically pay more | N/A – cannot change |
Your health classification significantly impacts premiums. Insurers typically use categories like Preferred Plus, Preferred, Standard Plus, Standard, and Substandard. The difference between Preferred Plus and Standard rates can exceed 40% for the same coverage.
Simple lifestyle changes implemented before applying can dramatically reduce costs. Losing weight, managing cholesterol or blood pressure, quitting tobacco, and addressing other controllable health factors can move you into better rating classes. Some applicants save thousands of dollars over the policy term by delaying application three to six months while improving their health profile.
Policy Riders and Additional Features
While decreasing mortgage life insurance emphasizes simplicity, several optional riders can enhance the coverage for minimal additional cost. Understanding these options helps you customize protection to your needs.
Common valuable riders include:
- Waiver of premium – Continues coverage without premium payments if you become disabled
- Accelerated death benefit – Allows access to death benefit if diagnosed with terminal illness
- Child term rider – Adds coverage for children at low cost
- Accidental death benefit – Pays additional benefit for accidental death
The waiver of premium rider deserves special consideration for mortgage protection. If you become disabled and cannot work, this rider ensures your mortgage protection remains in force even though you're not paying premiums. Given that disability risk often exceeds death risk during working years, this relatively inexpensive addition provides valuable protection.
Evaluating Your Long-Term Insurance Needs
Decreasing mortgage life insurance addresses one specific need: protecting your family from mortgage debt if you die prematurely. However, comprehensive financial planning requires broader consideration of your family's total protection needs.
Financial experts typically recommend life insurance coverage equal to 10-12 times your annual income, or enough to replace your income for 10-15 years while also covering major debts and expenses. For someone earning $60,000 annually with a $200,000 mortgage, this suggests total coverage of $600,000-$720,000, far exceeding the mortgage alone.
This broader perspective reveals that decreasing mortgage life insurance might serve as one component of a comprehensive insurance strategy but rarely provides sufficient total protection by itself. Research on decreasing term applications confirms that most financial planners view it as supplementary rather than primary coverage.
Life Stage Considerations
Your insurance needs evolve throughout your life, and the type of coverage that makes sense changes accordingly. Understanding this progression helps you make strategic decisions about decreasing mortgage life insurance timing.
Early career (ages 25-35): Maximum coverage needs with minimum budget. Level term provides best value and flexibility. Decreasing coverage might leave you underinsured.
Mid-career with young children (ages 35-50): Peak coverage needs including mortgage, income replacement, and education funding. Combination of term policies or laddering strategy often works best.
Late career with older children (ages 50-60): Declining coverage needs as mortgage decreases and children become independent. Decreasing coverage or reducing ladder policies makes sense.
Pre-retirement (ages 60+): Minimal coverage needs if assets have accumulated. Small permanent policy for final expenses may replace term coverage entirely.
This progression suggests that decreasing mortgage life insurance makes most sense for mid-to-late career individuals whose primary remaining debt is their mortgage and whose children are largely independent.
Tax Implications and Estate Planning Considerations
While life insurance death benefits generally pass to beneficiaries tax-free, several tax and estate planning considerations affect how decreasing mortgage life insurance fits into your overall financial picture.
The primary tax advantage of life insurance is that death benefits are not subject to federal income tax. If you have a $200,000 decreasing term policy and pass away when the death benefit has declined to $120,000, your beneficiaries receive the full $120,000 without income tax consequences.
However, life insurance proceeds do count toward your gross estate for estate tax purposes. In 2026, the federal estate tax exemption stands at $13.99 million per individual, so most families face no estate tax concerns. For high-net-worth individuals, properly structuring life insurance ownership through irrevocable life insurance trusts can remove proceeds from the taxable estate.
Beneficiary Designation Strategies
How you designate beneficiaries affects both tax efficiency and estate settlement processes. Properly structured beneficiary designations can avoid probate, provide immediate access to funds, and protect assets from creditors.
Primary options include:
- Individual beneficiaries – Spouse, children, or other individuals receive proceeds directly
- Trust as beneficiary – Proceeds flow into trust for controlled distribution
- Estate as beneficiary – Proceeds become part of probate estate (generally avoid this option)
- Contingent beneficiaries – Backup recipients if primary beneficiaries predecease you
For mortgage protection specifically, naming your spouse as primary beneficiary and your children as contingent beneficiaries typically makes sense. This structure ensures your spouse has immediate access to funds for mortgage payments while protecting children's interests if both spouses die simultaneously.
Always review and update beneficiary designations after major life events such as marriage, divorce, births, or deaths. Outdated beneficiary designations create significant complications and may result in proceeds going to unintended recipients.
Making Your Decision: A Practical Framework
Determining whether decreasing mortgage life insurance serves your needs requires honest assessment of your financial situation, family obligations, and future plans. This framework provides structure for your decision-making process.
Step 1: Calculate total insurance needs
- Income replacement (annual income × 10-12)
- Outstanding mortgage balance
- Other debts (auto loans, student loans, credit cards)
- Education funding for children
- Final expenses and estate settlement costs
- Emergency fund enhancement
Step 2: Evaluate existing coverage
- Employer-provided group life insurance
- Existing individual policies
- Military or veteran benefits
- Accidental death coverage through other policies
Step 3: Determine coverage gap
Total needs minus existing coverage equals your insurance gap. This number guides your purchase decision.
Step 4: Compare policy options
Get quotes for decreasing term, level term, and combination approaches. Consider both premium costs and total coverage value over the policy term.
Step 5: Project future changes
Consider potential refinancing, home upgrades, additional children, career changes, or other life events that might affect your needs.
If your coverage gap approximately equals your mortgage balance, you anticipate no significant life changes, and you have other assets to support your family beyond mortgage coverage, decreasing mortgage life insurance might serve you well. If your gap exceeds your mortgage or you anticipate significant changes, level term or combination approaches likely provide better value and flexibility.
Decreasing mortgage life insurance offers an affordable way to protect your family from mortgage debt, particularly when budget constraints limit your options or when your primary insurance need involves covering a declining loan balance. However, understanding its limitations, comparing alternatives, and evaluating your comprehensive insurance needs ensures you make the right choice for your family's protection. Whether you're exploring life insurance options for the first time or reevaluating existing coverage, personalized guidance helps navigate the complexity of matching products to needs. At Moser Insurance Group Inc, we help families throughout the Triad Area understand their life insurance and protection options without pressure, ensuring you make confident decisions that serve your family's long-term interests. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss which life insurance approach best fits your situation.
Recent Comments